
Muhammad BR Crypto
72 Publicaciones

Muhammad BR Crypto
Denunciar
Bloquear usuario
36 Siguiendo
232 Seguidores
46 Me gusta
Publicaciones
Todo
Citas
Live
Responde y obtén una recompensa
10+10
Responde y obtén una recompensa
10+10
10+10
104
2
7
104
Ver traducción
#BinancePick Day by day, I'm climbing the Scores leaderboard on #BinancePick. Completing markets, making smart predictions, and enjoying every step of the campaign! 📈
#BinancePick Day by day, I'm climbing the Scores leaderboard on #BinancePick. Completing markets, making smart predictions, and enjoying every step of the campaign! 📈
1
Ver traducción
#BinancePick Just joined Binance Pick and it's a fun way to put my market predictions to the test! Pick your markets, make your calls, and earn Scores along the way. Can't wait to see how many I can unlock this week.
#BinancePick Just joined Binance Pick and it's a fun way to put my market predictions to the test! Pick your markets, make your calls, and earn Scores along the way. Can't wait to see how many I can unlock this week.
9
Ver traducción
#BinancePick Just joined Binance Pick and it's a fun way to put my market predictions to the test! Pick your markets, make your calls, and earn Scores along the way. Can't wait to see how many I can unlock this week.
#BinancePick Just joined Binance Pick and it's a fun way to put my market predictions to the test! Pick your markets, make your calls, and earn Scores along the way. Can't wait to see how many I can unlock this week.
11
Ver traducción
#BinancePick Prediction markets make crypto even more exciting. Participating in #BinancePick daily to complete tasks and climb the leaderboard.
#BinancePick Prediction markets make crypto even more exciting. Participating in #BinancePick daily to complete tasks and climb the leaderboard.
3
🎙️ Hoy, dos eventos de recompensas en airdrops de BNB
Finalizado
02 h 44 m 47 s
12.2k
37
23
Ver traducción
#BinancePick Prediction Market se market samajhna mazedaar hai. Bina FOMO ke, sahi analysis ke saath predict karo!
#BinancePick Prediction Market se market samajhna mazedaar hai. Bina FOMO ke, sahi analysis ke saath predict karo!
Ver traducción
#BinancePick Prediction markets make trading feel more interactive. I'm taking my time to research each market on Binance Pick before making a call. Who else is participating?
#BinancePick Prediction markets make trading feel more interactive. I'm taking my time to research each market on Binance Pick before making a call. Who else is participating?
Ver traducción
#BinancePick Prediction markets make crypto even more exciting. Participating daily to complete tasks and climb the leaderboard. Who else is in?
#BinancePick Prediction markets make crypto even more exciting. Participating daily to complete tasks and climb the leaderboard. Who else is in?
3
Ver traducción
#BinancePick Just completed today's #BinancePick task! Joining prediction markets is a fresh, fun way to understand crypto better. Have you tried Predict yet? ?
#BinancePick Just completed today's #BinancePick task! Joining prediction markets is a fresh, fun way to understand crypto better. Have you tried Predict yet? ?
63
Ver traducción
#BinancePick Prediction markets are a whole new way to put your insights to work. 📊 On Binance Pick, you can back your read on different markets and earn rewards along the way. Joined a few markets today. Give it a try!
#BinancePick Prediction markets are a whole new way to put your insights to work. 📊 On Binance Pick, you can back your read on different markets and earn rewards along the way. Joined a few markets today. Give it a try!
53
Ver traducción
#BinancePick
Prediction markets mein hissa lena ek naya aur interesting experience hai! Market trends ko samajh kar sahi predict karna sach mein maza deta hai.
#BinancePick
Prediction markets mein hissa lena ek naya aur interesting experience hai! Market trends ko samajh kar sahi predict karna sach mein maza deta hai.
Prediction markets mein hissa lena ek naya aur interesting experience hai! Market trends ko samajh kar sahi predict karna sach mein maza deta hai.
66
Ver traducción
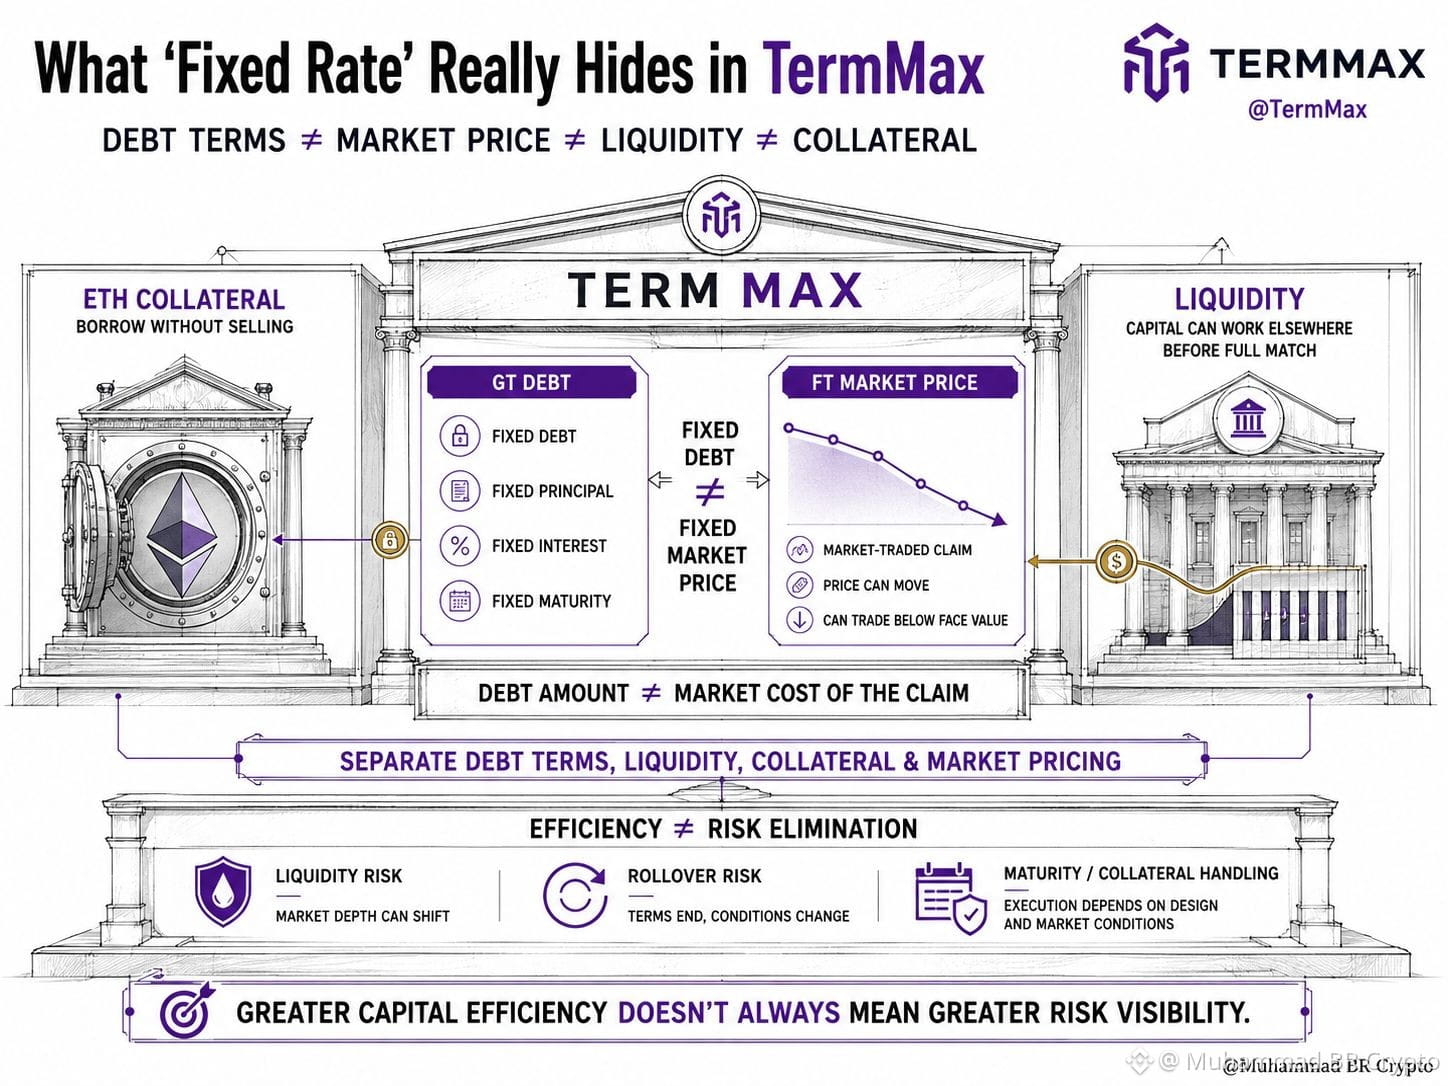
#termmax @termmax I used to think the interesting part of TermMax was simply fixed-rate borrowing. The more I looked at how its products connect, the more I realized that was only the surface.
A borrower can use ETH as collateral without selling it, while lenders can have capital working elsewhere even before an order is fully matched. But large protocol TVL doesn’t necessarily mean deep liquidity or easy execution in every market.
What really changed my view was seeing how differently capital behaves depending on where it sits. A GT debt can remain fixed while the FT linked to that debt trades below face value — so the amount of debt and the market cost of acquiring the claim are not necessarily the same.
That made me see @termmax less as a simple lending market and more as an attempt to separate debt terms, liquidity, collateral and market pricing instead of treating them as one thing.
The trade-off is that this can improve capital efficiency, but it doesn’t automatically remove liquidity or rollover risk — especially as a position approaches maturity or collateral needs to be handled after a default.
The bigger question, then, isn’t simply whether @termmax makes capital more efficient. It’s whether separating debt, liquidity, collateral and market pricing makes capital easier to manage — or simply makes the risks harder to see.
#termmax @TermMax I used to think the interesting part of TermMax was simply fixed-rate borrowing. The more I looked at how its products connect, the more I realized that was only the surface.
A borrower can use ETH as collateral without selling it, while lenders can have capital working elsewhere even before an order is fully matched. But large protocol TVL doesn’t necessarily mean deep liquidity or easy execution in every market.
What really changed my view was seeing how differently capital behaves depending on where it sits. A GT debt can remain fixed while the FT linked to that debt trades below face value — so the amount of debt and the market cost of acquiring the claim are not necessarily the same.
That made me see @TermMax less as a simple lending market and more as an attempt to separate debt terms, liquidity, collateral and market pricing instead of treating them as one thing.
The trade-off is that this can improve capital efficiency, but it doesn’t automatically remove liquidity or rollover risk — especially as a position approaches maturity or collateral needs to be handled after a default.
The bigger question, then, isn’t simply whether @TermMax makes capital more efficient. It’s whether separating debt, liquidity, collateral and market pricing makes capital easier to manage — or simply makes the risks harder to see.
A borrower can use ETH as collateral without selling it, while lenders can have capital working elsewhere even before an order is fully matched. But large protocol TVL doesn’t necessarily mean deep liquidity or easy execution in every market.
What really changed my view was seeing how differently capital behaves depending on where it sits. A GT debt can remain fixed while the FT linked to that debt trades below face value — so the amount of debt and the market cost of acquiring the claim are not necessarily the same.
That made me see @TermMax less as a simple lending market and more as an attempt to separate debt terms, liquidity, collateral and market pricing instead of treating them as one thing.
The trade-off is that this can improve capital efficiency, but it doesn’t automatically remove liquidity or rollover risk — especially as a position approaches maturity or collateral needs to be handled after a default.
The bigger question, then, isn’t simply whether @TermMax makes capital more efficient. It’s whether separating debt, liquidity, collateral and market pricing makes capital easier to manage — or simply makes the risks harder to see.
2
82
Ver traducción
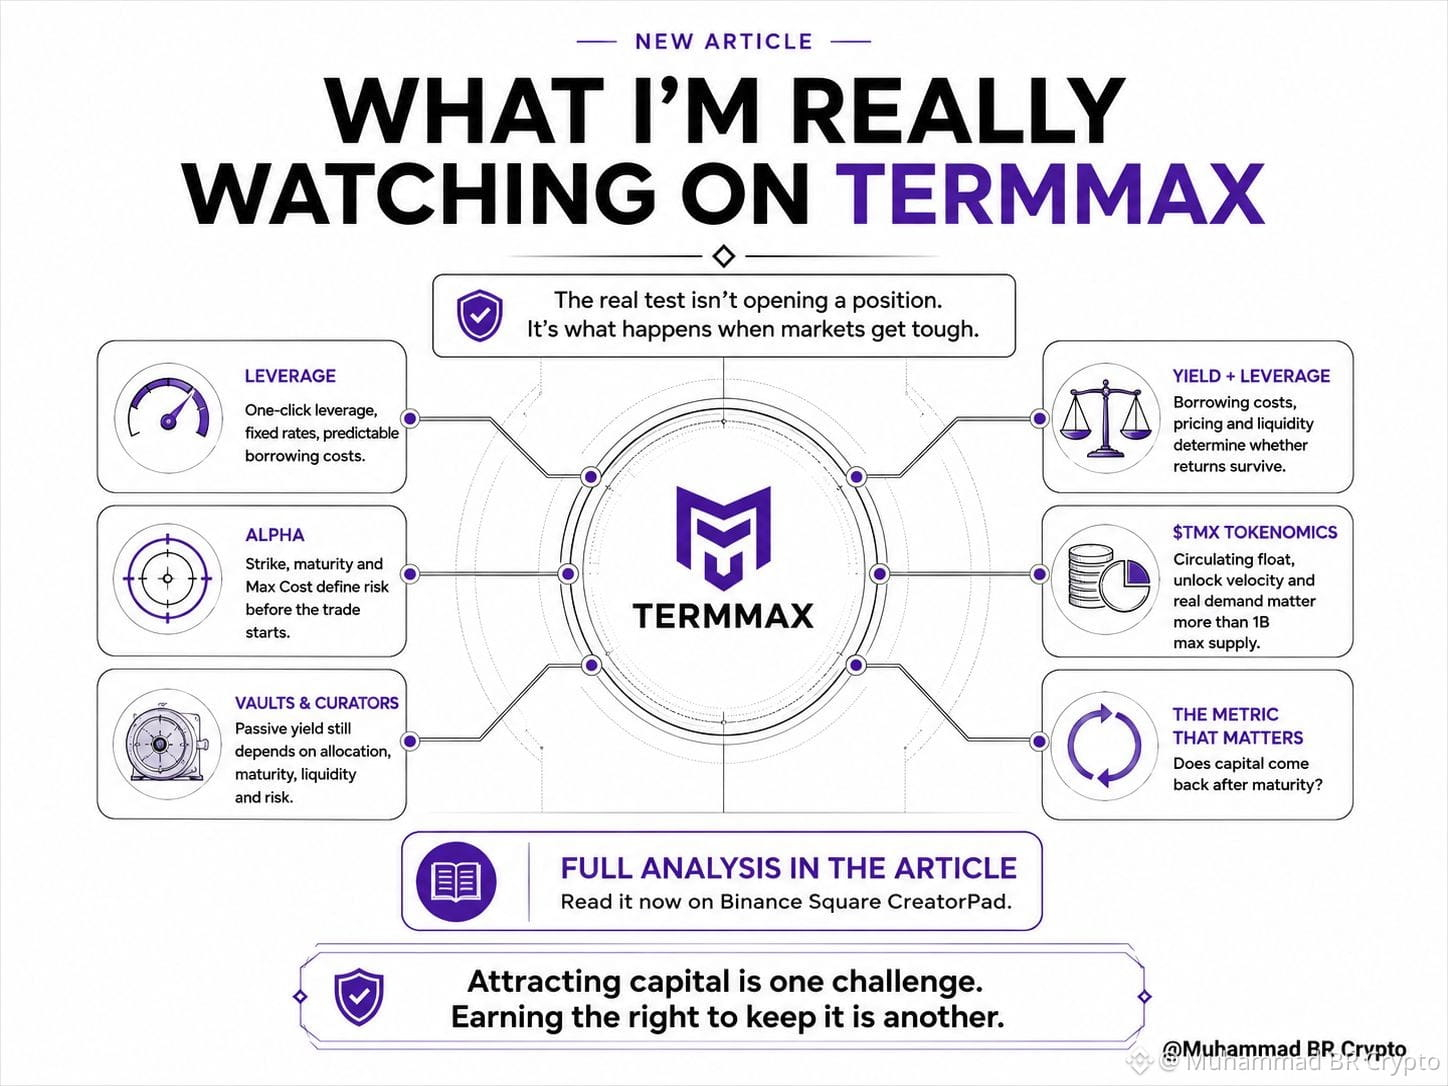
#termmax @termmax I’ve been looking at @TermMax from different angles over the last few days, and I keep coming back to one question:
Is TermMax actually making DeFi simpler, or just making complexity easier to access?
One-click leverage is a good example. It bundles multiple steps into one transaction, while fixed rates make borrowing costs more predictable.
Alpha takes the same idea into risk management. Strike, maturity and Max Cost define the trade before it starts. The market can still move against you, but the downside has a clearer boundary.
Then there’s the Vault and Curator layer.
Passive yield doesn’t remove risk. It shifts the responsibility of choosing markets, maturities, liquidity and risk levels to another layer.
That matters even more with leverage and yield-bearing assets, where borrowing costs, pricing and liquidity can determine whether the expected return actually survives.
Even TMX tokenomics points to the same lesson. The 1B maximum supply matters less than circulating float, unlock velocity and real demand.
And I’m less interested in headline wallet counts or TVL than one simple metric:
Does capital come back after maturity?
Because the real test isn’t opening a position when markets are calm.
It’s what happens when volatility rises, liquidity gets tight and users want to unwind.
Attracting capital is one challenge. Earning the right to keep it is another.
#termmax @TermMax I’ve been looking at @TermMax from different angles over the last few days, and I keep coming back to one question:
Is TermMax actually making DeFi simpler, or just making complexity easier to access?
One-click leverage is a good example. It bundles multiple steps into one transaction, while fixed rates make borrowing costs more predictable.
Alpha takes the same idea into risk management. Strike, maturity and Max Cost define the trade before it starts. The market can still move against you, but the downside has a clearer boundary.
Then there’s the Vault and Curator layer.
Passive yield doesn’t remove risk. It shifts the responsibility of choosing markets, maturities, liquidity and risk levels to another layer.
That matters even more with leverage and yield-bearing assets, where borrowing costs, pricing and liquidity can determine whether the expected return actually survives.
Even TMX tokenomics points to the same lesson. The 1B maximum supply matters less than circulating float, unlock velocity and real demand.
And I’m less interested in headline wallet counts or TVL than one simple metric:
Does capital come back after maturity?
Because the real test isn’t opening a position when markets are calm.
It’s what happens when volatility rises, liquidity gets tight and users want to unwind.
Attracting capital is one challenge. Earning the right to keep it is another.
Is TermMax actually making DeFi simpler, or just making complexity easier to access?
One-click leverage is a good example. It bundles multiple steps into one transaction, while fixed rates make borrowing costs more predictable.
Alpha takes the same idea into risk management. Strike, maturity and Max Cost define the trade before it starts. The market can still move against you, but the downside has a clearer boundary.
Then there’s the Vault and Curator layer.
Passive yield doesn’t remove risk. It shifts the responsibility of choosing markets, maturities, liquidity and risk levels to another layer.
That matters even more with leverage and yield-bearing assets, where borrowing costs, pricing and liquidity can determine whether the expected return actually survives.
Even TMX tokenomics points to the same lesson. The 1B maximum supply matters less than circulating float, unlock velocity and real demand.
And I’m less interested in headline wallet counts or TVL than one simple metric:
Does capital come back after maturity?
Because the real test isn’t opening a position when markets are calm.
It’s what happens when volatility rises, liquidity gets tight and users want to unwind.
Attracting capital is one challenge. Earning the right to keep it is another.
2
75
Ver traducción
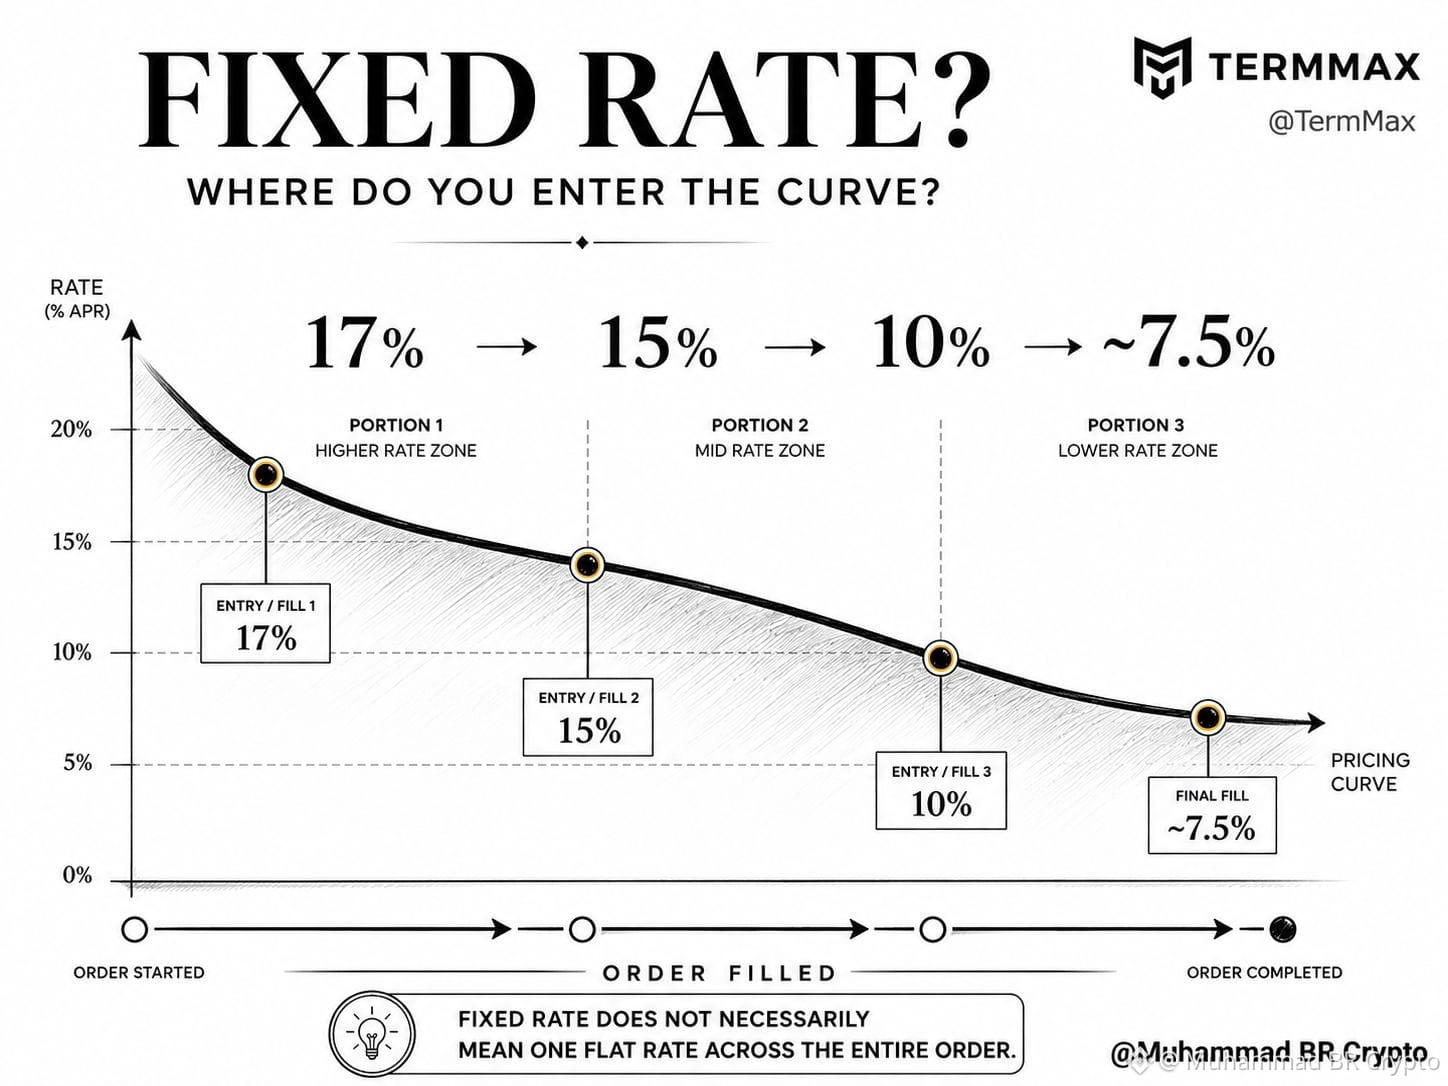
#termmax @termmax I thought “fixed rate” on @termmax meant one rate across an entire order.
Then I looked closer at how Range Orders actually work and realized I was oversimplifying it.
They’re built from pricing curves, not flat rates. In TermMax’s borrowing example, the first 1.5M ranges from 17% toward 15%, the next 0.2M from 15% toward 10%, and the final 0.17M from 10% toward roughly 7.5%.
So once your portion is matched, its rate is fixed — but different portions can lock in different rates depending on where they’re matched on the curve.
That makes the order’s fill position more important than I initially thought.
For a taker, should the first question be “what’s the rate?” — or “where am I entering the curve?”
#termmax @TermMax I thought “fixed rate” on @TermMax meant one rate across an entire order.
Then I looked closer at how Range Orders actually work and realized I was oversimplifying it.
They’re built from pricing curves, not flat rates. In TermMax’s borrowing example, the first 1.5M ranges from 17% toward 15%, the next 0.2M from 15% toward 10%, and the final 0.17M from 10% toward roughly 7.5%.
So once your portion is matched, its rate is fixed — but different portions can lock in different rates depending on where they’re matched on the curve.
That makes the order’s fill position more important than I initially thought.
For a taker, should the first question be “what’s the rate?” — or “where am I entering the curve?”
Then I looked closer at how Range Orders actually work and realized I was oversimplifying it.
They’re built from pricing curves, not flat rates. In TermMax’s borrowing example, the first 1.5M ranges from 17% toward 15%, the next 0.2M from 15% toward 10%, and the final 0.17M from 10% toward roughly 7.5%.
So once your portion is matched, its rate is fixed — but different portions can lock in different rates depending on where they’re matched on the curve.
That makes the order’s fill position more important than I initially thought.
For a taker, should the first question be “what’s the rate?” — or “where am I entering the curve?”
1
79
Ver traducción
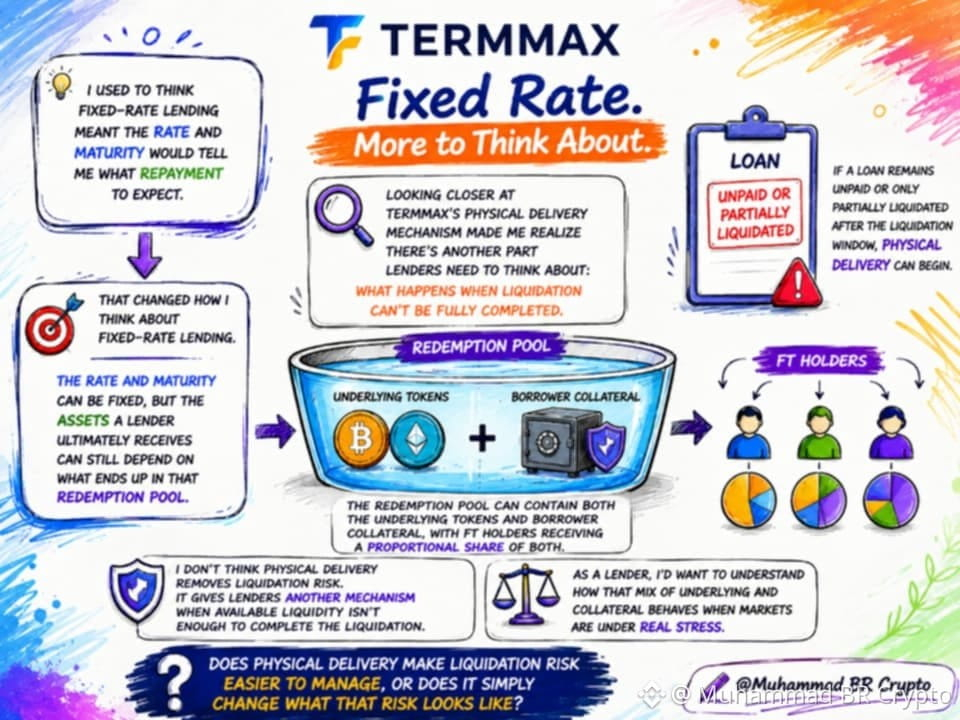
#termmax @termmax I used to think fixed-rate lending was mainly about knowing the rate and maturity upfront.
But looking closer at @termmax physical delivery mechanism made me realize there’s another question: what happens when liquidation can’t be fully completed?
If a loan remains unpaid or only partially liquidated after the liquidation window, physical delivery can begin. The redemption pool can contain both the underlying tokens and borrower collateral, with FT holders receiving a proportional share of both.
That changed how I think about fixed-rate lending.
The rate and maturity can be fixed, but what a lender ultimately receives can still depend on what ends up in that pool.
That’s also where I see the practical value of TermMax: lenders can target fixed returns, borrowers can access defined-rate liquidity, and LPs can provide liquidity to the market.
I don’t think physical delivery removes liquidation risk. It gives lenders another mechanism when available liquidity isn’t enough to complete the liquidation.
Does physical delivery make liquidation risk easier to manage, or simply change what that risk looks like?
#termmax @TermMax I used to think fixed-rate lending was mainly about knowing the rate and maturity upfront.
But looking closer at @TermMax physical delivery mechanism made me realize there’s another question: what happens when liquidation can’t be fully completed?
If a loan remains unpaid or only partially liquidated after the liquidation window, physical delivery can begin. The redemption pool can contain both the underlying tokens and borrower collateral, with FT holders receiving a proportional share of both.
That changed how I think about fixed-rate lending.
The rate and maturity can be fixed, but what a lender ultimately receives can still depend on what ends up in that pool.
That’s also where I see the practical value of TermMax: lenders can target fixed returns, borrowers can access defined-rate liquidity, and LPs can provide liquidity to the market.
I don’t think physical delivery removes liquidation risk. It gives lenders another mechanism when available liquidity isn’t enough to complete the liquidation.
Does physical delivery make liquidation risk easier to manage, or simply change what that risk looks like?
But looking closer at @TermMax physical delivery mechanism made me realize there’s another question: what happens when liquidation can’t be fully completed?
If a loan remains unpaid or only partially liquidated after the liquidation window, physical delivery can begin. The redemption pool can contain both the underlying tokens and borrower collateral, with FT holders receiving a proportional share of both.
That changed how I think about fixed-rate lending.
The rate and maturity can be fixed, but what a lender ultimately receives can still depend on what ends up in that pool.
That’s also where I see the practical value of TermMax: lenders can target fixed returns, borrowers can access defined-rate liquidity, and LPs can provide liquidity to the market.
I don’t think physical delivery removes liquidation risk. It gives lenders another mechanism when available liquidity isn’t enough to complete the liquidation.
Does physical delivery make liquidation risk easier to manage, or simply change what that risk looks like?
2
57
Ver traducción
#dusk $DUSK I used to think more transparency automatically meant more trust in financial blockchains. But the more I look at @Dusk_Foundation , the less convincing that assumption feels.
In regulated finance, institutions need to prove eligibility and compliance without necessarily exposing every underlying detail. Dusk’s programmable privacy approach caught my attention because it aims for privacy where needed, transparency where useful, and selective disclosure when authorized.
That makes me look at Hedger differently too. Its homomorphic encryption and zero-knowledge proofs aren’t simply about hiding information; they enable confidential transaction flows while preserving the ability to verify relevant information when needed.
The real tension is interesting: can regulated markets have strong privacy without giving up verifiability?
Could programmable disclosure be the missing piece?
#dusk $DUSK I used to think more transparency automatically meant more trust in financial blockchains. But the more I look at @Dusk , the less convincing that assumption feels.
In regulated finance, institutions need to prove eligibility and compliance without necessarily exposing every underlying detail. Dusk’s programmable privacy approach caught my attention because it aims for privacy where needed, transparency where useful, and selective disclosure when authorized.
That makes me look at Hedger differently too. Its homomorphic encryption and zero-knowledge proofs aren’t simply about hiding information; they enable confidential transaction flows while preserving the ability to verify relevant information when needed.
The real tension is interesting: can regulated markets have strong privacy without giving up verifiability?
Could programmable disclosure be the missing piece?
In regulated finance, institutions need to prove eligibility and compliance without necessarily exposing every underlying detail. Dusk’s programmable privacy approach caught my attention because it aims for privacy where needed, transparency where useful, and selective disclosure when authorized.
That makes me look at Hedger differently too. Its homomorphic encryption and zero-knowledge proofs aren’t simply about hiding information; they enable confidential transaction flows while preserving the ability to verify relevant information when needed.
The real tension is interesting: can regulated markets have strong privacy without giving up verifiability?
Could programmable disclosure be the missing piece?
66
Ver traducción
😍
😍
Ahmad Wêb³
·
--
AlcistaProbé el flujo del bóveda Bitcoin sin confianza de Babylon y la parte que se quedó conmigo no fue pedir prestado BTC. Fue la espera después del bloqueo. Ese pequeño retraso mostró el verdadero compromiso: TBV se construye sobre verificación nativa de Bitcoin y reduce los supuestos de confianza, no sobre conveniencia inmediata de DeFi.
Luego miré el mercado.
$BABY cotiza alrededor de 0,0129 USD con una capitalización de mercado cercana a 50,7M USD, mientras que el token ha bajado aproximadamente un 9% en los últimos 7 días. El mercado todavía espera pruebas de que el crecimiento del ecosistema de Babylon puede traducirse en una demanda de tokens sostenible.
Pero el ecosistema cuenta otra historia.
El TVL de Babylon está alrededor de 3,25B USD, lo que muestra que el protocolo ya está conectado a un valor significativo en BTC. La pregunta clave es si esta actividad genera una captura de valor real para $BABY mediante la adopción y el crecimiento de la red.
Por el lado de la oferta hay otra capa.
BABY tiene alrededor de 4,02B de suministro en circulación de un total de 10,89B. El próximo desbloqueo el 10 de agosto libera 136,11M de tokens BABY, cerca de un 1,2% del suministro total, para asesores, inversores tempranos y asignaciones del equipo.
Así que el mercado está equilibrando dos cosas:
¿Puede Babylon convertir la adopción de BTC en una demanda de tokens duradera, mientras gestiona la expansión futura de la oferta?
El verdadero desafío puede no ser construir infraestructura de Bitcoin; puede ser demostrar que los titulares de Bitcoin elegirán este modelo de confianza frente a alternativas más rápidas.
¿Babylon se convertirá en la capa que lleve liquidez seria de BTC hacia DeFi, o la conveniencia seguirá ganando?
@BabylonLabs_io
#baby $BABY
Luego miré el mercado.
$BABY cotiza alrededor de 0,0129 USD con una capitalización de mercado cercana a 50,7M USD, mientras que el token ha bajado aproximadamente un 9% en los últimos 7 días. El mercado todavía espera pruebas de que el crecimiento del ecosistema de Babylon puede traducirse en una demanda de tokens sostenible.
Pero el ecosistema cuenta otra historia.
El TVL de Babylon está alrededor de 3,25B USD, lo que muestra que el protocolo ya está conectado a un valor significativo en BTC. La pregunta clave es si esta actividad genera una captura de valor real para $BABY mediante la adopción y el crecimiento de la red.
Por el lado de la oferta hay otra capa.
BABY tiene alrededor de 4,02B de suministro en circulación de un total de 10,89B. El próximo desbloqueo el 10 de agosto libera 136,11M de tokens BABY, cerca de un 1,2% del suministro total, para asesores, inversores tempranos y asignaciones del equipo.
Así que el mercado está equilibrando dos cosas:
¿Puede Babylon convertir la adopción de BTC en una demanda de tokens duradera, mientras gestiona la expansión futura de la oferta?
El verdadero desafío puede no ser construir infraestructura de Bitcoin; puede ser demostrar que los titulares de Bitcoin elegirán este modelo de confianza frente a alternativas más rápidas.
¿Babylon se convertirá en la capa que lleve liquidez seria de BTC hacia DeFi, o la conveniencia seguirá ganando?
@BabylonLabs_io
#baby $BABY
2
España vs Argentina se siente como una rivalidad clásica del fútbol en el escenario más grande. ⚽ Ambos equipos tienen delanteros de clase mundial, mediocampistas creativos y defensas sólidas. Estoy esperando una final de alta intensidad, con muchas ocasiones y momentos dramáticos. Mi pronóstico: un partido entretenido que llega hasta el pitido final. ¿A quién apoyas esta noche? #BinancePickAndWin
España vs Argentina se siente como una rivalidad clásica del fútbol en el escenario más grande. ⚽ Ambos equipos tienen delanteros de clase mundial, mediocampistas creativos y defensas sólidas. Estoy esperando una final de alta intensidad, con muchas ocasiones y momentos dramáticos. Mi pronóstico: un partido entretenido que llega hasta el pitido final. ¿A quién apoyas esta noche? #BinancePickAndWin
74
Inicia sesión para explorar más contenidos
Únete a usuarios globales de criptomonedas en Binance Square
⚡️ Obtén información útil y actualizada sobre criptos.
💬 Avalado por el mayor exchange de criptomonedas en el mundo.
👍 Descubre perspectivas reales de creadores verificados.
Email/número de teléfono
Temas populares
BTCRemainsUnderPressureAfterHawkishFOMCMinutes
28,323 vistas
411 están debatiendo
Actas del FOMC | Las actas de la Fed muestran que casi todos los funcionarios prevén más subidas de tasas, y algunos están abiertos a un aumento mayor en diciembre
Binance News
·42 me gusta
·52.3k vistas
AnthropicToDebutAfter$83IPOPricing
8,883 vistas
49 están debatiendo
NvidiaBoardReportedlySplitOverHuang’sReturn
7,204 vistas
127 están debatiendo