
REACHER _Crypto
8.6k Posts
REACHER _Crypto
Report
Block User
Web3 boy I Crypto never sleeps neither do profits Turning volatility into opportunity I Think. Trade. Earn. Repeat. #BinanceLife
489 Following
19.7K+ Followers
11.3K+ Liked
Posts
All
Quotes
Videos
Live
Verified
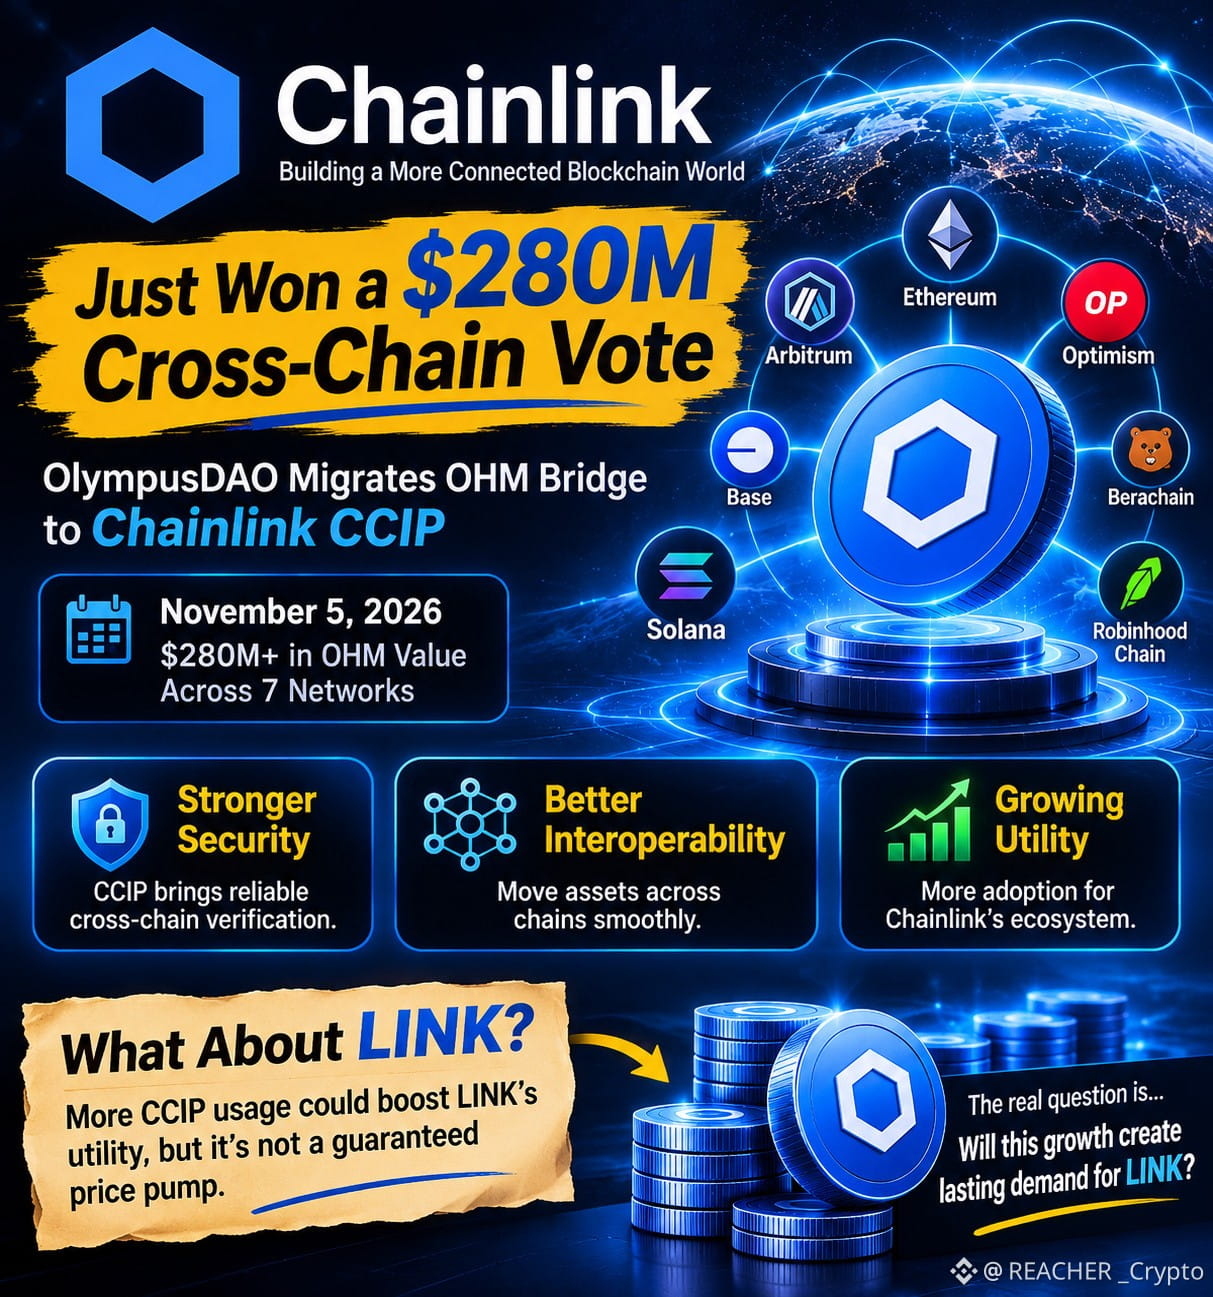
I've been looking at Chainlink's latest development, and I think there is an important lesson here about where blockchain infrastructure is heading.
On November 5, OlympusDAO's migration to Chainlink's Cross-Chain Interoperability Protocol (CCIP) brought attention to a major infrastructure change. Olympus moved its OHM bridging system from LayerZero to Chainlink, covering more than $280 million in OHM value across seven blockchain networks.
But why does this matter?
Let's understand it simply.
Different blockchains operate independently. For example, Ethereum and Arbitrum cannot automatically communicate or transfer assets between each other. A bridge solves this problem by verifying transfers and coordinating them across networks.
That's exactly where Chainlink CCIP comes in.
Olympus now uses CCIP to manage OHM transfers across Ethereum, Arbitrum, Optimism, Base, Berachain, Solana and Robinhood Chain.
One interesting part is its token mechanism. When OHM moves from Ethereum to another supported network, the Ethereum tokens are locked and corresponding OHM is minted on the destination chain. When it returns, the process works in reverse. This helps maintain the token's backing across networks.
For me, the bigger story is security and infrastructure. Cross-chain bridges have historically been a major target for hackers, so reliable verification, transfer limits and emergency controls are important.
Now let's connect this to LINK.
LINK is Chainlink's native token. It supports payments within the Chainlink ecosystem, including CCIP fees, alongside supported alternative payment methods. More CCIP adoption could strengthen its utility, but it does not guarantee an immediate increase in LINK demand or price.
I am watching whether this migration leads to more actual CCIP transactions, additional protocol integrations and sustainable fee activity.
The real competition in blockchain is not just about building faster networks. It is also about connecting them securely. And this is where Chainlink is trying to build its position.
$LINK
{future}(LINKUSDT)
I've been looking at Chainlink's latest development, and I think there is an important lesson here about where blockchain infrastructure is heading.
On November 5, OlympusDAO's migration to Chainlink's Cross-Chain Interoperability Protocol (CCIP) brought attention to a major infrastructure change. Olympus moved its OHM bridging system from LayerZero to Chainlink, covering more than $280 million in OHM value across seven blockchain networks.
But why does this matter?
Let's understand it simply.
Different blockchains operate independently. For example, Ethereum and Arbitrum cannot automatically communicate or transfer assets between each other. A bridge solves this problem by verifying transfers and coordinating them across networks.
That's exactly where Chainlink CCIP comes in.
Olympus now uses CCIP to manage OHM transfers across Ethereum, Arbitrum, Optimism, Base, Berachain, Solana and Robinhood Chain.
One interesting part is its token mechanism. When OHM moves from Ethereum to another supported network, the Ethereum tokens are locked and corresponding OHM is minted on the destination chain. When it returns, the process works in reverse. This helps maintain the token's backing across networks.
For me, the bigger story is security and infrastructure. Cross-chain bridges have historically been a major target for hackers, so reliable verification, transfer limits and emergency controls are important.
Now let's connect this to LINK.
LINK is Chainlink's native token. It supports payments within the Chainlink ecosystem, including CCIP fees, alongside supported alternative payment methods. More CCIP adoption could strengthen its utility, but it does not guarantee an immediate increase in LINK demand or price.
I am watching whether this migration leads to more actual CCIP transactions, additional protocol integrations and sustainable fee activity.
The real competition in blockchain is not just about building faster networks. It is also about connecting them securely. And this is where Chainlink is trying to build its position.
$LINK
On November 5, OlympusDAO's migration to Chainlink's Cross-Chain Interoperability Protocol (CCIP) brought attention to a major infrastructure change. Olympus moved its OHM bridging system from LayerZero to Chainlink, covering more than $280 million in OHM value across seven blockchain networks.
But why does this matter?
Let's understand it simply.
Different blockchains operate independently. For example, Ethereum and Arbitrum cannot automatically communicate or transfer assets between each other. A bridge solves this problem by verifying transfers and coordinating them across networks.
That's exactly where Chainlink CCIP comes in.
Olympus now uses CCIP to manage OHM transfers across Ethereum, Arbitrum, Optimism, Base, Berachain, Solana and Robinhood Chain.
One interesting part is its token mechanism. When OHM moves from Ethereum to another supported network, the Ethereum tokens are locked and corresponding OHM is minted on the destination chain. When it returns, the process works in reverse. This helps maintain the token's backing across networks.
For me, the bigger story is security and infrastructure. Cross-chain bridges have historically been a major target for hackers, so reliable verification, transfer limits and emergency controls are important.
Now let's connect this to LINK.
LINK is Chainlink's native token. It supports payments within the Chainlink ecosystem, including CCIP fees, alongside supported alternative payment methods. More CCIP adoption could strengthen its utility, but it does not guarantee an immediate increase in LINK demand or price.
I am watching whether this migration leads to more actual CCIP transactions, additional protocol integrations and sustainable fee activity.
The real competition in blockchain is not just about building faster networks. It is also about connecting them securely. And this is where Chainlink is trying to build its position.
$LINK
323
Verified
I've been looking more closely at Stellar lately, and one thing caught my attention: the network is slowly building something bigger than a simple crypto payment system.
Look at what has been happening.
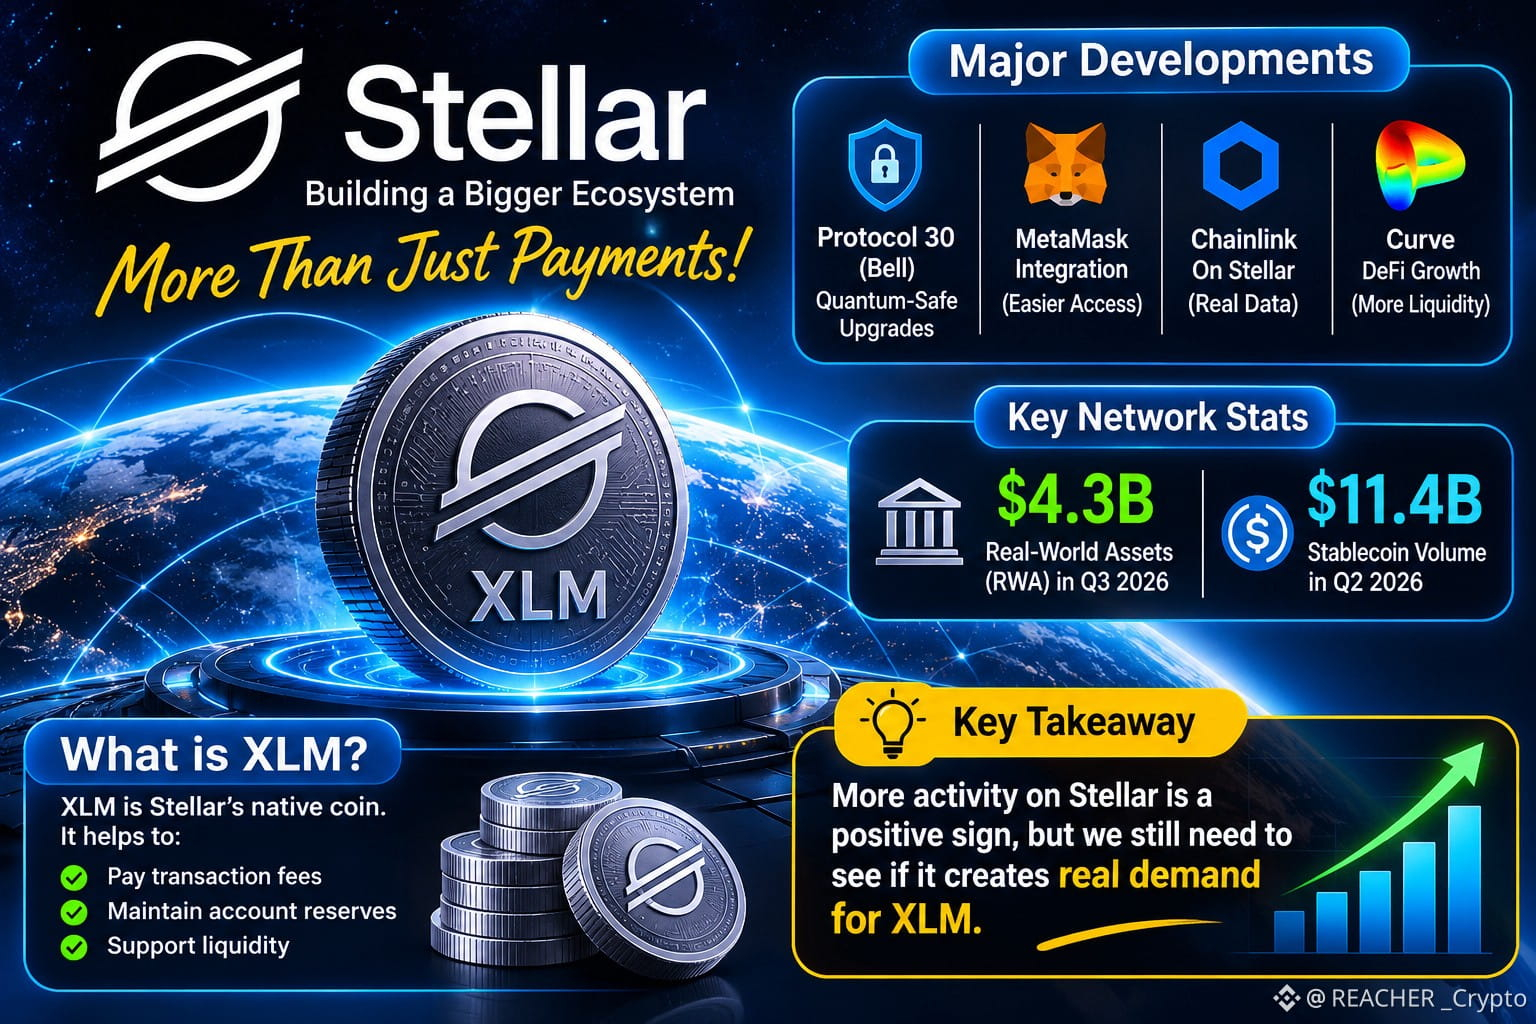
Stellar reported more than $4.3 billion in real-world assets (RWA) on its network in Q3 2026. Its Q2 report also showed around $11.4 billion in stablecoin transfer volume. These numbers matter because they show that blockchain activity is not limited to people buying and selling cryptocurrencies. Financial assets and payment infrastructure are also moving on-chain.
There are several developments behind this growth.
Chainlink's integration brings external price data to Stellar's smart contracts. This can help developers build lending, borrowing and collateral-based applications.
MetaMask's Stellar integration makes the network easier to access for existing crypto users. Meanwhile, Curve's expansion could bring more stablecoin liquidity and DeFi activity to the ecosystem.
Another development worth watching is Protocol 30, also called Bell. Its testnet activation introduces support for ML-DSA post quantum signature verification in Soroban smart contracts, alongside other improvements. The mainnet activation is still subject to the planned November 23 validator vote.
But what does all this mean for XLM?
XLM is Stellar's native coin. It is used to pay network transaction fees, maintain account reserves and support liquidity when moving between different assets.
Here is the part I think traders should understand: more activity on Stellar does not automatically mean a higher XLM price.
For example, if institutions issue more tokenized assets or users transfer more stablecoins, that is positive for network utility. But we still need to see whether this activity creates meaningful demand for XLM itself.
Personally, I am watching three things: real RWA growth, stablecoin activity and whether XLM demand increases alongside network adoption.
$XLM
#Binance98PercentReplenished #BinanceReopensWithdrawalsForMoreAssets
{future}(XLMUSDT)
I've been looking more closely at Stellar lately, and one thing caught my attention: the network is slowly building something bigger than a simple crypto payment system.
Look at what has been happening.
Stellar reported more than $4.3 billion in real-world assets (RWA) on its network in Q3 2026. Its Q2 report also showed around $11.4 billion in stablecoin transfer volume. These numbers matter because they show that blockchain activity is not limited to people buying and selling cryptocurrencies. Financial assets and payment infrastructure are also moving on-chain.
There are several developments behind this growth.
Chainlink's integration brings external price data to Stellar's smart contracts. This can help developers build lending, borrowing and collateral-based applications.
MetaMask's Stellar integration makes the network easier to access for existing crypto users. Meanwhile, Curve's expansion could bring more stablecoin liquidity and DeFi activity to the ecosystem.
Another development worth watching is Protocol 30, also called Bell. Its testnet activation introduces support for ML-DSA post quantum signature verification in Soroban smart contracts, alongside other improvements. The mainnet activation is still subject to the planned November 23 validator vote.
But what does all this mean for XLM?
XLM is Stellar's native coin. It is used to pay network transaction fees, maintain account reserves and support liquidity when moving between different assets.
Here is the part I think traders should understand: more activity on Stellar does not automatically mean a higher XLM price.
For example, if institutions issue more tokenized assets or users transfer more stablecoins, that is positive for network utility. But we still need to see whether this activity creates meaningful demand for XLM itself.
Personally, I am watching three things: real RWA growth, stablecoin activity and whether XLM demand increases alongside network adoption.
$XLM
#Binance98PercentReplenished #BinanceReopensWithdrawalsForMoreAssets
Look at what has been happening.
Stellar reported more than $4.3 billion in real-world assets (RWA) on its network in Q3 2026. Its Q2 report also showed around $11.4 billion in stablecoin transfer volume. These numbers matter because they show that blockchain activity is not limited to people buying and selling cryptocurrencies. Financial assets and payment infrastructure are also moving on-chain.
There are several developments behind this growth.
Chainlink's integration brings external price data to Stellar's smart contracts. This can help developers build lending, borrowing and collateral-based applications.
MetaMask's Stellar integration makes the network easier to access for existing crypto users. Meanwhile, Curve's expansion could bring more stablecoin liquidity and DeFi activity to the ecosystem.
Another development worth watching is Protocol 30, also called Bell. Its testnet activation introduces support for ML-DSA post quantum signature verification in Soroban smart contracts, alongside other improvements. The mainnet activation is still subject to the planned November 23 validator vote.
But what does all this mean for XLM?
XLM is Stellar's native coin. It is used to pay network transaction fees, maintain account reserves and support liquidity when moving between different assets.
Here is the part I think traders should understand: more activity on Stellar does not automatically mean a higher XLM price.
For example, if institutions issue more tokenized assets or users transfer more stablecoins, that is positive for network utility. But we still need to see whether this activity creates meaningful demand for XLM itself.
Personally, I am watching three things: real RWA growth, stablecoin activity and whether XLM demand increases alongside network adoption.
$XLM
#Binance98PercentReplenished #BinanceReopensWithdrawalsForMoreAssets
2
1.1k
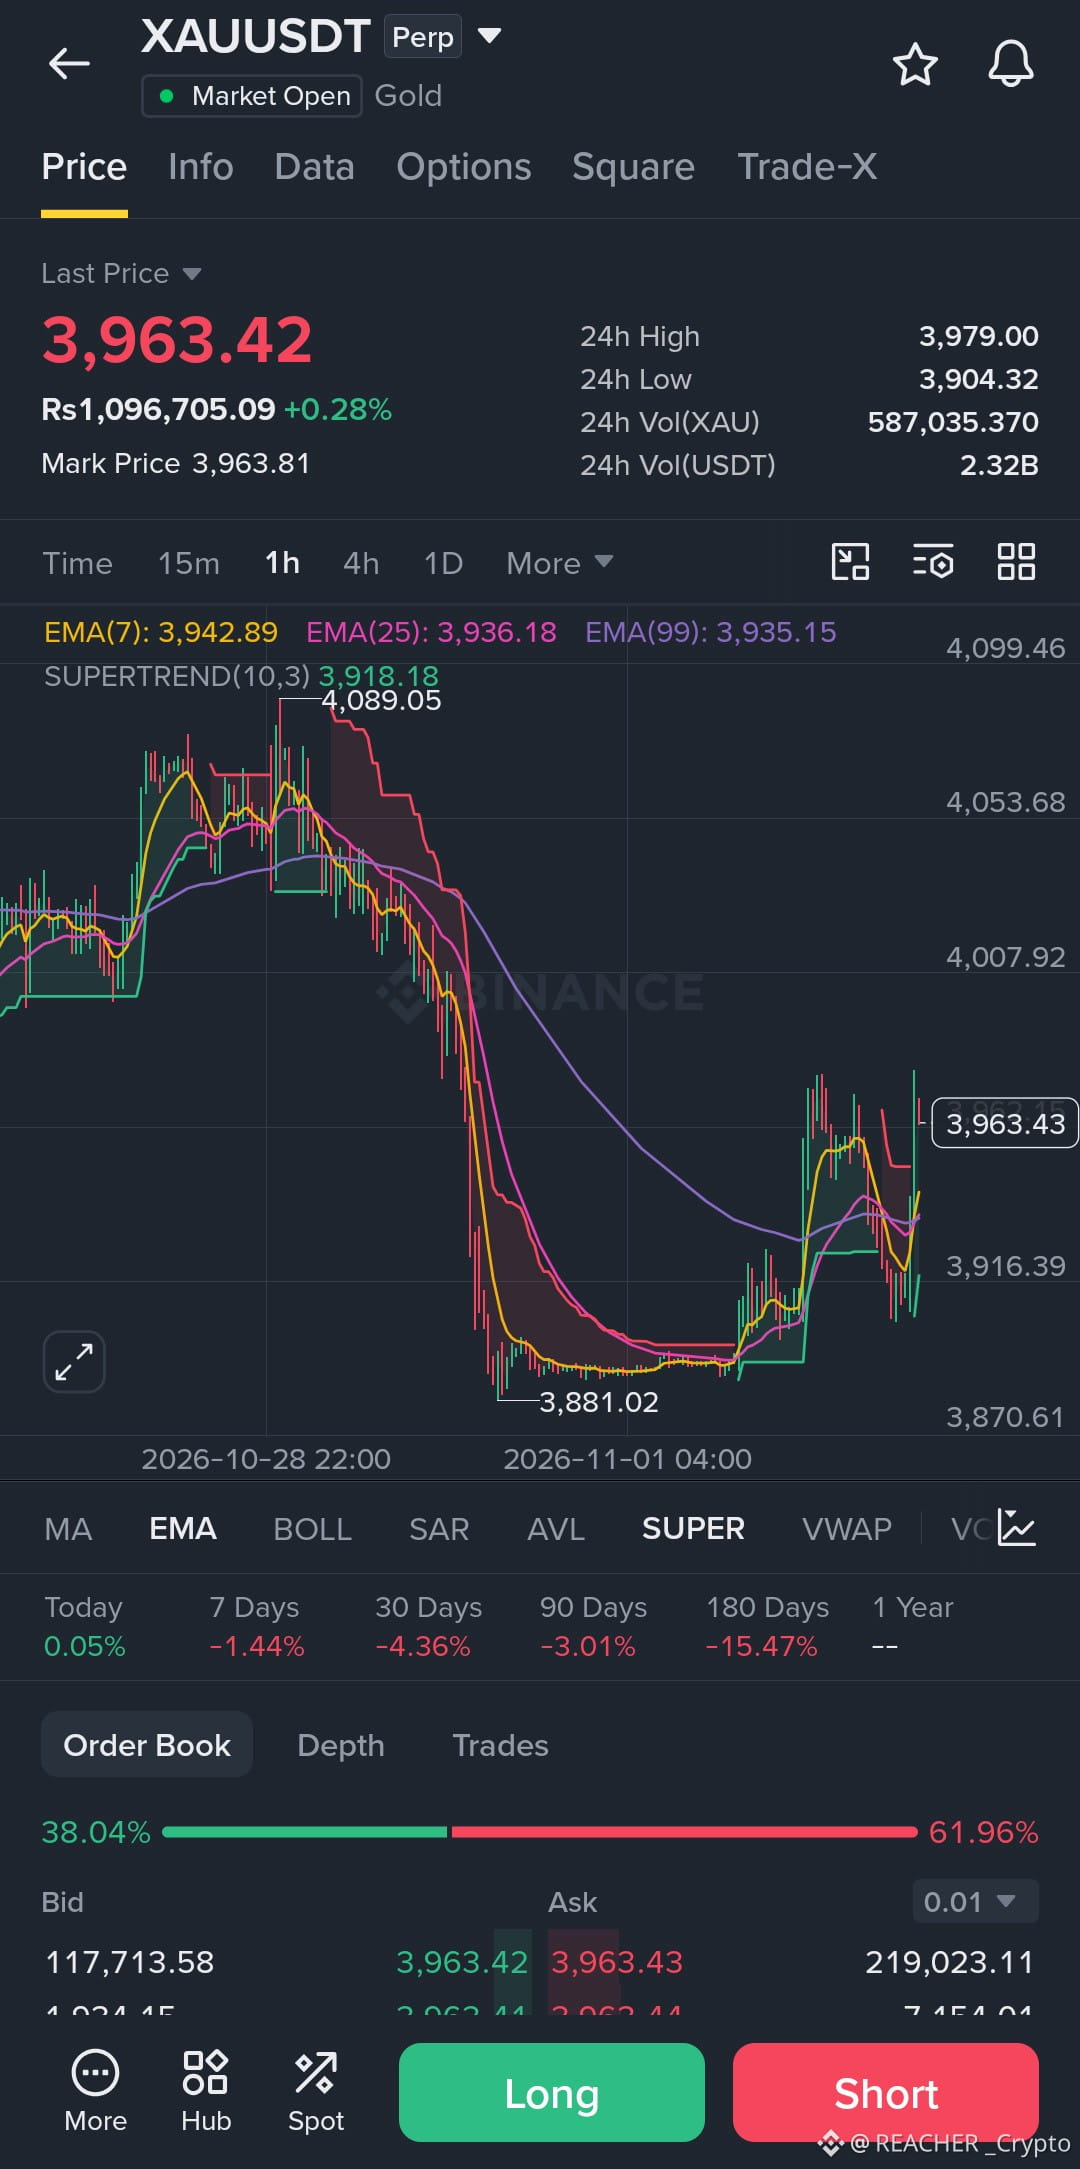
I almost ignored this XAU chart until I noticed how the price was interacting with the EMAs and the Supertrend indicator on the right side.
Looking at the 1-hour timeframe, the macro trend was heavily bearish, dropping from the 4,089 peak down to the 3,881 low. But zoom in on the recent price action. We’ve seen a sharp bounce, and price is currently sitting at 3,963.42.
Here is the critical detail: the price has reclaimed the EMA cluster. The EMA7 (3,942), EMA25 (3,936), and EMA99 (3,935) are all acting as dynamic support beneath us. More importantly, the Supertrend indicator has flipped to green, with the support line now sitting at 3,918.
However, look at the order book. It’s showing 61.96% sell pressure against only 38.04% buy pressure. This tells me that while the momentum has shifted locally, there is heavy overhead resistance.
A lesson I've learned from trading these bounces is that you don't buy the first green candle; you wait for the market to prove it can hold the moving averages.
Trade Plan:
Bias: Short-term bullish (Playing the oversold bounce).
Entry Zone: 3,940.00 – 3,950.00 (Looking for a slight pullback to retest the EMA cluster and Supertrend).
Stop Loss: 3,880.00 (Just below the recent capitulation wick).
Target 1: 3,979.00 (24h high and immediate resistance).
Target 2: 4,007.92 (Mid-range macro resistance).
Target 3: 4,053.68 (Previous breakdown level).
Risk/Reward: 1:2.5
Invalidation: A 1H candle close back below 3,910.00, signaling the bears are still in control.
Don't FOMO into a falling candle. Wait for the hourly candle to close strong, respect your stop loss, and never risk more than you can afford to lose.
Do you think XAU has finally found a bottom here, or is this just a lower high before the next dump?
$XAU
{future}(XAUUSDT)
#AppleReportsMixedResults #USMidtermElections #Nasdaq100EntersCorrection #USOctoberNFP-AreRateCutsStillPossible
I almost ignored this XAU chart until I noticed how the price was interacting with the EMAs and the Supertrend indicator on the right side.
Looking at the 1-hour timeframe, the macro trend was heavily bearish, dropping from the 4,089 peak down to the 3,881 low. But zoom in on the recent price action. We’ve seen a sharp bounce, and price is currently sitting at 3,963.42.
Here is the critical detail: the price has reclaimed the EMA cluster. The EMA7 (3,942), EMA25 (3,936), and EMA99 (3,935) are all acting as dynamic support beneath us. More importantly, the Supertrend indicator has flipped to green, with the support line now sitting at 3,918.
However, look at the order book. It’s showing 61.96% sell pressure against only 38.04% buy pressure. This tells me that while the momentum has shifted locally, there is heavy overhead resistance.
A lesson I've learned from trading these bounces is that you don't buy the first green candle; you wait for the market to prove it can hold the moving averages.
Trade Plan:
Bias: Short-term bullish (Playing the oversold bounce).
Entry Zone: 3,940.00 – 3,950.00 (Looking for a slight pullback to retest the EMA cluster and Supertrend).
Stop Loss: 3,880.00 (Just below the recent capitulation wick).
Target 1: 3,979.00 (24h high and immediate resistance).
Target 2: 4,007.92 (Mid-range macro resistance).
Target 3: 4,053.68 (Previous breakdown level).
Risk/Reward: 1:2.5
Invalidation: A 1H candle close back below 3,910.00, signaling the bears are still in control.
Don't FOMO into a falling candle. Wait for the hourly candle to close strong, respect your stop loss, and never risk more than you can afford to lose.
Do you think XAU has finally found a bottom here, or is this just a lower high before the next dump?
$XAU
#AppleReportsMixedResults #USMidtermElections #Nasdaq100EntersCorrection #USOctoberNFP-AreRateCutsStillPossible
Looking at the 1-hour timeframe, the macro trend was heavily bearish, dropping from the 4,089 peak down to the 3,881 low. But zoom in on the recent price action. We’ve seen a sharp bounce, and price is currently sitting at 3,963.42.
Here is the critical detail: the price has reclaimed the EMA cluster. The EMA7 (3,942), EMA25 (3,936), and EMA99 (3,935) are all acting as dynamic support beneath us. More importantly, the Supertrend indicator has flipped to green, with the support line now sitting at 3,918.
However, look at the order book. It’s showing 61.96% sell pressure against only 38.04% buy pressure. This tells me that while the momentum has shifted locally, there is heavy overhead resistance.
A lesson I've learned from trading these bounces is that you don't buy the first green candle; you wait for the market to prove it can hold the moving averages.
Trade Plan:
Bias: Short-term bullish (Playing the oversold bounce).
Entry Zone: 3,940.00 – 3,950.00 (Looking for a slight pullback to retest the EMA cluster and Supertrend).
Stop Loss: 3,880.00 (Just below the recent capitulation wick).
Target 1: 3,979.00 (24h high and immediate resistance).
Target 2: 4,007.92 (Mid-range macro resistance).
Target 3: 4,053.68 (Previous breakdown level).
Risk/Reward: 1:2.5
Invalidation: A 1H candle close back below 3,910.00, signaling the bears are still in control.
Don't FOMO into a falling candle. Wait for the hourly candle to close strong, respect your stop loss, and never risk more than you can afford to lose.
Do you think XAU has finally found a bottom here, or is this just a lower high before the next dump?
$XAU
#AppleReportsMixedResults #USMidtermElections #Nasdaq100EntersCorrection #USOctoberNFP-AreRateCutsStillPossible
253
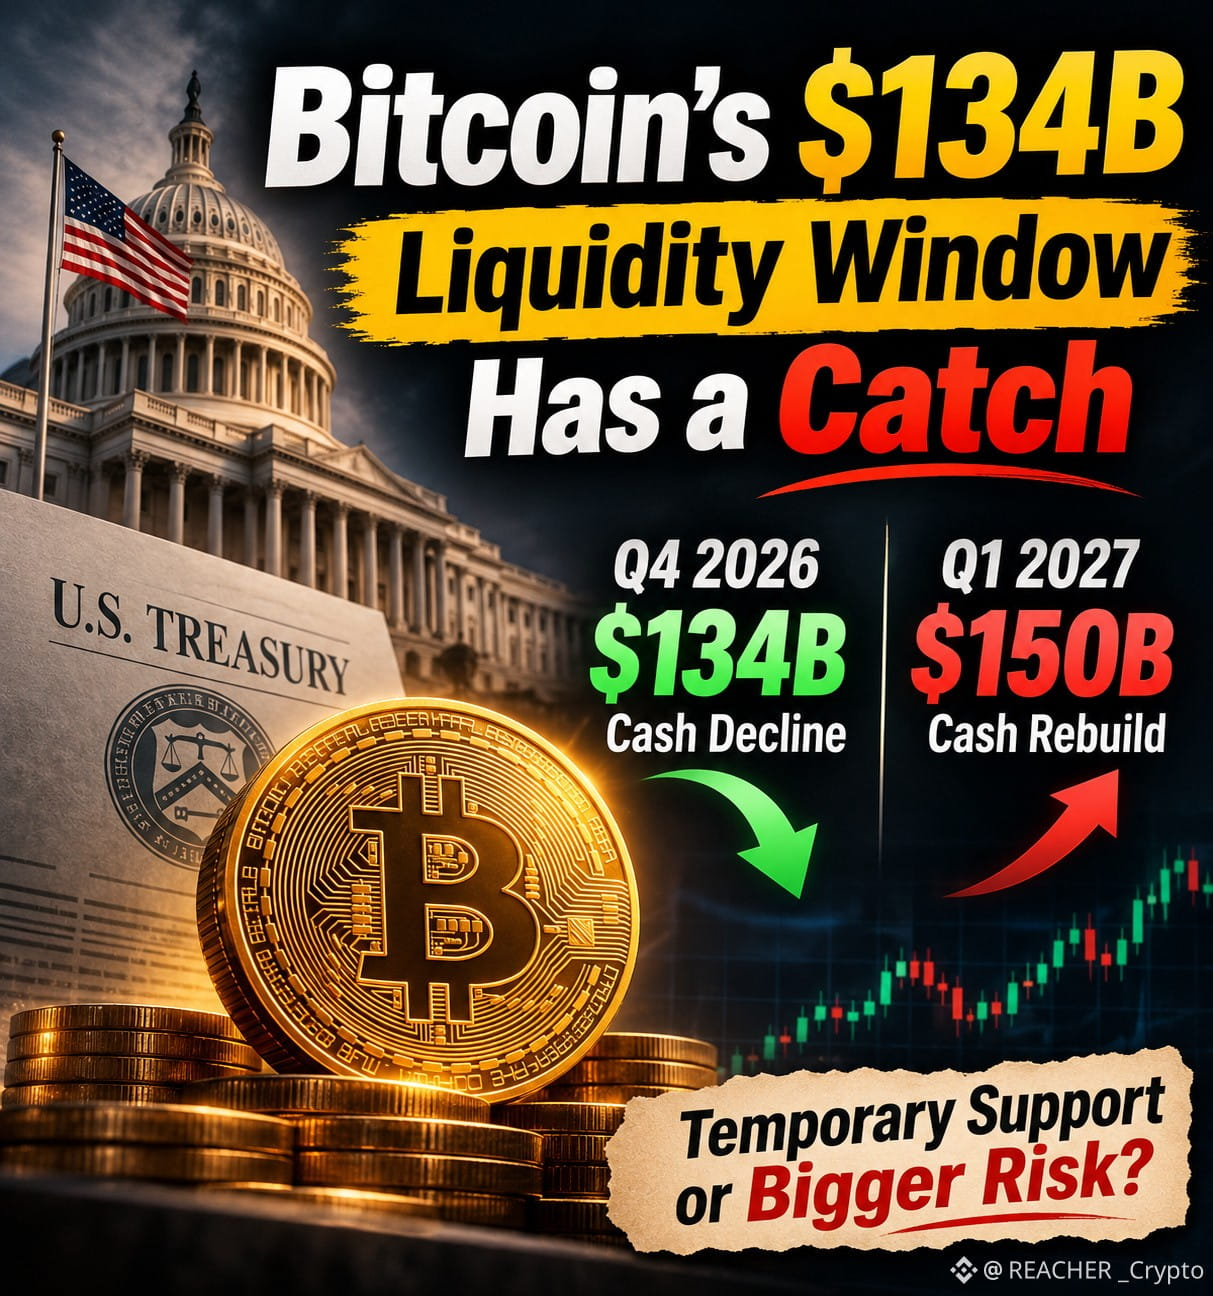
I think the latest US Treasury borrowing update deserves more attention from Bitcoin traders. At first glance, the numbers look positive, but there is another side to this story that the market should not ignore.
The Treasury reduced its Q4 borrowing estimate by $10 billion, from $628B to $618B. However, its cash-adjusted financing needs actually increased by $24B. The difference comes from a higher starting cash balance, not necessarily lower government financing needs.
Here is where things get interesting.
The Treasury expects its cash balance to fall from $984B in September to $850B by December. That represents a projected $134B decline. When the government spends money from its Treasury General Account (TGA), funds generally move into the banking system, potentially supporting liquidity.
But the outlook changes in Q1 2027.
Treasury expects to rebuild its cash balance to $1 trillion by March. That means a $150B increase, larger than the previous quarter's projected drawdown.
For Bitcoin, this creates two different liquidity environments. Q4 could provide some support for risk assets, while Q1 could bring additional liquidity pressure as Treasury rebuilds its cash reserves.
However, I would not treat this as an automatic $150B withdrawal from crypto markets. Federal Reserve operations, bank reserves, Treasury issuance, repo conditions and institutional demand will determine the actual impact.
Personally, I am watching the TGA balance, Fed reserves, US yields and Bitcoin ETF flows together.
The real question is not whether Treasury is borrowing less. It is whether the liquidity entering the financial system today can remain supportive when Treasury starts rebuilding its cash balance tomorrow.
That is the part I believe Bitcoin traders should prepare to monitor.
$BTC
#BinanceReopensWithdrawalsForMoreAssets #BinanceHourlyDepositsExceedWithdrawals #Nasdaq100EntersCorrection #USOctoberNFP-AreRateCutsStillPossible #USMidtermElections
{future}(BTCUSDT)
I think the latest US Treasury borrowing update deserves more attention from Bitcoin traders. At first glance, the numbers look positive, but there is another side to this story that the market should not ignore.
The Treasury reduced its Q4 borrowing estimate by $10 billion, from $628B to $618B. However, its cash-adjusted financing needs actually increased by $24B. The difference comes from a higher starting cash balance, not necessarily lower government financing needs.
Here is where things get interesting.
The Treasury expects its cash balance to fall from $984B in September to $850B by December. That represents a projected $134B decline. When the government spends money from its Treasury General Account (TGA), funds generally move into the banking system, potentially supporting liquidity.
But the outlook changes in Q1 2027.
Treasury expects to rebuild its cash balance to $1 trillion by March. That means a $150B increase, larger than the previous quarter's projected drawdown.
For Bitcoin, this creates two different liquidity environments. Q4 could provide some support for risk assets, while Q1 could bring additional liquidity pressure as Treasury rebuilds its cash reserves.
However, I would not treat this as an automatic $150B withdrawal from crypto markets. Federal Reserve operations, bank reserves, Treasury issuance, repo conditions and institutional demand will determine the actual impact.
Personally, I am watching the TGA balance, Fed reserves, US yields and Bitcoin ETF flows together.
The real question is not whether Treasury is borrowing less. It is whether the liquidity entering the financial system today can remain supportive when Treasury starts rebuilding its cash balance tomorrow.
That is the part I believe Bitcoin traders should prepare to monitor.
$BTC
#BinanceReopensWithdrawalsForMoreAssets #BinanceHourlyDepositsExceedWithdrawals #Nasdaq100EntersCorrection #USOctoberNFP-AreRateCutsStillPossible #USMidtermElections
The Treasury reduced its Q4 borrowing estimate by $10 billion, from $628B to $618B. However, its cash-adjusted financing needs actually increased by $24B. The difference comes from a higher starting cash balance, not necessarily lower government financing needs.
Here is where things get interesting.
The Treasury expects its cash balance to fall from $984B in September to $850B by December. That represents a projected $134B decline. When the government spends money from its Treasury General Account (TGA), funds generally move into the banking system, potentially supporting liquidity.
But the outlook changes in Q1 2027.
Treasury expects to rebuild its cash balance to $1 trillion by March. That means a $150B increase, larger than the previous quarter's projected drawdown.
For Bitcoin, this creates two different liquidity environments. Q4 could provide some support for risk assets, while Q1 could bring additional liquidity pressure as Treasury rebuilds its cash reserves.
However, I would not treat this as an automatic $150B withdrawal from crypto markets. Federal Reserve operations, bank reserves, Treasury issuance, repo conditions and institutional demand will determine the actual impact.
Personally, I am watching the TGA balance, Fed reserves, US yields and Bitcoin ETF flows together.
The real question is not whether Treasury is borrowing less. It is whether the liquidity entering the financial system today can remain supportive when Treasury starts rebuilding its cash balance tomorrow.
That is the part I believe Bitcoin traders should prepare to monitor.
$BTC
#BinanceReopensWithdrawalsForMoreAssets #BinanceHourlyDepositsExceedWithdrawals #Nasdaq100EntersCorrection #USOctoberNFP-AreRateCutsStillPossible #USMidtermElections
158
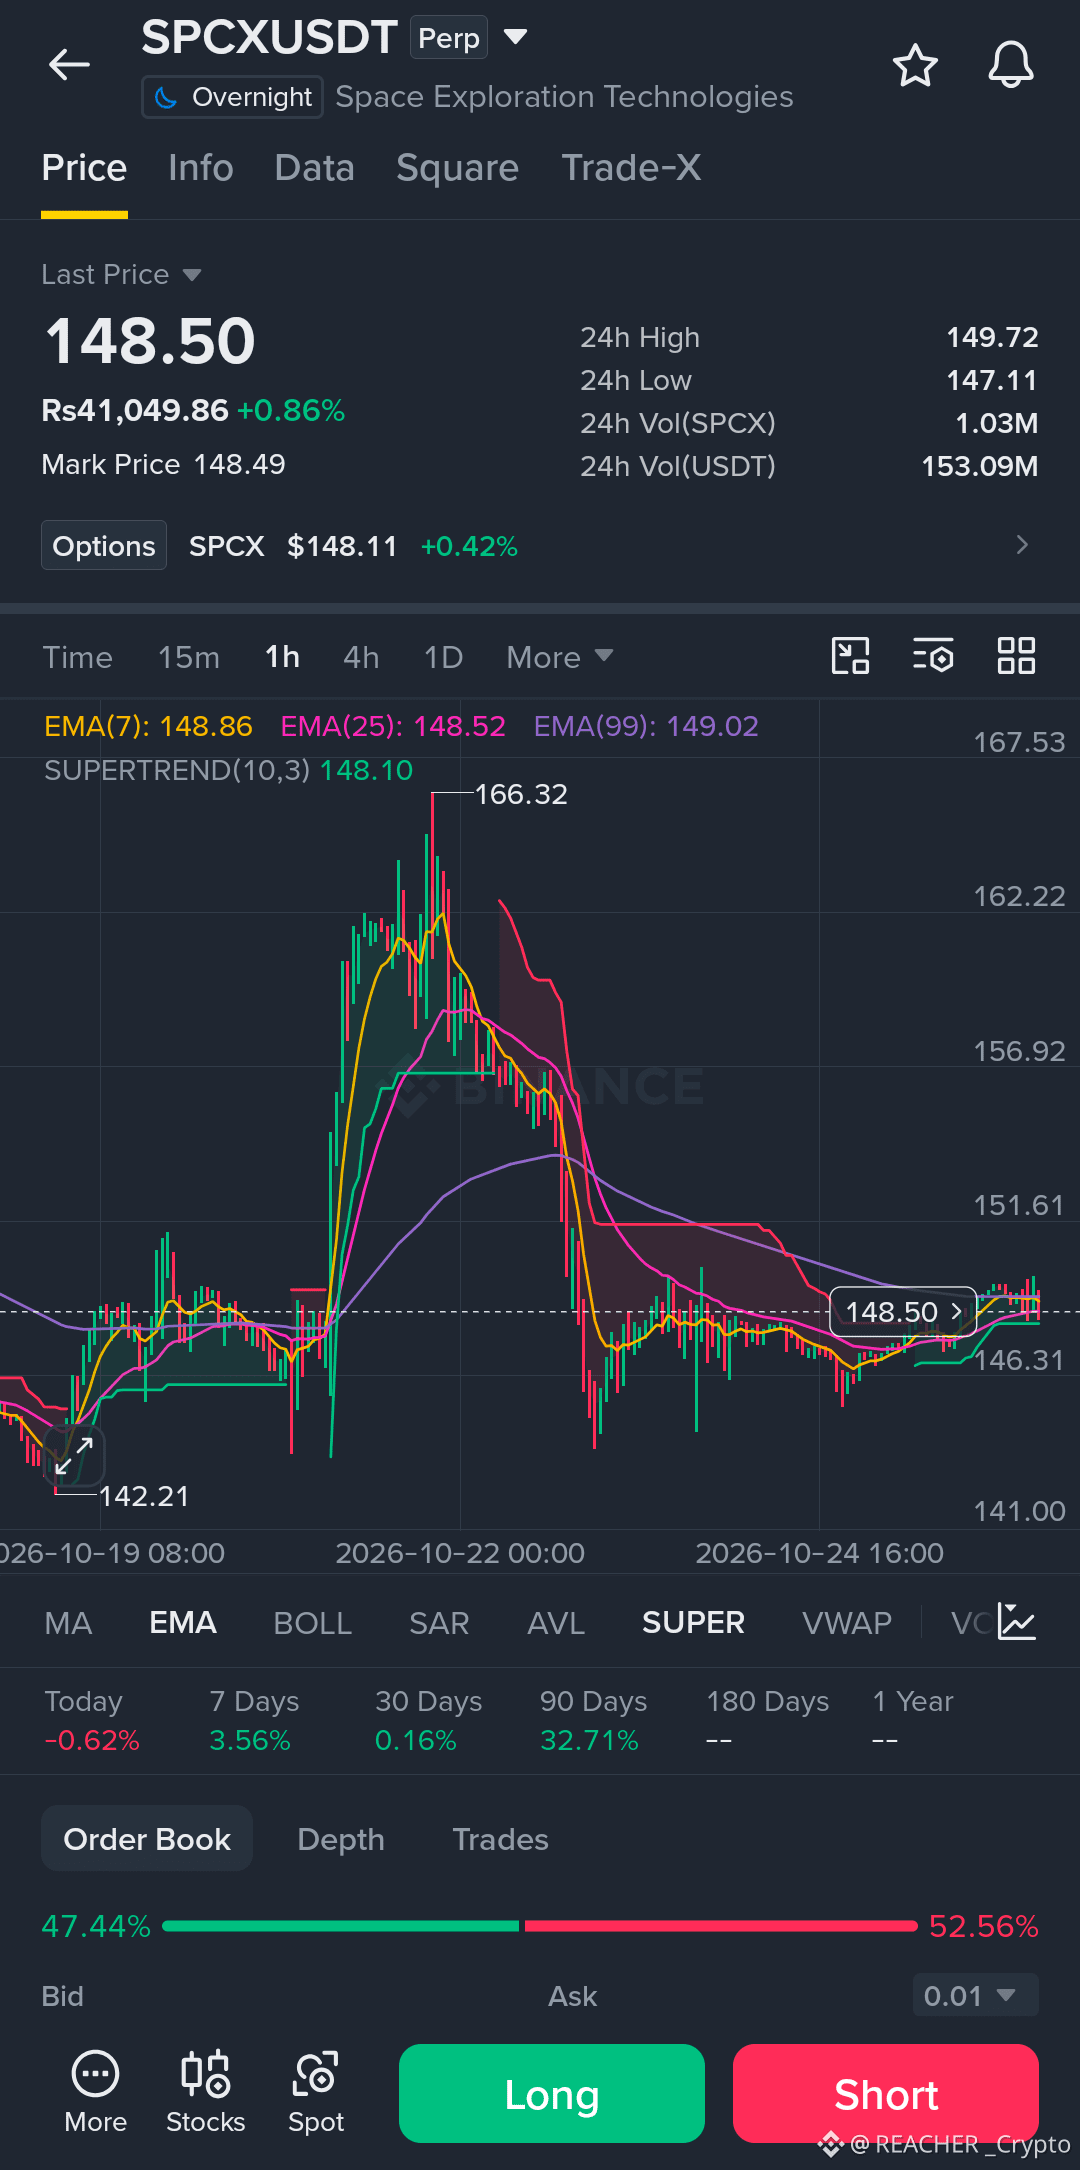
I wasn’t planning to look at tokenized stocks today, but this 1-hour $SPCX USDT chart caught my eye. After that massive run-up to 166.32, the subsequent drop was brutal, but the price action right now is telling an interesting story of stabilization.
Look at the bottom left. We saw a sharp flush down to 142.21, but since then, we’ve been chopping sideways, printing slightly higher lows. We are currently sitting at 148.50, which puts us right in the middle of a clear congestion zone.
The interesting part is the moving average squeeze. The 7 EMA (148.86), 25 EMA (148.52), and 99 EMA (149.02) are all tangled together right at current price. When MAs compress like this, it usually signals an impending volatility expansion—the market is coiling.
A lesson I've learned is that trading inside a tight range is a great way to get chopped up. I prefer to wait for the breakout. Right now, the SuperTrend has flipped green, giving a slight edge to the bulls, but the overhead 99 EMA is still a barrier.
My bias is neutral-to-bullish, but I want confirmation. I’m watching for a decisive hourly close above the 149.00–149.70 resistance block.
Trade Plan:
· Entry: 149.70 (On a confirmed breakout)
· Stop Loss: 147.10 (Below the recent range lows)
· Target 1: 153.50
· Target 2: 158.00
· RR: Roughly 1:2
· Invalidation: A rejection at 149.00 that pushes price back below the SuperTrend (148.10).
The order book is fairly balanced (47% buy, 52% sell), meaning it could go either way. Don't force a trade in the middle of the range. Protect your capital and never risk more than you can afford to lose.
Are you waiting for the breakout above 150, or do you think this compression breaks to the downside?
$SPCX
{future}(SPCXUSDT)
#EarningsSeason #BinancePick #SouthKoreaDelaysCryptoIncomeTax #SouthKoreaPlansToRegulateStablecoinsUnderFXLaw
I wasn’t planning to look at tokenized stocks today, but this 1-hour $SPCX USDT chart caught my eye. After that massive run-up to 166.32, the subsequent drop was brutal, but the price action right now is telling an interesting story of stabilization.
Look at the bottom left. We saw a sharp flush down to 142.21, but since then, we’ve been chopping sideways, printing slightly higher lows. We are currently sitting at 148.50, which puts us right in the middle of a clear congestion zone.
The interesting part is the moving average squeeze. The 7 EMA (148.86), 25 EMA (148.52), and 99 EMA (149.02) are all tangled together right at current price. When MAs compress like this, it usually signals an impending volatility expansion—the market is coiling.
A lesson I've learned is that trading inside a tight range is a great way to get chopped up. I prefer to wait for the breakout. Right now, the SuperTrend has flipped green, giving a slight edge to the bulls, but the overhead 99 EMA is still a barrier.
My bias is neutral-to-bullish, but I want confirmation. I’m watching for a decisive hourly close above the 149.00–149.70 resistance block.
Trade Plan:
· Entry: 149.70 (On a confirmed breakout)
· Stop Loss: 147.10 (Below the recent range lows)
· Target 1: 153.50
· Target 2: 158.00
· RR: Roughly 1:2
· Invalidation: A rejection at 149.00 that pushes price back below the SuperTrend (148.10).
The order book is fairly balanced (47% buy, 52% sell), meaning it could go either way. Don't force a trade in the middle of the range. Protect your capital and never risk more than you can afford to lose.
Are you waiting for the breakout above 150, or do you think this compression breaks to the downside?
$SPCX
#EarningsSeason #BinancePick #SouthKoreaDelaysCryptoIncomeTax #SouthKoreaPlansToRegulateStablecoinsUnderFXLaw
Look at the bottom left. We saw a sharp flush down to 142.21, but since then, we’ve been chopping sideways, printing slightly higher lows. We are currently sitting at 148.50, which puts us right in the middle of a clear congestion zone.
The interesting part is the moving average squeeze. The 7 EMA (148.86), 25 EMA (148.52), and 99 EMA (149.02) are all tangled together right at current price. When MAs compress like this, it usually signals an impending volatility expansion—the market is coiling.
A lesson I've learned is that trading inside a tight range is a great way to get chopped up. I prefer to wait for the breakout. Right now, the SuperTrend has flipped green, giving a slight edge to the bulls, but the overhead 99 EMA is still a barrier.
My bias is neutral-to-bullish, but I want confirmation. I’m watching for a decisive hourly close above the 149.00–149.70 resistance block.
Trade Plan:
· Entry: 149.70 (On a confirmed breakout)
· Stop Loss: 147.10 (Below the recent range lows)
· Target 1: 153.50
· Target 2: 158.00
· RR: Roughly 1:2
· Invalidation: A rejection at 149.00 that pushes price back below the SuperTrend (148.10).
The order book is fairly balanced (47% buy, 52% sell), meaning it could go either way. Don't force a trade in the middle of the range. Protect your capital and never risk more than you can afford to lose.
Are you waiting for the breakout above 150, or do you think this compression breaks to the downside?
$SPCX
#EarningsSeason #BinancePick #SouthKoreaDelaysCryptoIncomeTax #SouthKoreaPlansToRegulateStablecoinsUnderFXLaw
257
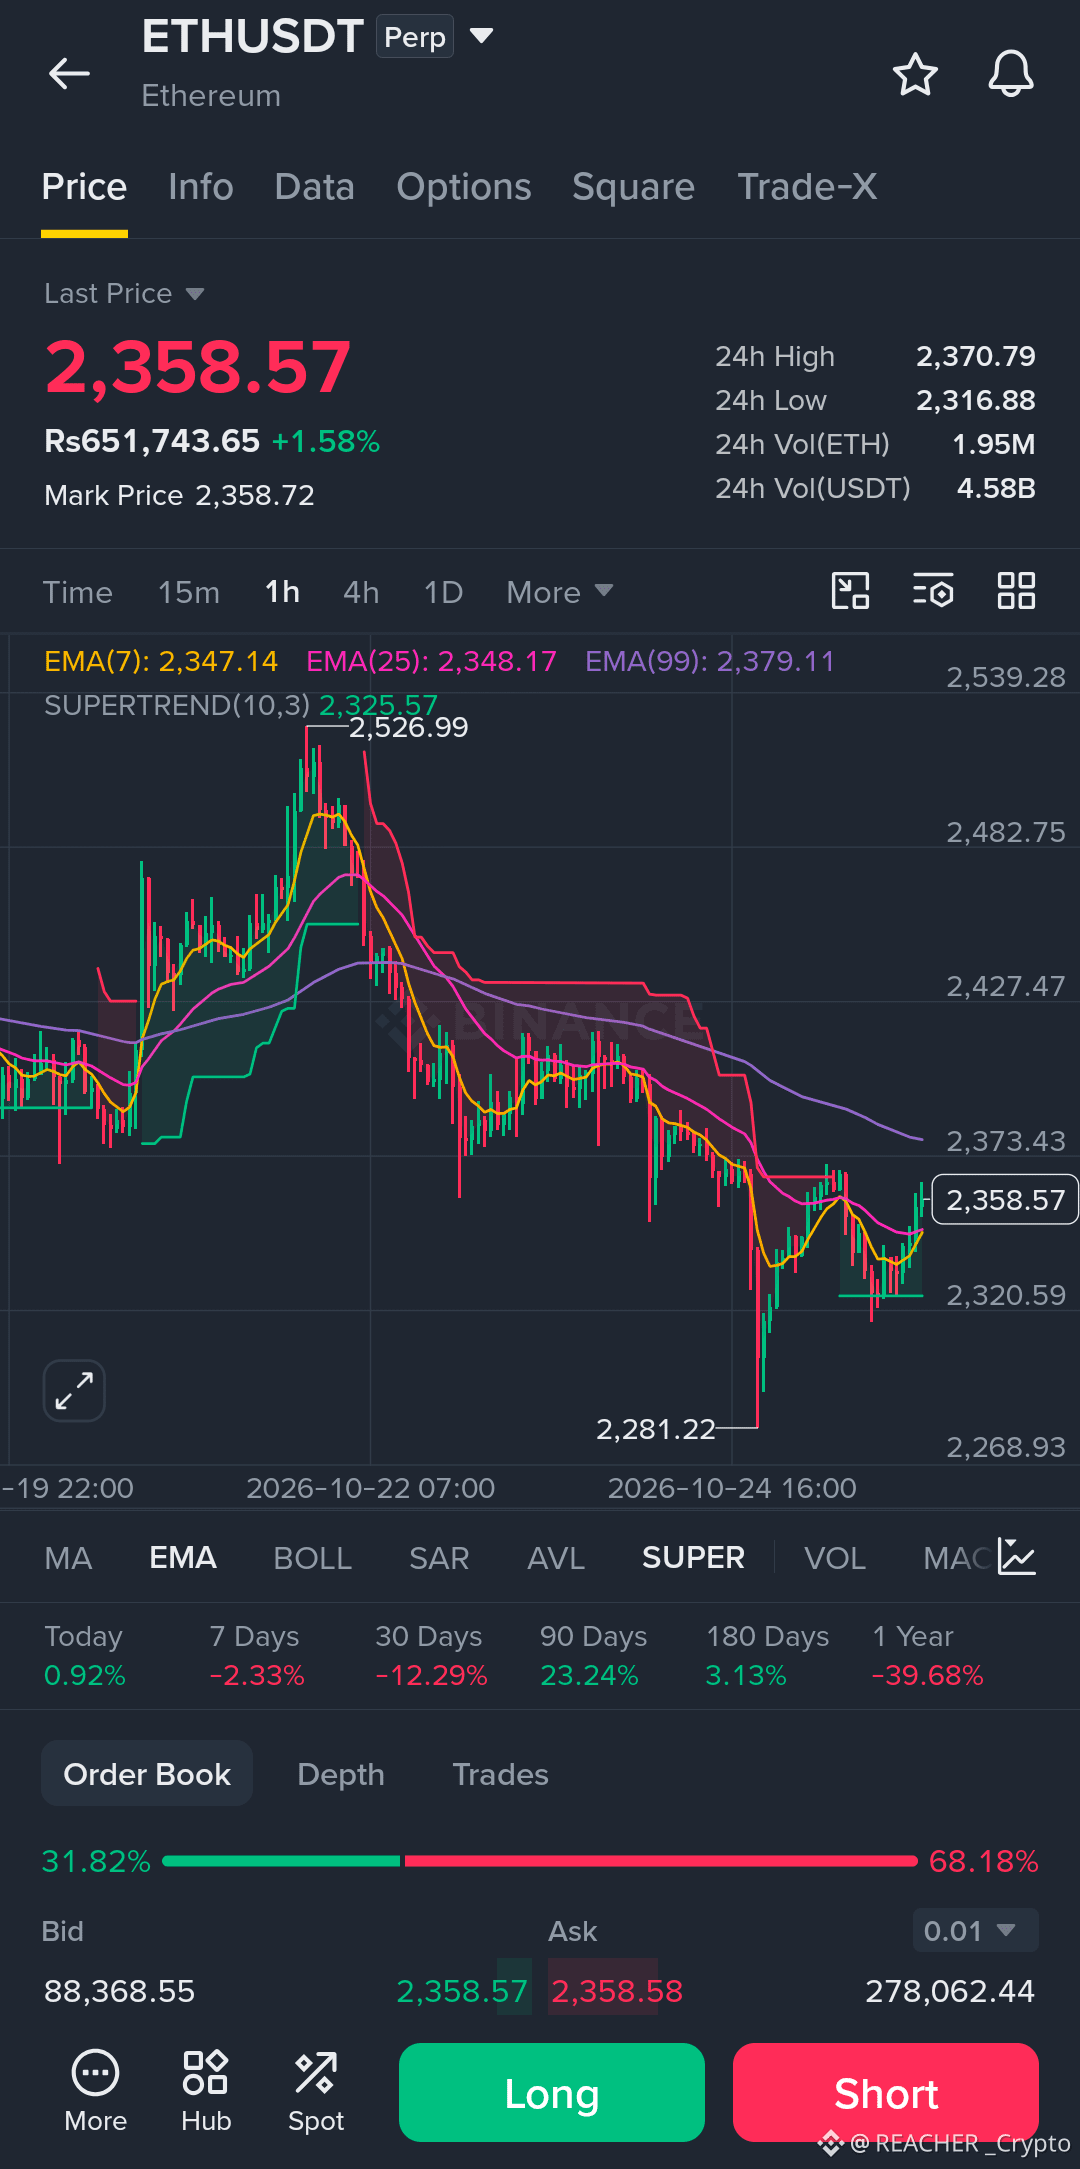
I’ve been watching this ETH setup for a while, and today’s price action finally gave me a reason to take it seriously. It’s a classic relief bounce, but the bigger picture still looks heavy.
Looking at the 1-hour chart, we saw a sharp drop down to 2,281. Since then, price has clawed its way back to 2,358. The immediate momentum is clearly shifting—notice how the 7 EMA (2,347) has crossed back above the 25 EMA (2,348), and the SuperTrend has flipped to green at 2,325. Short-term buyers are stepping in.
But here is where I stay cautious. The 99 EMA at 2,379 is looming right overhead. In a broader downtrend, this longer moving average acts like a magnet and a ceiling. Also, look at the order book—sellers completely dominate the book at 68%. That tells me there’s a heavy wall of supply waiting above.
A lesson I've learned after taking too many early entries is that a counter-trend bounce can easily trap you. I’d rather wait for the market to prove itself.
My plan is to watch the 2,370–2,379 zone closely. If price pushes up there and prints a rejection candle, I’ll look to short the retracement back down. If it breaks and holds above 2,380, I’ll stand aside and reassess.
Trade Plan:
· Entry: 2,370–2,379 (Rejection zone)
· Stop Loss: 2,395 (Just above the 99 EMA)
· Target 1: 2,325 (SuperTrend support)
· Target 2: 2,282 (Recent low)
· RR: Roughly 1:2.5
· Invalidation: A strong hourly close above 2,380.
Never risk more than you can afford to lose, and don’t FOMO into a trade if the setup doesn’t align with your plan.
Would you wait for a rejection at the 99 EMA, or are you buying this bounce early?
$ETH
{future}(ETHUSDT)
#USQ3GDPAndSeptemberPCEDueNextWeek #DowDrops653Points #BinancePick #EarningsSeason
I’ve been watching this ETH setup for a while, and today’s price action finally gave me a reason to take it seriously. It’s a classic relief bounce, but the bigger picture still looks heavy.
Looking at the 1-hour chart, we saw a sharp drop down to 2,281. Since then, price has clawed its way back to 2,358. The immediate momentum is clearly shifting—notice how the 7 EMA (2,347) has crossed back above the 25 EMA (2,348), and the SuperTrend has flipped to green at 2,325. Short-term buyers are stepping in.
But here is where I stay cautious. The 99 EMA at 2,379 is looming right overhead. In a broader downtrend, this longer moving average acts like a magnet and a ceiling. Also, look at the order book—sellers completely dominate the book at 68%. That tells me there’s a heavy wall of supply waiting above.
A lesson I've learned after taking too many early entries is that a counter-trend bounce can easily trap you. I’d rather wait for the market to prove itself.
My plan is to watch the 2,370–2,379 zone closely. If price pushes up there and prints a rejection candle, I’ll look to short the retracement back down. If it breaks and holds above 2,380, I’ll stand aside and reassess.
Trade Plan:
· Entry: 2,370–2,379 (Rejection zone)
· Stop Loss: 2,395 (Just above the 99 EMA)
· Target 1: 2,325 (SuperTrend support)
· Target 2: 2,282 (Recent low)
· RR: Roughly 1:2.5
· Invalidation: A strong hourly close above 2,380.
Never risk more than you can afford to lose, and don’t FOMO into a trade if the setup doesn’t align with your plan.
Would you wait for a rejection at the 99 EMA, or are you buying this bounce early?
$ETH
#USQ3GDPAndSeptemberPCEDueNextWeek #DowDrops653Points #BinancePick #EarningsSeason
Looking at the 1-hour chart, we saw a sharp drop down to 2,281. Since then, price has clawed its way back to 2,358. The immediate momentum is clearly shifting—notice how the 7 EMA (2,347) has crossed back above the 25 EMA (2,348), and the SuperTrend has flipped to green at 2,325. Short-term buyers are stepping in.
But here is where I stay cautious. The 99 EMA at 2,379 is looming right overhead. In a broader downtrend, this longer moving average acts like a magnet and a ceiling. Also, look at the order book—sellers completely dominate the book at 68%. That tells me there’s a heavy wall of supply waiting above.
A lesson I've learned after taking too many early entries is that a counter-trend bounce can easily trap you. I’d rather wait for the market to prove itself.
My plan is to watch the 2,370–2,379 zone closely. If price pushes up there and prints a rejection candle, I’ll look to short the retracement back down. If it breaks and holds above 2,380, I’ll stand aside and reassess.
Trade Plan:
· Entry: 2,370–2,379 (Rejection zone)
· Stop Loss: 2,395 (Just above the 99 EMA)
· Target 1: 2,325 (SuperTrend support)
· Target 2: 2,282 (Recent low)
· RR: Roughly 1:2.5
· Invalidation: A strong hourly close above 2,380.
Never risk more than you can afford to lose, and don’t FOMO into a trade if the setup doesn’t align with your plan.
Would you wait for a rejection at the 99 EMA, or are you buying this bounce early?
$ETH
#USQ3GDPAndSeptemberPCEDueNextWeek #DowDrops653Points #BinancePick #EarningsSeason
667
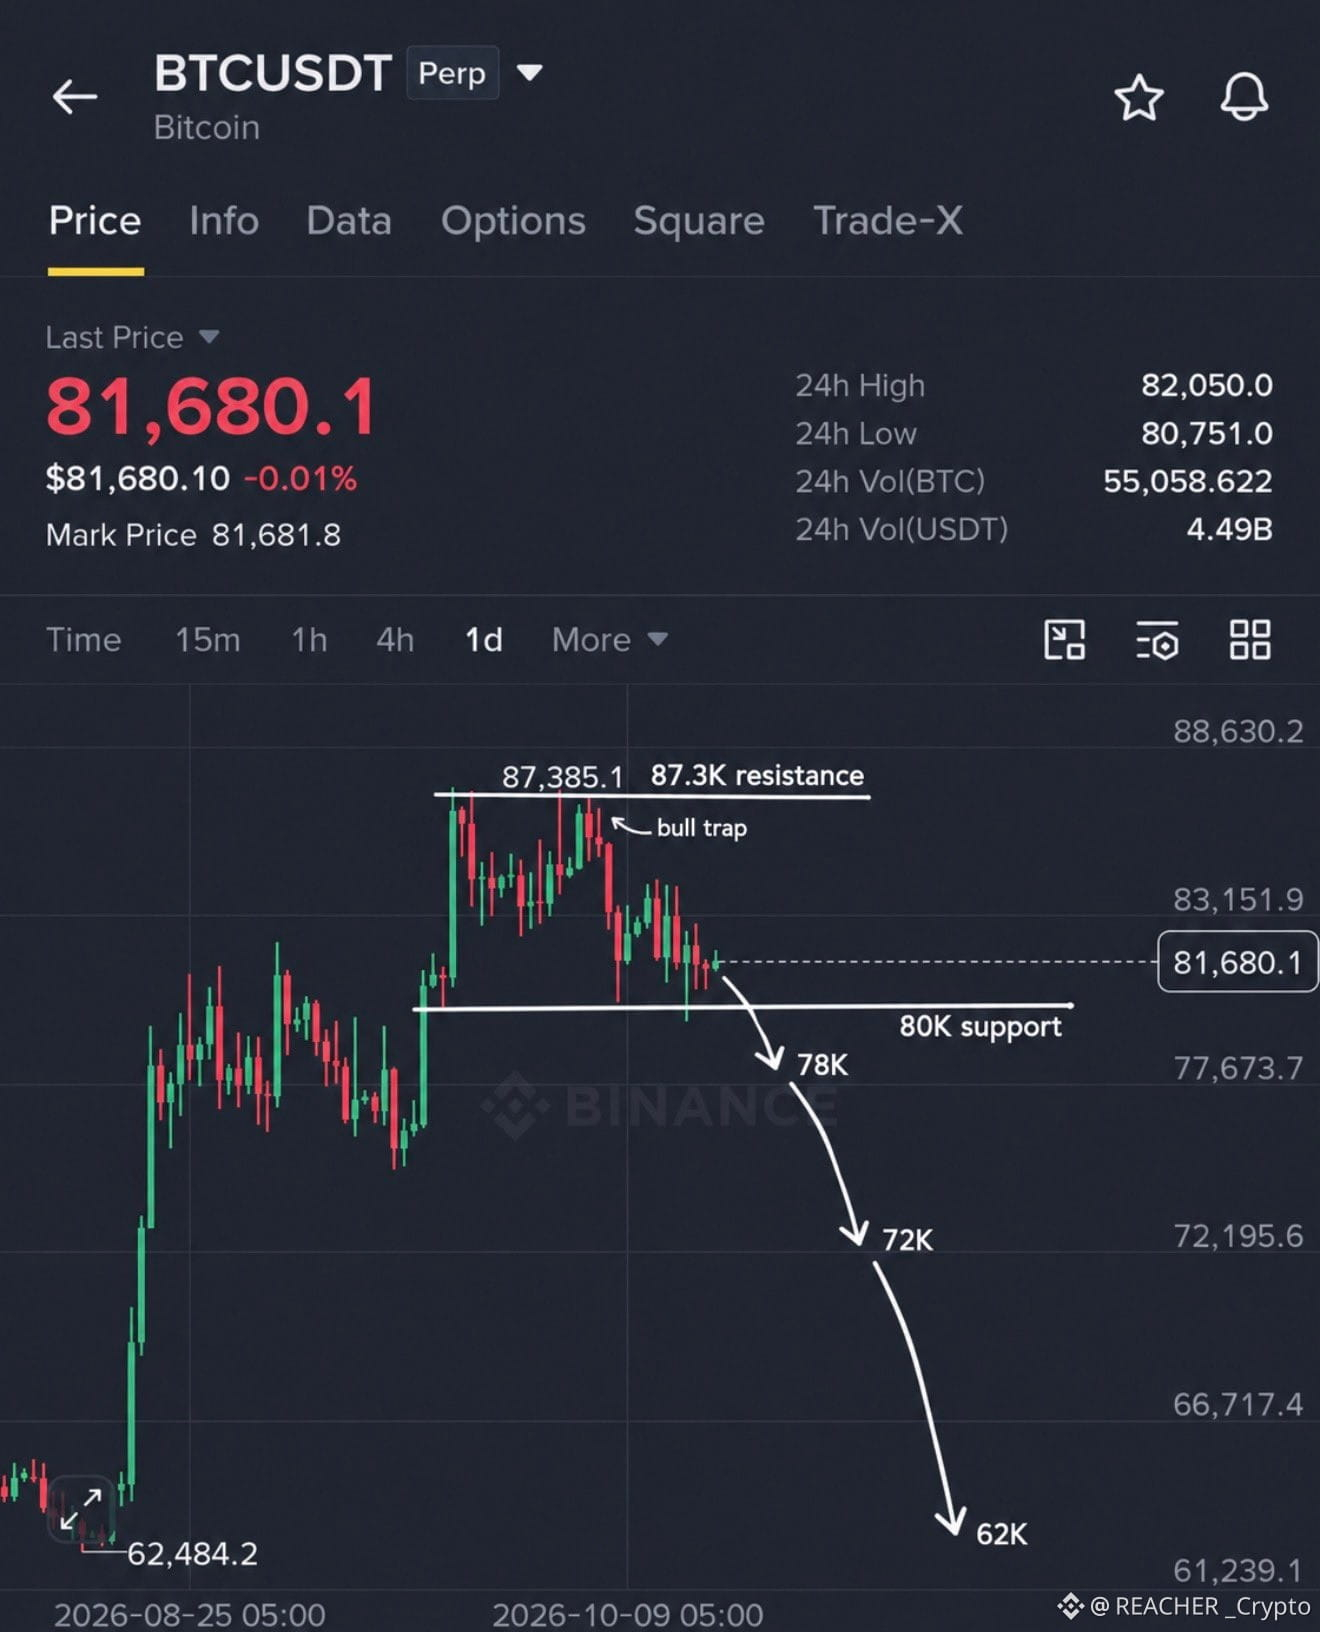
🚨 THE $BTC BULL TRAP IS FINALLY ENDING.
Bitcoin rejected from $87.3K exactly where I warned, and now it is back around $81K.
The bigger dump has started.
$81K → $78K → $72K → $62K → Bottom → $90K+
There will be small pumps on the way, but they will only trap more buyers.
I have been saying this for weeks: don’t trust the fake pumps.
Save this chart and check back later.
Turn on notifications. Follow before you’re late.
I’ll post every major update here first
$BTC
#DeepSeekReleasesUpdatedAIModel #Nasdaq100Falls5.5%InWorstWeekIn18Months #USPPIRises6.3%YearOverYear #StrategySharesFall9%OnFriday
{future}(BTCUSDT)
🚨 THE $BTC BULL TRAP IS FINALLY ENDING.
Bitcoin rejected from $87.3K exactly where I warned, and now it is back around $81K.
The bigger dump has started.
$81K → $78K → $72K → $62K → Bottom → $90K+
There will be small pumps on the way, but they will only trap more buyers.
I have been saying this for weeks: don’t trust the fake pumps.
Save this chart and check back later.
Turn on notifications. Follow before you’re late.
I’ll post every major update here first
$BTC
#DeepSeekReleasesUpdatedAIModel #Nasdaq100Falls5.5%InWorstWeekIn18Months #USPPIRises6.3%YearOverYear #StrategySharesFall9%OnFriday
Bitcoin rejected from $87.3K exactly where I warned, and now it is back around $81K.
The bigger dump has started.
$81K → $78K → $72K → $62K → Bottom → $90K+
There will be small pumps on the way, but they will only trap more buyers.
I have been saying this for weeks: don’t trust the fake pumps.
Save this chart and check back later.
Turn on notifications. Follow before you’re late.
I’ll post every major update here first
$BTC
#DeepSeekReleasesUpdatedAIModel #Nasdaq100Falls5.5%InWorstWeekIn18Months #USPPIRises6.3%YearOverYear #StrategySharesFall9%OnFriday
114
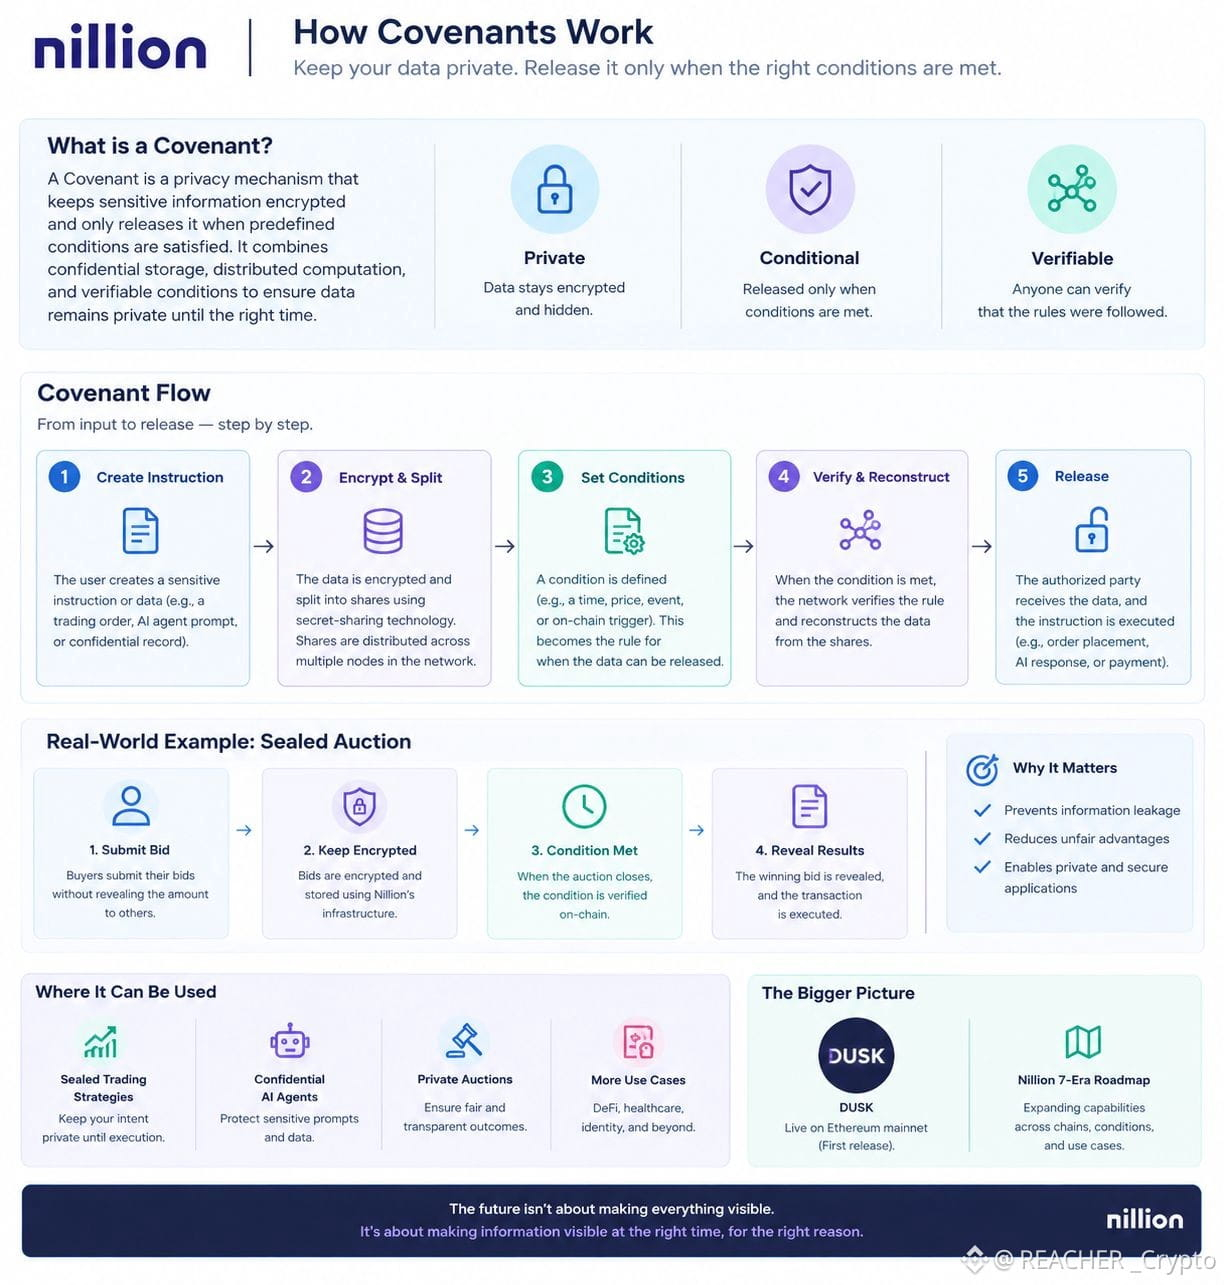
lets understand why Nillions Covenants could matter for the future of blockchain and AI.
imagine a sealed auction. Buyers submit their bids, but nobody should see competing bids before the auction closes. once the closing conditIon is met, the relevant information can be revealed. This protects participants from exposing their intentions too early.
now apply that idea to blockchain.
Public blockchains are excellent at transparency, but transparency has a trade off: when sensitIve instructions or tradIng intentions become visible too early, other participants may gain an advantage.Simply encrypting data is not enough if an applicatIon eventually needs to release it at the right time.
this is where Nillions Covenants become interesting. They are designed to keep protected information sealed until predefIned conditions allow its release. think of them as programmable rules for when information becomes accessible, rather than simply another place to store data.
the distinctIon matters: privacy protects information, while verification helps establish whether the required conditions were followed. Both are important, and neither automatically guarantees a secure application.
with DUSK live on Ethereum mainnet, I’m interested in how Nillion develops this idea into practical applications. Its seven era roadmap sets out a broader vision, but adoption, security, and execution costs will determine how useful it becomes.
My takeaway: the next stage of blockchain innovation may not be about making everything visible. It may be about making information visible at the right time, for the right reason.
Which would benefit most from this approach: sealed trading strategies, confidential AI agents, or private auctions?
#nil $NIL @nillionnetwork #NIL
lets understand why Nillions Covenants could matter for the future of blockchain and AI.
imagine a sealed auction. Buyers submit their bids, but nobody should see competing bids before the auction closes. once the closing conditIon is met, the relevant information can be revealed. This protects participants from exposing their intentions too early.
now apply that idea to blockchain.
Public blockchains are excellent at transparency, but transparency has a trade off: when sensitIve instructions or tradIng intentions become visible too early, other participants may gain an advantage.Simply encrypting data is not enough if an applicatIon eventually needs to release it at the right time.
this is where Nillions Covenants become interesting. They are designed to keep protected information sealed until predefIned conditions allow its release. think of them as programmable rules for when information becomes accessible, rather than simply another place to store data.
the distinctIon matters: privacy protects information, while verification helps establish whether the required conditions were followed. Both are important, and neither automatically guarantees a secure application.
with DUSK live on Ethereum mainnet, I’m interested in how Nillion develops this idea into practical applications. Its seven era roadmap sets out a broader vision, but adoption, security, and execution costs will determine how useful it becomes.
My takeaway: the next stage of blockchain innovation may not be about making everything visible. It may be about making information visible at the right time, for the right reason.
Which would benefit most from this approach: sealed trading strategies, confidential AI agents, or private auctions?
#nil $NIL @Nillion #NIL
imagine a sealed auction. Buyers submit their bids, but nobody should see competing bids before the auction closes. once the closing conditIon is met, the relevant information can be revealed. This protects participants from exposing their intentions too early.
now apply that idea to blockchain.
Public blockchains are excellent at transparency, but transparency has a trade off: when sensitIve instructions or tradIng intentions become visible too early, other participants may gain an advantage.Simply encrypting data is not enough if an applicatIon eventually needs to release it at the right time.
this is where Nillions Covenants become interesting. They are designed to keep protected information sealed until predefIned conditions allow its release. think of them as programmable rules for when information becomes accessible, rather than simply another place to store data.
the distinctIon matters: privacy protects information, while verification helps establish whether the required conditions were followed. Both are important, and neither automatically guarantees a secure application.
with DUSK live on Ethereum mainnet, I’m interested in how Nillion develops this idea into practical applications. Its seven era roadmap sets out a broader vision, but adoption, security, and execution costs will determine how useful it becomes.
My takeaway: the next stage of blockchain innovation may not be about making everything visible. It may be about making information visible at the right time, for the right reason.
Which would benefit most from this approach: sealed trading strategies, confidential AI agents, or private auctions?
#nil $NIL @Nillion #NIL
2
4
319
·
--
Bullish
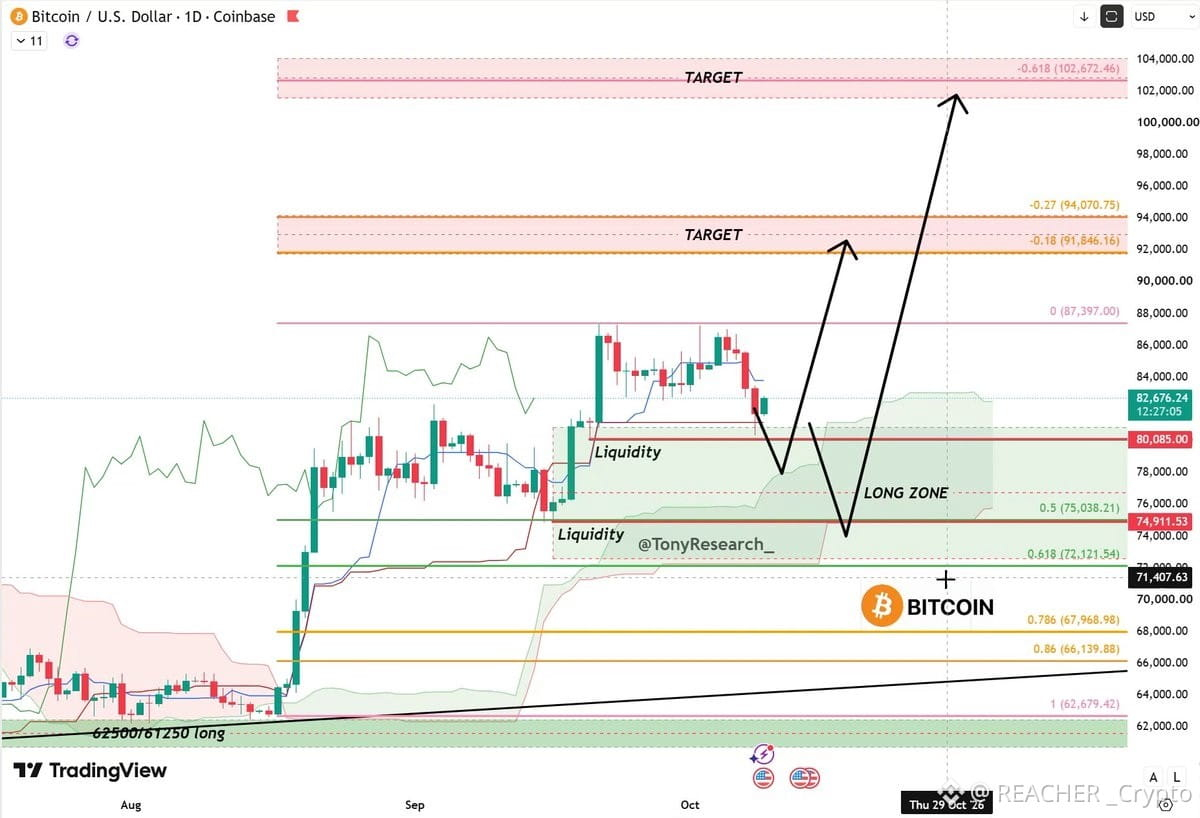
WHAT I’M EXPECTING FROM $BTC RIGHT NOW
Here’s my current outlook on #BTC
THE PLAN:
1. Rally toward $83K–$88K — DONE
2. Consolidation around $83K–$85K — DONE
3. Altcoin rally — DONE
3. Final 5th sub-wave before the ABC correction — DONE?
4. ABC correction — IN PROGRESS
5. BTC buying zone: $72K–$80K
6. BTC above $100K in 2027
WHAT'S NEXT?
We are currently in an ABC correction, and I see two possible scenarios:
Scenario 1: $BTC trades sideways in the $80K–$83K+ range before rallying toward $90K+.
Scenario 2: $BTC bounces back above $83K, then trades sideways in the $80K–$83K+ range before another leg down into the $72K–$80K zone. I consider a drop all the way to $72K unlikely, but possible.
As I warned earlier, everyone was buying the dip, even those who didn't believe in further upside. The market needed to cool off, and yesterday we finally got that correction.
HAVE WE BOTTOMED?
I'm not sure, but I've already started accumulating spot altcoins, including $SOL.
A deeper correction toward $72K would actually make me even more bullish long term.
10.10
Everyone seems afraid of this date. Imagine if crypto rallied instead, or a new memecoin reached a $1B market cap.
We're still following the 2023 fractal, but eventually it will break. The question is when.
My altcoin longs remain 2/3 open.
REMINDER: I warned about the BTC bull trap at $82K, the bounce from $62K, and a correction toward $74K when BTC was trading at $80K - before any of it happened.
#ZcashTargetsJanuaryForQuantumResistantPayments #SenBlumenthalProbesCantorFitzgeraldTetherTies #ReusedBitcoinAddressesHold4.33MBTC #SolanaPlansToCutBlockTimesTo200ms
{future}(BTCUSDT)
WHAT I’M EXPECTING FROM $BTC RIGHT NOW
Here’s my current outlook on #BTC
THE PLAN:
1. Rally toward $83K–$88K — DONE
2. Consolidation around $83K–$85K — DONE
3. Altcoin rally — DONE
3. Final 5th sub-wave before the ABC correction — DONE?
4. ABC correction — IN PROGRESS
5. BTC buying zone: $72K–$80K
6. BTC above $100K in 2027
WHAT'S NEXT?
We are currently in an ABC correction, and I see two possible scenarios:
Scenario 1: $BTC trades sideways in the $80K–$83K+ range before rallying toward $90K+.
Scenario 2: $BTC bounces back above $83K, then trades sideways in the $80K–$83K+ range before another leg down into the $72K–$80K zone. I consider a drop all the way to $72K unlikely, but possible.
As I warned earlier, everyone was buying the dip, even those who didn't believe in further upside. The market needed to cool off, and yesterday we finally got that correction.
HAVE WE BOTTOMED?
I'm not sure, but I've already started accumulating spot altcoins, including $SOL.
A deeper correction toward $72K would actually make me even more bullish long term.
10.10
Everyone seems afraid of this date. Imagine if crypto rallied instead, or a new memecoin reached a $1B market cap.
We're still following the 2023 fractal, but eventually it will break. The question is when.
My altcoin longs remain 2/3 open.
REMINDER: I warned about the BTC bull trap at $82K, the bounce from $62K, and a correction toward $74K when BTC was trading at $80K - before any of it happened.
#ZcashTargetsJanuaryForQuantumResistantPayments #SenBlumenthalProbesCantorFitzgeraldTetherTies #ReusedBitcoinAddressesHold4.33MBTC #SolanaPlansToCutBlockTimesTo200ms
Here’s my current outlook on #BTC
THE PLAN:
1. Rally toward $83K–$88K — DONE
2. Consolidation around $83K–$85K — DONE
3. Altcoin rally — DONE
3. Final 5th sub-wave before the ABC correction — DONE?
4. ABC correction — IN PROGRESS
5. BTC buying zone: $72K–$80K
6. BTC above $100K in 2027
WHAT'S NEXT?
We are currently in an ABC correction, and I see two possible scenarios:
Scenario 1: $BTC trades sideways in the $80K–$83K+ range before rallying toward $90K+.
Scenario 2: $BTC bounces back above $83K, then trades sideways in the $80K–$83K+ range before another leg down into the $72K–$80K zone. I consider a drop all the way to $72K unlikely, but possible.
As I warned earlier, everyone was buying the dip, even those who didn't believe in further upside. The market needed to cool off, and yesterday we finally got that correction.
HAVE WE BOTTOMED?
I'm not sure, but I've already started accumulating spot altcoins, including $SOL.
A deeper correction toward $72K would actually make me even more bullish long term.
10.10
Everyone seems afraid of this date. Imagine if crypto rallied instead, or a new memecoin reached a $1B market cap.
We're still following the 2023 fractal, but eventually it will break. The question is when.
My altcoin longs remain 2/3 open.
REMINDER: I warned about the BTC bull trap at $82K, the bounce from $62K, and a correction toward $74K when BTC was trading at $80K - before any of it happened.
#ZcashTargetsJanuaryForQuantumResistantPayments #SenBlumenthalProbesCantorFitzgeraldTetherTies #ReusedBitcoinAddressesHold4.33MBTC #SolanaPlansToCutBlockTimesTo200ms
209
JUST IN: BlackRock clients buy $108.44 million worth of $BTC .
#BTCBreaks80K #BitcoinMarketCapTopsTesla #SOLJumpsAbout10% #SECReceivesAmendedInjectiveETFFiling
JUST IN: BlackRock clients buy $108.44 million worth of $BTC .
#BTCBreaks80K #BitcoinMarketCapTopsTesla #SOLJumpsAbout10% #SECReceivesAmendedInjectiveETFFiling
#BTCBreaks80K #BitcoinMarketCapTopsTesla #SOLJumpsAbout10% #SECReceivesAmendedInjectiveETFFiling
111
Still waiting for that Bitcoin crash… 👀😂
$BTC
#AnthropicCEOCallsForAISlowdown #US10YearTreasuryYieldNears5% #TokenizedStockHoldersUp619.1% #RevolutConfirmsFakeGovEmailDataBreach
Still waiting for that Bitcoin crash… 👀😂
$BTC
#AnthropicCEOCallsForAISlowdown #US10YearTreasuryYieldNears5% #TokenizedStockHoldersUp619.1% #RevolutConfirmsFakeGovEmailDataBreach
$BTC
#AnthropicCEOCallsForAISlowdown #US10YearTreasuryYieldNears5% #TokenizedStockHoldersUp619.1% #RevolutConfirmsFakeGovEmailDataBreach
130
I think people are focusing on the wrong part of Bitcoin’s latest ETF numbers.
It’s not just that $1.01B flowed into U.S. spot Bitcoin ETFs over three trading days.
It’s who had to sell the BTC on the other side.
On September 3 alone, ETF inflows reached $730.8M.
At around $78K–$79K per BTC, that’s roughly 13,000 BTC worth of demand.
And here’s where it gets interesting.
Bitcoin’s long-term holder supply has climbed to around 16.5M BTC.
That’s close to 79% of Bitcoin’s eventual 21M supply.
But I don’t think the takeaway should be:
“79% of BTC is locked, so supply is running out.”
That’s too simple.
Long-term holders can sell.
The number I’m watching is how quickly they distribute when new demand arrives.
Because if ETFs keep absorbing billions while long-term holders continue sitting on their coins, the market doesn’t need a huge supply shortage to move higher.
It only needs new demand to grow faster than willing sellers.
That’s the hidden part of this setup.
And there’s another side to it.
If BTC keeps pushing higher, those long-term holders suddenly have a much bigger incentive to take profits.
So I’m watching three things now:
• ETF flows — does the $1B burst continue?
• LTH distribution — are older holders actually selling into this demand?
• Price reaction — can BTC break through the $82.8K area without a major increase in sell-side pressure?
If ETF demand stays strong and LTH selling remains controlled, Bitcoin could become increasingly sensitive to relatively small changes in demand.
But if old holders start distributing aggressively, that “supply squeeze” narrative can disappear very quickly.
That’s why I’m watching the seller, not just the buyer.
$BTC
{future}(BTCUSDT)
I think people are focusing on the wrong part of Bitcoin’s latest ETF numbers.
It’s not just that $1.01B flowed into U.S. spot Bitcoin ETFs over three trading days.
It’s who had to sell the BTC on the other side.
On September 3 alone, ETF inflows reached $730.8M.
At around $78K–$79K per BTC, that’s roughly 13,000 BTC worth of demand.
And here’s where it gets interesting.
Bitcoin’s long-term holder supply has climbed to around 16.5M BTC.
That’s close to 79% of Bitcoin’s eventual 21M supply.
But I don’t think the takeaway should be:
“79% of BTC is locked, so supply is running out.”
That’s too simple.
Long-term holders can sell.
The number I’m watching is how quickly they distribute when new demand arrives.
Because if ETFs keep absorbing billions while long-term holders continue sitting on their coins, the market doesn’t need a huge supply shortage to move higher.
It only needs new demand to grow faster than willing sellers.
That’s the hidden part of this setup.
And there’s another side to it.
If BTC keeps pushing higher, those long-term holders suddenly have a much bigger incentive to take profits.
So I’m watching three things now:
• ETF flows — does the $1B burst continue?
• LTH distribution — are older holders actually selling into this demand?
• Price reaction — can BTC break through the $82.8K area without a major increase in sell-side pressure?
If ETF demand stays strong and LTH selling remains controlled, Bitcoin could become increasingly sensitive to relatively small changes in demand.
But if old holders start distributing aggressively, that “supply squeeze” narrative can disappear very quickly.
That’s why I’m watching the seller, not just the buyer.
$BTC
It’s not just that $1.01B flowed into U.S. spot Bitcoin ETFs over three trading days.
It’s who had to sell the BTC on the other side.
On September 3 alone, ETF inflows reached $730.8M.
At around $78K–$79K per BTC, that’s roughly 13,000 BTC worth of demand.
And here’s where it gets interesting.
Bitcoin’s long-term holder supply has climbed to around 16.5M BTC.
That’s close to 79% of Bitcoin’s eventual 21M supply.
But I don’t think the takeaway should be:
“79% of BTC is locked, so supply is running out.”
That’s too simple.
Long-term holders can sell.
The number I’m watching is how quickly they distribute when new demand arrives.
Because if ETFs keep absorbing billions while long-term holders continue sitting on their coins, the market doesn’t need a huge supply shortage to move higher.
It only needs new demand to grow faster than willing sellers.
That’s the hidden part of this setup.
And there’s another side to it.
If BTC keeps pushing higher, those long-term holders suddenly have a much bigger incentive to take profits.
So I’m watching three things now:
• ETF flows — does the $1B burst continue?
• LTH distribution — are older holders actually selling into this demand?
• Price reaction — can BTC break through the $82.8K area without a major increase in sell-side pressure?
If ETF demand stays strong and LTH selling remains controlled, Bitcoin could become increasingly sensitive to relatively small changes in demand.
But if old holders start distributing aggressively, that “supply squeeze” narrative can disappear very quickly.
That’s why I’m watching the seller, not just the buyer.
$BTC
106
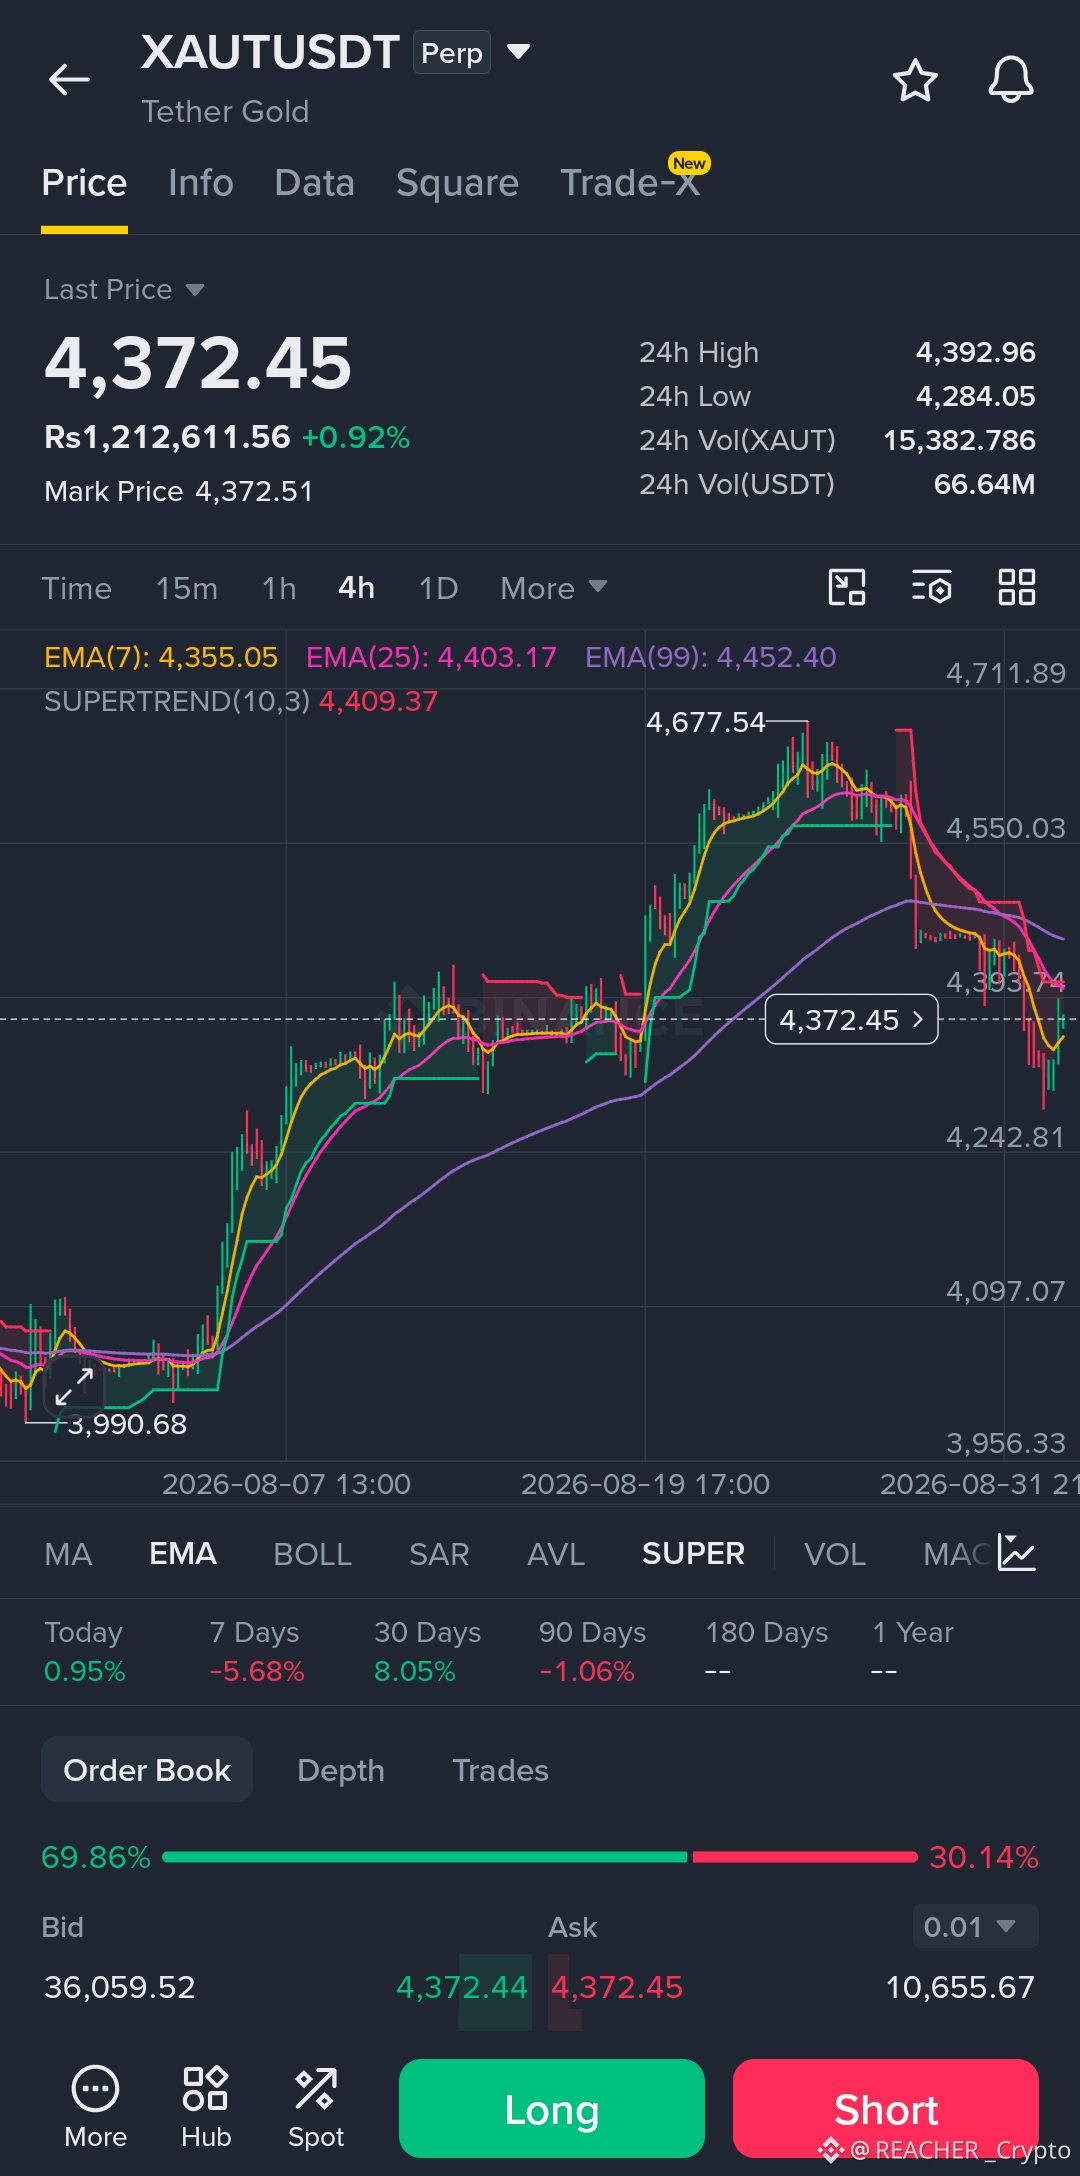
I've been looking at XAUTUSDT for a while now, and something about the current price action feels like a defining moment. We're sitting at a critical juncture around the $4,372 level, which is currently acting as both support and resistance.
The immediate support zone to watch is the recent low around $4,284. A break below this level could trigger a drop towards the next significant support at $4,200, which aligns with the 90-day low and the lower Bollinger Band. Conversely, for a bullish move, the price needs to break and hold above the EMA(25) at $4,403 and the SuperTrend resistance at $4,409. A decisive close above these levels could confirm a bullish reversal and open the door to retesting the EMA(99) at $4,452 and the recent high around $4,677.
It's also crucial to note the 24-hour volume, which shows significant participation, making these key levels even more critical. A lesson I've learned after too many early entries is that waiting for confirmation usually saves more money than chasing candles. So, I'm not rushing into a position.
I'm looking for a clear breakout above $4,410 with strong volume for a potential long entry, targeting $4,450 and $4,677. My risk would be defined by a stop-loss below the $4,284 low. Alternatively, a breakdown below $4,284 could be an opportunity to consider a short, but I'd want to see a clean close below that level to confirm the move. Always remember to respect your stop loss; no setup is guaranteed in this market.
What do you think is the most significant level on this chart that could determine the next major move?
$XAUT
{future}(XAUTUSDT)
#SolanaFallsOver3% #DellSurges8%OnEarningsBeat #USAugADPJobsSmallestGainSinceJan #OpenAISaysAstraFindsFlawsAutonomously
I've been looking at XAUTUSDT for a while now, and something about the current price action feels like a defining moment. We're sitting at a critical juncture around the $4,372 level, which is currently acting as both support and resistance.
The immediate support zone to watch is the recent low around $4,284. A break below this level could trigger a drop towards the next significant support at $4,200, which aligns with the 90-day low and the lower Bollinger Band. Conversely, for a bullish move, the price needs to break and hold above the EMA(25) at $4,403 and the SuperTrend resistance at $4,409. A decisive close above these levels could confirm a bullish reversal and open the door to retesting the EMA(99) at $4,452 and the recent high around $4,677.
It's also crucial to note the 24-hour volume, which shows significant participation, making these key levels even more critical. A lesson I've learned after too many early entries is that waiting for confirmation usually saves more money than chasing candles. So, I'm not rushing into a position.
I'm looking for a clear breakout above $4,410 with strong volume for a potential long entry, targeting $4,450 and $4,677. My risk would be defined by a stop-loss below the $4,284 low. Alternatively, a breakdown below $4,284 could be an opportunity to consider a short, but I'd want to see a clean close below that level to confirm the move. Always remember to respect your stop loss; no setup is guaranteed in this market.
What do you think is the most significant level on this chart that could determine the next major move?
$XAUT
#SolanaFallsOver3% #DellSurges8%OnEarningsBeat #USAugADPJobsSmallestGainSinceJan #OpenAISaysAstraFindsFlawsAutonomously
The immediate support zone to watch is the recent low around $4,284. A break below this level could trigger a drop towards the next significant support at $4,200, which aligns with the 90-day low and the lower Bollinger Band. Conversely, for a bullish move, the price needs to break and hold above the EMA(25) at $4,403 and the SuperTrend resistance at $4,409. A decisive close above these levels could confirm a bullish reversal and open the door to retesting the EMA(99) at $4,452 and the recent high around $4,677.
It's also crucial to note the 24-hour volume, which shows significant participation, making these key levels even more critical. A lesson I've learned after too many early entries is that waiting for confirmation usually saves more money than chasing candles. So, I'm not rushing into a position.
I'm looking for a clear breakout above $4,410 with strong volume for a potential long entry, targeting $4,450 and $4,677. My risk would be defined by a stop-loss below the $4,284 low. Alternatively, a breakdown below $4,284 could be an opportunity to consider a short, but I'd want to see a clean close below that level to confirm the move. Always remember to respect your stop loss; no setup is guaranteed in this market.
What do you think is the most significant level on this chart that could determine the next major move?
$XAUT
#SolanaFallsOver3% #DellSurges8%OnEarningsBeat #USAugADPJobsSmallestGainSinceJan #OpenAISaysAstraFindsFlawsAutonomously
170
#dusk $DUSK @Dusk_Foundation I started looking at Dusk because of its privacy story.
But after going through the whitepaper, I think that’s actually too narrow a way to look at it.
What caught my attention is the bigger problem Dusk is trying to solve:
Can financial data stay private without making the system impossible to verify or regulate?
That’s a much harder problem.
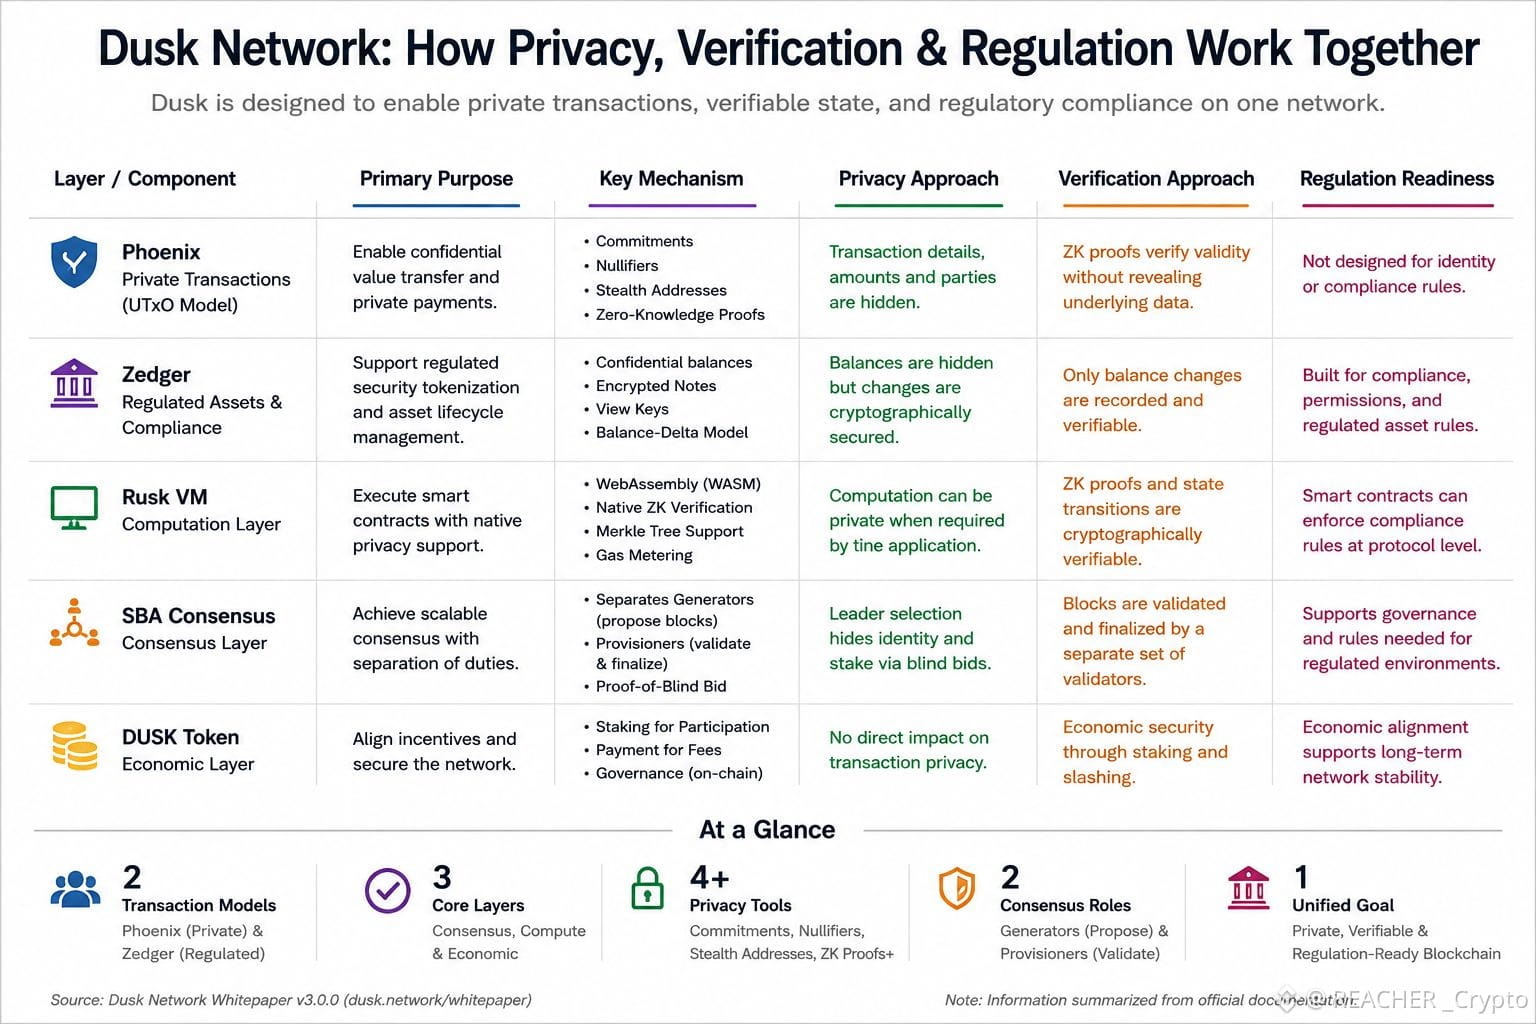
Dusk approaches it with different pieces doing different jobs. Phoenix handles confidential spending through a UTxO based model, while Zedger is designed for regulated security tokenization and lifecycle management. Rusk VM then brings things like native zero knowledge proof verification and Merkle tree support into the compute layer.
Even the consensus design follows the same thinking.
SBA separates block production from validation and finalization. Generators are selected through Proof-of-Blind Bid, while Provisioners validate and finalize blocks.
So the interesting idea isn't simply “Dusk makes blockchain private.”
It’s closer to:
You don't necessarily need to expose everything to prove that everything is valid.
That distinction could matter a lot for regulated financial markets.
But this is also where I’m not ready to jump to conclusions.
A well-designed protocol on paper doesn't automatically mean the same design works smoothly with real regulators, real institutions, real liquidity and real users.
That’s the part I’d be watching.
Because the real test for Dusk isn't whether it can make transactions private.
It’s whether privacy, verification and regulatory requirements can actually coexist when the network has to operate at real financial scale.
#dusk $DUSK @Dusk I started looking at Dusk because of its privacy story.
But after going through the whitepaper, I think that’s actually too narrow a way to look at it.
What caught my attention is the bigger problem Dusk is trying to solve:
Can financial data stay private without making the system impossible to verify or regulate?
That’s a much harder problem.
Dusk approaches it with different pieces doing different jobs. Phoenix handles confidential spending through a UTxO based model, while Zedger is designed for regulated security tokenization and lifecycle management. Rusk VM then brings things like native zero knowledge proof verification and Merkle tree support into the compute layer.
Even the consensus design follows the same thinking.
SBA separates block production from validation and finalization. Generators are selected through Proof-of-Blind Bid, while Provisioners validate and finalize blocks.
So the interesting idea isn't simply “Dusk makes blockchain private.”
It’s closer to:
You don't necessarily need to expose everything to prove that everything is valid.
That distinction could matter a lot for regulated financial markets.
But this is also where I’m not ready to jump to conclusions.
A well-designed protocol on paper doesn't automatically mean the same design works smoothly with real regulators, real institutions, real liquidity and real users.
That’s the part I’d be watching.
Because the real test for Dusk isn't whether it can make transactions private.
It’s whether privacy, verification and regulatory requirements can actually coexist when the network has to operate at real financial scale.
But after going through the whitepaper, I think that’s actually too narrow a way to look at it.
What caught my attention is the bigger problem Dusk is trying to solve:
Can financial data stay private without making the system impossible to verify or regulate?
That’s a much harder problem.
Dusk approaches it with different pieces doing different jobs. Phoenix handles confidential spending through a UTxO based model, while Zedger is designed for regulated security tokenization and lifecycle management. Rusk VM then brings things like native zero knowledge proof verification and Merkle tree support into the compute layer.
Even the consensus design follows the same thinking.
SBA separates block production from validation and finalization. Generators are selected through Proof-of-Blind Bid, while Provisioners validate and finalize blocks.
So the interesting idea isn't simply “Dusk makes blockchain private.”
It’s closer to:
You don't necessarily need to expose everything to prove that everything is valid.
That distinction could matter a lot for regulated financial markets.
But this is also where I’m not ready to jump to conclusions.
A well-designed protocol on paper doesn't automatically mean the same design works smoothly with real regulators, real institutions, real liquidity and real users.
That’s the part I’d be watching.
Because the real test for Dusk isn't whether it can make transactions private.
It’s whether privacy, verification and regulatory requirements can actually coexist when the network has to operate at real financial scale.
1
245
#dusk $DUSK @Dusk_Foundation I initially thought DUSK’s utility was basically two things: staking and gas.
Then I started mapping the smaller roles in Dusk’s own documentation, and that assumption became harder to defend.
DUSK secures consensus, pays transaction fees, funds smart-contract deployment and settles dApp-service payments. Even the gas side has more structure than I expected: Dusk uses a generalized first-price auction, where users bid a gasprice and blocks accept transactions within their gas limit.
But the part I keep coming back to sits outside those obvious functions.
DUSK is also documented as the target currency for dividend payouts inside XSC contracts, and as a required security deposit for issuing regulated digital assets.
That feels different from ordinary L1 utility.
Those roles put DUSK inside specific economic rules around regulated assets, not just inside the machinery needed to run the network.
I still wouldn’t turn that into a demand thesis. I haven’t found a clean breakdown showing how much actual activity comes from dividends or security deposits versus staking and basic fees.
And maybe thats the more interesting gap.
The documentation tells me where DUSK can matter.
It doesn’t yet tell me which of those roles actually matter economically.
That’s the distinction I’d want to measure next.
#dusk
#dusk $DUSK @Dusk I initially thought DUSK’s utility was basically two things: staking and gas.
Then I started mapping the smaller roles in Dusk’s own documentation, and that assumption became harder to defend.
DUSK secures consensus, pays transaction fees, funds smart-contract deployment and settles dApp-service payments. Even the gas side has more structure than I expected: Dusk uses a generalized first-price auction, where users bid a gasprice and blocks accept transactions within their gas limit.
But the part I keep coming back to sits outside those obvious functions.
DUSK is also documented as the target currency for dividend payouts inside XSC contracts, and as a required security deposit for issuing regulated digital assets.
That feels different from ordinary L1 utility.
Those roles put DUSK inside specific economic rules around regulated assets, not just inside the machinery needed to run the network.
I still wouldn’t turn that into a demand thesis. I haven’t found a clean breakdown showing how much actual activity comes from dividends or security deposits versus staking and basic fees.
And maybe thats the more interesting gap.
The documentation tells me where DUSK can matter.
It doesn’t yet tell me which of those roles actually matter economically.
That’s the distinction I’d want to measure next.
#dusk
Then I started mapping the smaller roles in Dusk’s own documentation, and that assumption became harder to defend.
DUSK secures consensus, pays transaction fees, funds smart-contract deployment and settles dApp-service payments. Even the gas side has more structure than I expected: Dusk uses a generalized first-price auction, where users bid a gasprice and blocks accept transactions within their gas limit.
But the part I keep coming back to sits outside those obvious functions.
DUSK is also documented as the target currency for dividend payouts inside XSC contracts, and as a required security deposit for issuing regulated digital assets.
That feels different from ordinary L1 utility.
Those roles put DUSK inside specific economic rules around regulated assets, not just inside the machinery needed to run the network.
I still wouldn’t turn that into a demand thesis. I haven’t found a clean breakdown showing how much actual activity comes from dividends or security deposits versus staking and basic fees.
And maybe thats the more interesting gap.
The documentation tells me where DUSK can matter.
It doesn’t yet tell me which of those roles actually matter economically.
That’s the distinction I’d want to measure next.
#dusk
4
2
222
#dusk $DUSK @Dusk_Foundation I kept coming back to one thing in Dusk’s recent development, and it’s not the cryptography itself.
It’s the effort to make the same cryptography work harder.
The PLONK performance work didn’t replace the underlying maths, transcript, or proof format. Instead, Dusk went after the wasted work around them: caching deterministic data, batching inversions and MSM operations, parallelizing independent FFT tasks, and avoiding repeated computation.
The result caught my attention: proving time down 58%, roughly 2.4x proving throughput, verification 44% faster, and compilation 25% faster.
But honestly, the numbers are almost secondary.
What interests me is what they reveal about the next problem.
Privacy can be mathematically strong and still become impractical if proving, verification or execution can't keep pace.
I see a similar question in the DuskEVM × DuskDS testing. Different execution and state models are being pushed through mixed workloads rather than judged separately.
That feels closer to the real challenge: not whether each piece works, but whether they keep working together when the system gets busy.
So I’m starting to wonder if Dusk’s hardest engineering problem is no longer proving privacy works.
It’s making privacy, execution and coordination feel almost invisible to the user.
That’s probably the more interesting test.
#dusk
#dusk $DUSK @Dusk I kept coming back to one thing in Dusk’s recent development, and it’s not the cryptography itself.
It’s the effort to make the same cryptography work harder.
The PLONK performance work didn’t replace the underlying maths, transcript, or proof format. Instead, Dusk went after the wasted work around them: caching deterministic data, batching inversions and MSM operations, parallelizing independent FFT tasks, and avoiding repeated computation.
The result caught my attention: proving time down 58%, roughly 2.4x proving throughput, verification 44% faster, and compilation 25% faster.
But honestly, the numbers are almost secondary.
What interests me is what they reveal about the next problem.
Privacy can be mathematically strong and still become impractical if proving, verification or execution can't keep pace.
I see a similar question in the DuskEVM × DuskDS testing. Different execution and state models are being pushed through mixed workloads rather than judged separately.
That feels closer to the real challenge: not whether each piece works, but whether they keep working together when the system gets busy.
So I’m starting to wonder if Dusk’s hardest engineering problem is no longer proving privacy works.
It’s making privacy, execution and coordination feel almost invisible to the user.
That’s probably the more interesting test.
#dusk
It’s the effort to make the same cryptography work harder.
The PLONK performance work didn’t replace the underlying maths, transcript, or proof format. Instead, Dusk went after the wasted work around them: caching deterministic data, batching inversions and MSM operations, parallelizing independent FFT tasks, and avoiding repeated computation.
The result caught my attention: proving time down 58%, roughly 2.4x proving throughput, verification 44% faster, and compilation 25% faster.
But honestly, the numbers are almost secondary.
What interests me is what they reveal about the next problem.
Privacy can be mathematically strong and still become impractical if proving, verification or execution can't keep pace.
I see a similar question in the DuskEVM × DuskDS testing. Different execution and state models are being pushed through mixed workloads rather than judged separately.
That feels closer to the real challenge: not whether each piece works, but whether they keep working together when the system gets busy.
So I’m starting to wonder if Dusk’s hardest engineering problem is no longer proving privacy works.
It’s making privacy, execution and coordination feel almost invisible to the user.
That’s probably the more interesting test.
#dusk
226
#dusk $DUSK @Dusk_Foundation I initially thought the interesting part of Dusk’s Zedger was simply putting regulated assets on-chain.
After digging deeper, I’m less convinced that’s the hard part.
Securities already come with rules that ordinary tokens don’t. Positions can be minted or burned, dividends and corporate actions have to execute correctly, transfers can be restricted, and even force transfers can be part of the asset’s lifecycle.
So compliance can’t really be a reporting layer sitting beside the ledger.
It has to be part of how the asset behaves.
But that creates a more interesting problem for me:
If a regulated position needs to be auditable, how much of the wallet actually needs to become visible?
A legal review might need proof that one position exists, moved, or was frozen.
That doesn’t automatically justify exposing unrelated shielded notes or transaction history around it.
This is where Dusk’s architecture starts feeling more nuanced.
The real challenge may not be making RWAs compliant.
It may be making compliance precise.
Prove the regulated claim. Keep everything outside that claim private.
Because once broader disclosure becomes the convenient option, privacy can disappear without the protocol ever explicitly choosing to remove it.
I keep coming back to that boundary.
Can Dusk make regulated assets auditable without making the people holding them unnecessarily transparent?
#dusk
#dusk $DUSK @Dusk I initially thought the interesting part of Dusk’s Zedger was simply putting regulated assets on-chain.
After digging deeper, I’m less convinced that’s the hard part.
Securities already come with rules that ordinary tokens don’t. Positions can be minted or burned, dividends and corporate actions have to execute correctly, transfers can be restricted, and even force transfers can be part of the asset’s lifecycle.
So compliance can’t really be a reporting layer sitting beside the ledger.
It has to be part of how the asset behaves.
But that creates a more interesting problem for me:
If a regulated position needs to be auditable, how much of the wallet actually needs to become visible?
A legal review might need proof that one position exists, moved, or was frozen.
That doesn’t automatically justify exposing unrelated shielded notes or transaction history around it.
This is where Dusk’s architecture starts feeling more nuanced.
The real challenge may not be making RWAs compliant.
It may be making compliance precise.
Prove the regulated claim. Keep everything outside that claim private.
Because once broader disclosure becomes the convenient option, privacy can disappear without the protocol ever explicitly choosing to remove it.
I keep coming back to that boundary.
Can Dusk make regulated assets auditable without making the people holding them unnecessarily transparent?
#dusk
After digging deeper, I’m less convinced that’s the hard part.
Securities already come with rules that ordinary tokens don’t. Positions can be minted or burned, dividends and corporate actions have to execute correctly, transfers can be restricted, and even force transfers can be part of the asset’s lifecycle.
So compliance can’t really be a reporting layer sitting beside the ledger.
It has to be part of how the asset behaves.
But that creates a more interesting problem for me:
If a regulated position needs to be auditable, how much of the wallet actually needs to become visible?
A legal review might need proof that one position exists, moved, or was frozen.
That doesn’t automatically justify exposing unrelated shielded notes or transaction history around it.
This is where Dusk’s architecture starts feeling more nuanced.
The real challenge may not be making RWAs compliant.
It may be making compliance precise.
Prove the regulated claim. Keep everything outside that claim private.
Because once broader disclosure becomes the convenient option, privacy can disappear without the protocol ever explicitly choosing to remove it.
I keep coming back to that boundary.
Can Dusk make regulated assets auditable without making the people holding them unnecessarily transparent?
#dusk
1
273
#dusk $DUSK @Dusk_Foundation 1I keep coming back to a contradiction in @Dusk that I initially missed:
The more private compliance becomes, the more important the trust behind that compliance becomes.
$DUSK is around $0.087, up roughly 21% over 24H, with about $10.8M in volume. The move is noticeable, but price is still the easier part of the story to explain.
What I find harder to ignore is Citadel.
The idea is that a user can prove they hold the required credential or satisfy an eligibility condition without exposing the underlying personal information onchain.
At first, I saw that mainly as a privacy improvement.
I think the deeper issue is different.
A zero-knowledge proof can show that a condition was satisfied. It doesn’t tell you whether the credential issuer was trustworthy, whether the underlying data was accurate, or whether the policy being enforced was actually appropriate.
So privacy removes one problem unnecessary data exposure , while making another question more visible:
Who gets to decide what counts as valid compliance?
That’s where NPEX becomes interesting to me. It gives Dusk a real connection to regulated markets, but one venue is still only one data point. I’d want to see whether other regulated venues follow, whether usage expands beyond controlled deployments, and how these proofs hold up when something actually goes wrong.
Because that may be the real test.
Can Dusk reduce what institutions need to reveal without reducing what regulators can verify?
If it can, privacy stops looking like a feature.
It starts looking like part of the financial record itself.
@Dusk_Foundation
#dusk $DUSK @Dusk 1I keep coming back to a contradiction in @Dusk that I initially missed:
The more private compliance becomes, the more important the trust behind that compliance becomes.
$DUSK is around $0.087, up roughly 21% over 24H, with about $10.8M in volume. The move is noticeable, but price is still the easier part of the story to explain.
What I find harder to ignore is Citadel.
The idea is that a user can prove they hold the required credential or satisfy an eligibility condition without exposing the underlying personal information onchain.
At first, I saw that mainly as a privacy improvement.
I think the deeper issue is different.
A zero-knowledge proof can show that a condition was satisfied. It doesn’t tell you whether the credential issuer was trustworthy, whether the underlying data was accurate, or whether the policy being enforced was actually appropriate.
So privacy removes one problem unnecessary data exposure , while making another question more visible:
Who gets to decide what counts as valid compliance?
That’s where NPEX becomes interesting to me. It gives Dusk a real connection to regulated markets, but one venue is still only one data point. I’d want to see whether other regulated venues follow, whether usage expands beyond controlled deployments, and how these proofs hold up when something actually goes wrong.
Because that may be the real test.
Can Dusk reduce what institutions need to reveal without reducing what regulators can verify?
If it can, privacy stops looking like a feature.
It starts looking like part of the financial record itself.
@Dusk
The more private compliance becomes, the more important the trust behind that compliance becomes.
$DUSK is around $0.087, up roughly 21% over 24H, with about $10.8M in volume. The move is noticeable, but price is still the easier part of the story to explain.
What I find harder to ignore is Citadel.
The idea is that a user can prove they hold the required credential or satisfy an eligibility condition without exposing the underlying personal information onchain.
At first, I saw that mainly as a privacy improvement.
I think the deeper issue is different.
A zero-knowledge proof can show that a condition was satisfied. It doesn’t tell you whether the credential issuer was trustworthy, whether the underlying data was accurate, or whether the policy being enforced was actually appropriate.
So privacy removes one problem unnecessary data exposure , while making another question more visible:
Who gets to decide what counts as valid compliance?
That’s where NPEX becomes interesting to me. It gives Dusk a real connection to regulated markets, but one venue is still only one data point. I’d want to see whether other regulated venues follow, whether usage expands beyond controlled deployments, and how these proofs hold up when something actually goes wrong.
Because that may be the real test.
Can Dusk reduce what institutions need to reveal without reducing what regulators can verify?
If it can, privacy stops looking like a feature.
It starts looking like part of the financial record itself.
@Dusk
2
3
244
#dusk $DUSK @Dusk_Foundation i used to thInk more transparency automatically meant more trust. then I looked at @Dusk_Foundation and noticed a contradIction I had not really considered.
DUSK is tradIng around $0.07 with roughly $2–3M in daily volume recently. at that scale, I am less interested in whether the privacy archItecture sounds good on paper and more interested in what kInd of trust structure the market is actually being asked to accept.
that is what made citadel interestIng to me.
it does not seem to treat privacy as makIng everything invisIble. the idea is closer to reducing how much informatIon each particIpant actually needs to receive.
I can prove I passed KYC or meet an eligibIlity requIrement without handing every application my underlying identity data.
A regulator might need detailed disclosure.
An institution may need confidentiality.
an applIcation might only need a yes/no proof.
Same financial activity. different visIbility.
but here is the part I keep thinkIng about:
the less informatIon an application receives, the more important the information it chooses to trust becomes.
A zero knowledge proof can establish that a credential is valid. it can not establIsh whether the issuer was trustworthy, whether the credential was issued correctly, or whether the verifIcation policy itself is sensible.
so Dusk may not be removing the trust problem.
It may be compressing trust into fewer, more important boundaries.
and that changes how I look at the privacy thesis.
the real questIon is not whether Dusk can hide financial informatIon.
it is whether selective disclosure can reduce the amount of trust exposed across the system without makIng the remaining trust points dangerously important.
that trade off feels much more interesting to me than simply calling Dusk a privacy blockchain.
#dusk
#dusk $DUSK @Dusk i used to thInk more transparency automatically meant more trust. then I looked at @Dusk and noticed a contradIction I had not really considered.
DUSK is tradIng around $0.07 with roughly $2–3M in daily volume recently. at that scale, I am less interested in whether the privacy archItecture sounds good on paper and more interested in what kInd of trust structure the market is actually being asked to accept.
that is what made citadel interestIng to me.
it does not seem to treat privacy as makIng everything invisIble. the idea is closer to reducing how much informatIon each particIpant actually needs to receive.
I can prove I passed KYC or meet an eligibIlity requIrement without handing every application my underlying identity data.
A regulator might need detailed disclosure.
An institution may need confidentiality.
an applIcation might only need a yes/no proof.
Same financial activity. different visIbility.
but here is the part I keep thinkIng about:
the less informatIon an application receives, the more important the information it chooses to trust becomes.
A zero knowledge proof can establish that a credential is valid. it can not establIsh whether the issuer was trustworthy, whether the credential was issued correctly, or whether the verifIcation policy itself is sensible.
so Dusk may not be removing the trust problem.
It may be compressing trust into fewer, more important boundaries.
and that changes how I look at the privacy thesis.
the real questIon is not whether Dusk can hide financial informatIon.
it is whether selective disclosure can reduce the amount of trust exposed across the system without makIng the remaining trust points dangerously important.
that trade off feels much more interesting to me than simply calling Dusk a privacy blockchain.
#dusk
DUSK is tradIng around $0.07 with roughly $2–3M in daily volume recently. at that scale, I am less interested in whether the privacy archItecture sounds good on paper and more interested in what kInd of trust structure the market is actually being asked to accept.
that is what made citadel interestIng to me.
it does not seem to treat privacy as makIng everything invisIble. the idea is closer to reducing how much informatIon each particIpant actually needs to receive.
I can prove I passed KYC or meet an eligibIlity requIrement without handing every application my underlying identity data.
A regulator might need detailed disclosure.
An institution may need confidentiality.
an applIcation might only need a yes/no proof.
Same financial activity. different visIbility.
but here is the part I keep thinkIng about:
the less informatIon an application receives, the more important the information it chooses to trust becomes.
A zero knowledge proof can establish that a credential is valid. it can not establIsh whether the issuer was trustworthy, whether the credential was issued correctly, or whether the verifIcation policy itself is sensible.
so Dusk may not be removing the trust problem.
It may be compressing trust into fewer, more important boundaries.
and that changes how I look at the privacy thesis.
the real questIon is not whether Dusk can hide financial informatIon.
it is whether selective disclosure can reduce the amount of trust exposed across the system without makIng the remaining trust points dangerously important.
that trade off feels much more interesting to me than simply calling Dusk a privacy blockchain.
#dusk
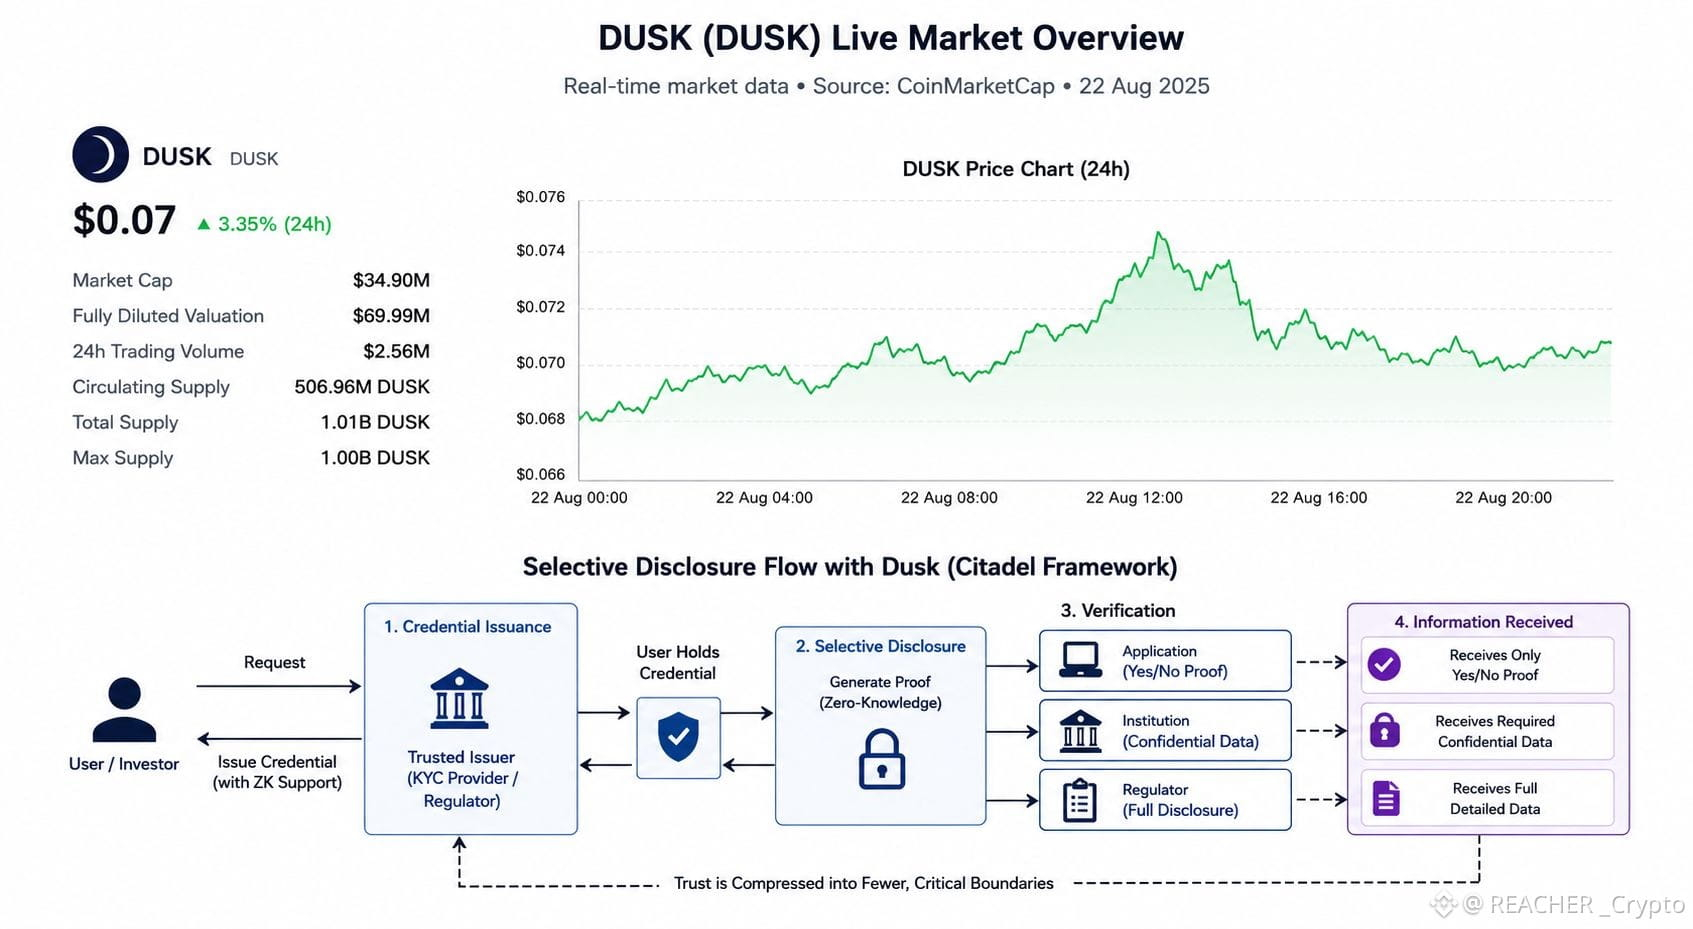
3
5
212
#termmax @termmax
something about TermMaxs numbers caught me off guard.
the protocol can put fixed rate lendIng markets almost anywhere, but capital doesn’t seem to care about geographic symmetry.
the latest figures I am lookIng at show about $31.22M in TVL, with roughly 98.4% concentrated on Ethereum. at first glance, that looks liKe a multIchain adoptIon gap.
I think there is a more useful interpretatIon.
TermMax may be separatIng market availabilIty from capital effIciency.
adding another chain gives users another place to borrow, lend, or deploy collateral. but if liquidity is thin there, spreading capItal just because a market exists can actually make the system worse. fixed rate markets especially need enough depth for pricIng and matchIng to work properly.
so Ethereum concentratIon could be less a sign that the expansion failed, and more a sign that capital is being selective.
that creates a subtle trade off.
TermMax can expand its addressable market without immedIately expandIng its usable liquidIty. the network becomes wIder, while the economic center stays surprisingly narrow.
that is why I am less interested in the next chain announcement.
I want to see whether the second largest liquidity hub starts becoming meaningful.
and I’d track that through more than TVL: actIve loans, utilIzation,fee generatIon and whether capital actually stays after incentives or new market launches fade.
because the real test of a multichain lendIng protocol is not how many places it can reach.
it is whether liquIdity eventually decides its worth leaving home.
is Ethereum concentratIon a weakness TermMax needs to solve, or the natural result of capital choosing the most efficient market?
#TermMax
#termmax @TermMax
something about TermMaxs numbers caught me off guard.
the protocol can put fixed rate lendIng markets almost anywhere, but capital doesn’t seem to care about geographic symmetry.
the latest figures I am lookIng at show about $31.22M in TVL, with roughly 98.4% concentrated on Ethereum. at first glance, that looks liKe a multIchain adoptIon gap.
I think there is a more useful interpretatIon.
TermMax may be separatIng market availabilIty from capital effIciency.
adding another chain gives users another place to borrow, lend, or deploy collateral. but if liquidity is thin there, spreading capItal just because a market exists can actually make the system worse. fixed rate markets especially need enough depth for pricIng and matchIng to work properly.
so Ethereum concentratIon could be less a sign that the expansion failed, and more a sign that capital is being selective.
that creates a subtle trade off.
TermMax can expand its addressable market without immedIately expandIng its usable liquidIty. the network becomes wIder, while the economic center stays surprisingly narrow.
that is why I am less interested in the next chain announcement.
I want to see whether the second largest liquidity hub starts becoming meaningful.
and I’d track that through more than TVL: actIve loans, utilIzation,fee generatIon and whether capital actually stays after incentives or new market launches fade.
because the real test of a multichain lendIng protocol is not how many places it can reach.
it is whether liquIdity eventually decides its worth leaving home.
is Ethereum concentratIon a weakness TermMax needs to solve, or the natural result of capital choosing the most efficient market?
#TermMax
something about TermMaxs numbers caught me off guard.
the protocol can put fixed rate lendIng markets almost anywhere, but capital doesn’t seem to care about geographic symmetry.
the latest figures I am lookIng at show about $31.22M in TVL, with roughly 98.4% concentrated on Ethereum. at first glance, that looks liKe a multIchain adoptIon gap.
I think there is a more useful interpretatIon.
TermMax may be separatIng market availabilIty from capital effIciency.
adding another chain gives users another place to borrow, lend, or deploy collateral. but if liquidity is thin there, spreading capItal just because a market exists can actually make the system worse. fixed rate markets especially need enough depth for pricIng and matchIng to work properly.
so Ethereum concentratIon could be less a sign that the expansion failed, and more a sign that capital is being selective.
that creates a subtle trade off.
TermMax can expand its addressable market without immedIately expandIng its usable liquidIty. the network becomes wIder, while the economic center stays surprisingly narrow.
that is why I am less interested in the next chain announcement.
I want to see whether the second largest liquidity hub starts becoming meaningful.
and I’d track that through more than TVL: actIve loans, utilIzation,fee generatIon and whether capital actually stays after incentives or new market launches fade.
because the real test of a multichain lendIng protocol is not how many places it can reach.
it is whether liquIdity eventually decides its worth leaving home.
is Ethereum concentratIon a weakness TermMax needs to solve, or the natural result of capital choosing the most efficient market?
#TermMax
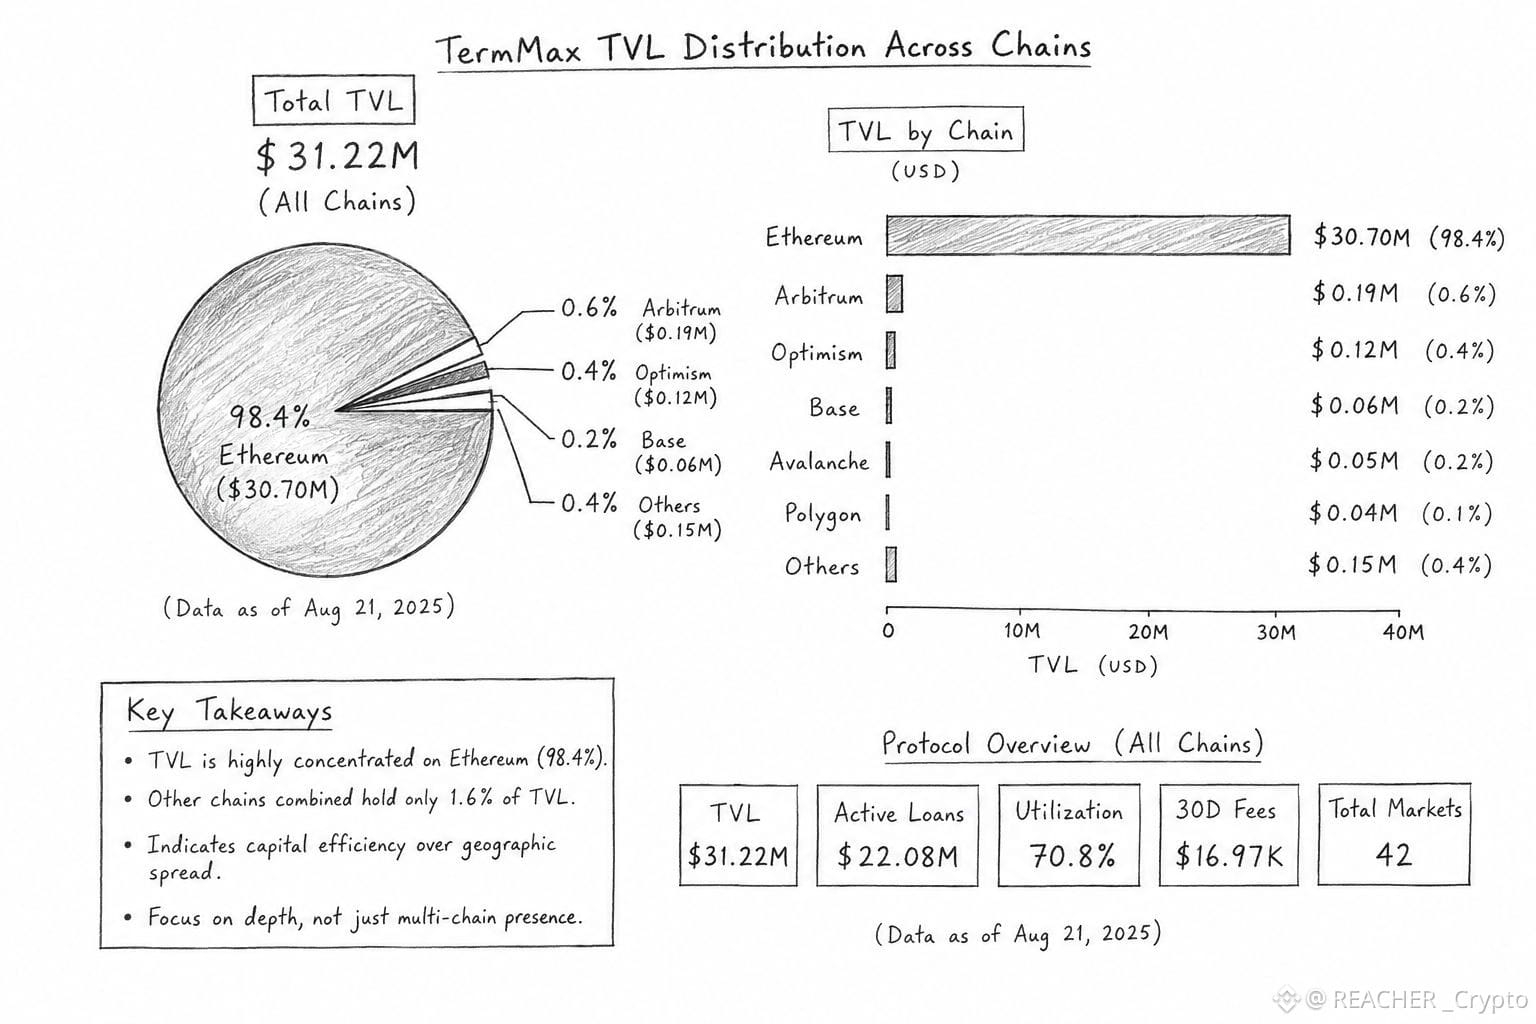
2
2
146
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
BitcoinFiveWeeklyLosses
12,631 views
404 Discussing
Bitcoin News | Bitcoin Slides for Five Straight Weeks as AI Stock Rout Spills Into Crypto
Binance News
·8 Likes
·9.6k views
AIChipSlumpNasdaq
6,536 views
223 Discussing
NvidiaInvestigatesAfterHuang’sAffairApology
4,667 views
113 Discussing