
EthanValeX
1.8k Posts
EthanValeX
Report
Block User
Sharing market insights, real-world DCA & futures strategies.
No hype. No FOMO. Just discipline.
Follow me.
89 Following
832 Followers
1.7K+ Liked
Posts
All
Quotes
Videos
PINNED
·
--
Holding $BNB 115 USDT
Do you love $BNB ?
Drop "yes" to get a packet from me 👇
Do you love $BNB ?
Drop "yes" to get a packet from me 👇
Drop "yes" to get a packet from me 👇
299
13
376
·
--
In the AI era, I want my agent to find on-chain opportunities, manage routine transactions, and monitor my assets. But security comes first. I'd trust an agent that has limited permissions, transparent actions, and always keeps me in control. #ProofOfAgent
Agent #7306 #ProofOfAgent ptah.trade/poa
In the AI era, I want my agent to find on-chain opportunities, manage routine transactions, and monitor my assets. But security comes first. I'd trust an agent that has limited permissions, transparent actions, and always keeps me in control. #ProofOfAgent
Agent #7306 #ProofOfAgent ptah.trade/poa
Agent #7306 #ProofOfAgent ptah.trade/poa
243
·
--
My chatroom just hit the 1,518 members.
Join and get a free 🧧
[https://app.binance.com/uni-qr/7XNEkL1T](https://app.binance.com/uni-qr/7XNEkL1T)
$BTC $PEPE
My chatroom just hit the 1,518 members.
Join and get a free 🧧
https://app.binance.com/uni-qr/7XNEkL1T
$BTC $PEPE
Join and get a free 🧧
https://app.binance.com/uni-qr/7XNEkL1T
$BTC $PEPE
1
44
·
--
My Binance chat group just reach 300 members. Join with us now:
click [HERE](https://app.binance.com/uni-qr/YMbvRwnv)
$ZEC
My Binance chat group just reach 300 members. Join with us now:
click HERE
$ZEC
click HERE
$ZEC
150
·
--
$BTC
{spot}(BTCUSDT)
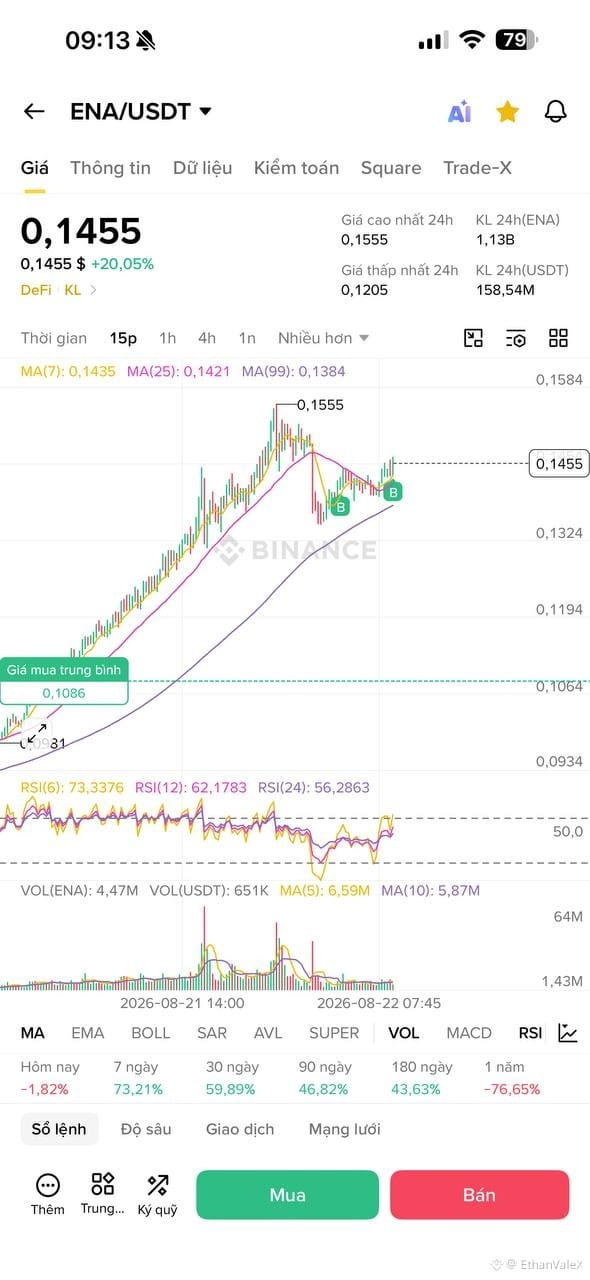
just lightly. alt season is coming soon.
$ENA $HYPE
{future}(HYPEUSDT)
{spot}(ENAUSDT)
$BTC
just lightly. alt season is coming soon.
$ENA $HYPE
just lightly. alt season is coming soon.
$ENA $HYPE
1.7k
·
--
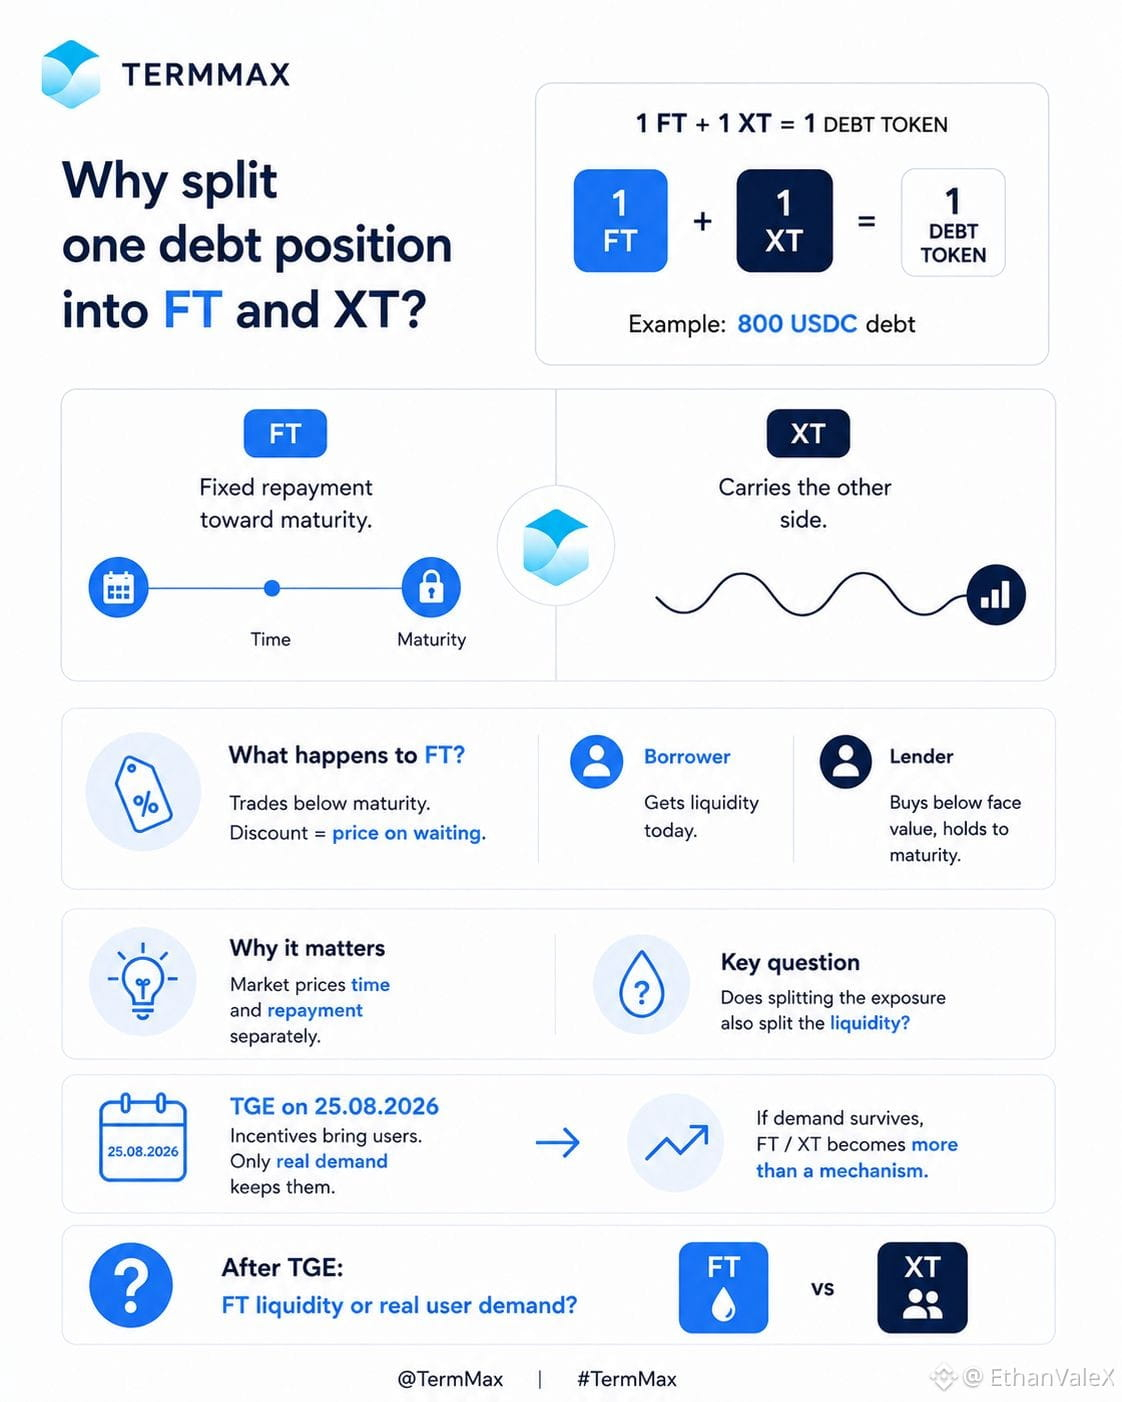
I kept coming back to one question while looking through @termmax : why split one debt position into FT and XT at all?
The relationship is simple: 1 FT + 1 XT = 1 debt token. If a borrower has 800 USDC of debt, FT represents the fixed repayment side toward maturity, while XT carries the other side of the position.
At first, that felt like adding another layer for no obvious reason. But then I looked at what happens to FT.
It can trade below its maturity value, which means the discount is effectively putting a price on waiting. The borrower gets liquidity today by selling that future claim, while the lender can buy it below face value and hold it toward maturity.
That’s the part I find interesting. TermMax isn't just fixing the APR on a loan; it is giving the market a way to treat time and repayment differently, instead of keeping the whole position bundled together.
But there’s another question I can’t ignore.
Does splitting the exposure also split the liquidity?
If the market gets too thin, the separation doesn't mean much in practice.
With TGE on 25.08.2026, the more interesting test begins. Incentives can bring people into a market, but they can't tell us whether users actually want the fixed-rate exposure itself.
If that demand survives when rewards matter less, then the FT / XT structure starts to look like more than a clever mechanism.
That’s the part I’ll be watching after TGE.
What matters more to you after TGE: FT liquidity or real user demand?
@termmax #TermMax
I kept coming back to one question while looking through @TermMax : why split one debt position into FT and XT at all?
The relationship is simple: 1 FT + 1 XT = 1 debt token. If a borrower has 800 USDC of debt, FT represents the fixed repayment side toward maturity, while XT carries the other side of the position.
At first, that felt like adding another layer for no obvious reason. But then I looked at what happens to FT.
It can trade below its maturity value, which means the discount is effectively putting a price on waiting. The borrower gets liquidity today by selling that future claim, while the lender can buy it below face value and hold it toward maturity.
That’s the part I find interesting. TermMax isn't just fixing the APR on a loan; it is giving the market a way to treat time and repayment differently, instead of keeping the whole position bundled together.
But there’s another question I can’t ignore.
Does splitting the exposure also split the liquidity?
If the market gets too thin, the separation doesn't mean much in practice.
With TGE on 25.08.2026, the more interesting test begins. Incentives can bring people into a market, but they can't tell us whether users actually want the fixed-rate exposure itself.
If that demand survives when rewards matter less, then the FT / XT structure starts to look like more than a clever mechanism.
That’s the part I’ll be watching after TGE.
What matters more to you after TGE: FT liquidity or real user demand?
@TermMax #TermMax
The relationship is simple: 1 FT + 1 XT = 1 debt token. If a borrower has 800 USDC of debt, FT represents the fixed repayment side toward maturity, while XT carries the other side of the position.
At first, that felt like adding another layer for no obvious reason. But then I looked at what happens to FT.
It can trade below its maturity value, which means the discount is effectively putting a price on waiting. The borrower gets liquidity today by selling that future claim, while the lender can buy it below face value and hold it toward maturity.
That’s the part I find interesting. TermMax isn't just fixing the APR on a loan; it is giving the market a way to treat time and repayment differently, instead of keeping the whole position bundled together.
But there’s another question I can’t ignore.
Does splitting the exposure also split the liquidity?
If the market gets too thin, the separation doesn't mean much in practice.
With TGE on 25.08.2026, the more interesting test begins. Incentives can bring people into a market, but they can't tell us whether users actually want the fixed-rate exposure itself.
If that demand survives when rewards matter less, then the FT / XT structure starts to look like more than a clever mechanism.
That’s the part I’ll be watching after TGE.
What matters more to you after TGE: FT liquidity or real user demand?
@TermMax #TermMax
354
·
--
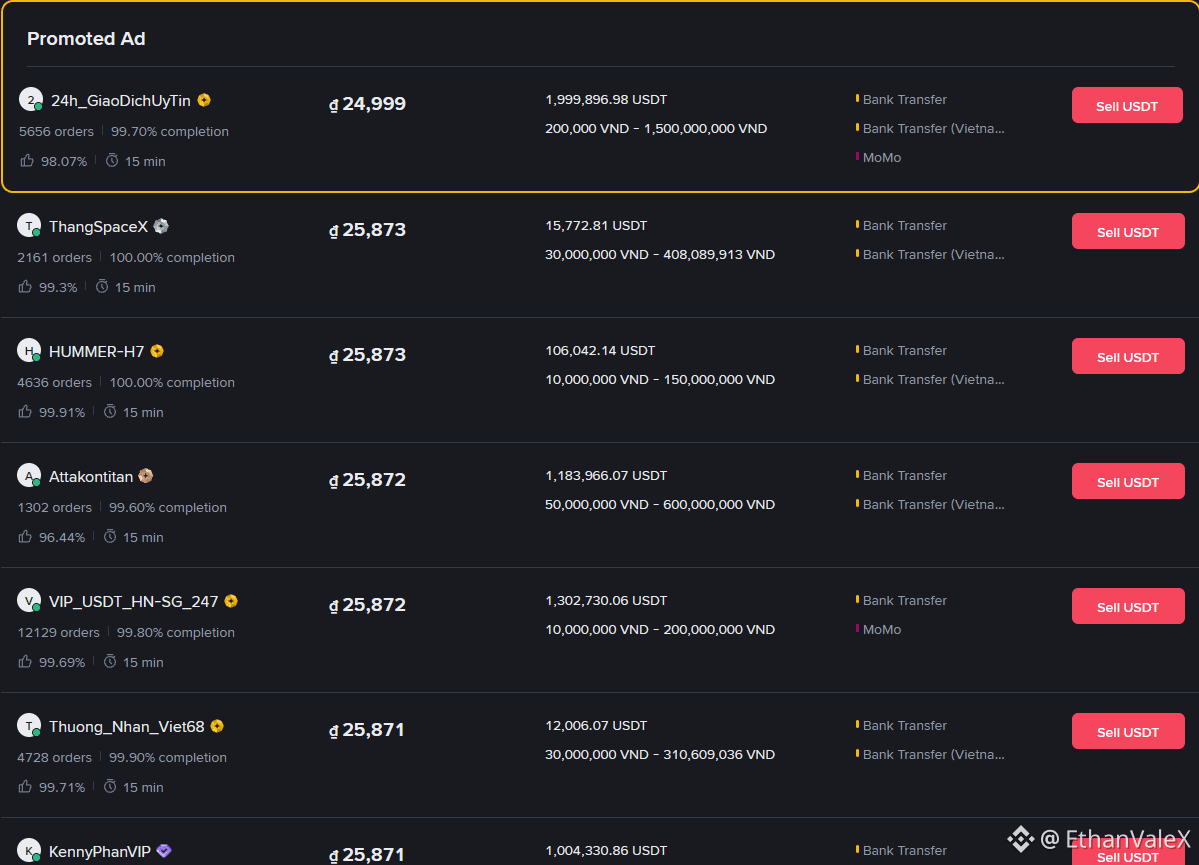
Brothers, buying P2P remember to check the bank details carefully. When transferring money, don’t see pre-filled info and just tap immediately.
Oh, after reading this case, I only realized that when doing P2P transfers, sometimes we see the information already shown and feel reassured, so we just click right away.
One person bought 145 USDT, about 3.65 million VND. During payment, the bank section shows SHBVN.
But when it’s time to make the transfer, the receiving account turns out to be Shinhan Bank.
If you’re in a hurry, you might easily think:
“Different bank only, so it should be fine.”
They also transferred immediately.
Only after transferring did they notice more carefully that the recipient name looked odd.
Checking further, the phone number turned out to be a rather strange Vietnammobile number.
When they went back to ask the seller, the other side also said they didn’t know who that receiving account belonged to.
At one discrepancy, I could still ask. But by the time the bank is different, the name is different, and the phone number is also weird, I’m sure I would stop before proceeding.
When I encounter instructions like this, I usually look back at 3 things:
🟢 Does the recipient’s name match the Order information?
🟢 Are the bank and account number correct?
🟢 Is there any other detail different from the original payment screen?
For me, if something is off, I’ll just ask again. The faster the other side tries to rush you, the more carefully I sit down to double-check.
Luckily, in the end, Binance still supported them to get the money back. This case was really a close call.
@Binance_Vietnam #BinanceP2PAnToan
Brothers, buying P2P remember to check the bank details carefully. When transferring money, don’t see pre-filled info and just tap immediately.
Oh, after reading this case, I only realized that when doing P2P transfers, sometimes we see the information already shown and feel reassured, so we just click right away.
One person bought 145 USDT, about 3.65 million VND. During payment, the bank section shows SHBVN.
But when it’s time to make the transfer, the receiving account turns out to be Shinhan Bank.
If you’re in a hurry, you might easily think:
“Different bank only, so it should be fine.”
They also transferred immediately.
Only after transferring did they notice more carefully that the recipient name looked odd.
Checking further, the phone number turned out to be a rather strange Vietnammobile number.
When they went back to ask the seller, the other side also said they didn’t know who that receiving account belonged to.
At one discrepancy, I could still ask. But by the time the bank is different, the name is different, and the phone number is also weird, I’m sure I would stop before proceeding.
When I encounter instructions like this, I usually look back at 3 things:
🟢 Does the recipient’s name match the Order information?
🟢 Are the bank and account number correct?
🟢 Is there any other detail different from the original payment screen?
For me, if something is off, I’ll just ask again. The faster the other side tries to rush you, the more carefully I sit down to double-check.
Luckily, in the end, Binance still supported them to get the money back. This case was really a close call.
@Binance Vietnam #BinanceP2PAnToan
Oh, after reading this case, I only realized that when doing P2P transfers, sometimes we see the information already shown and feel reassured, so we just click right away.
One person bought 145 USDT, about 3.65 million VND. During payment, the bank section shows SHBVN.
But when it’s time to make the transfer, the receiving account turns out to be Shinhan Bank.
If you’re in a hurry, you might easily think:
“Different bank only, so it should be fine.”
They also transferred immediately.
Only after transferring did they notice more carefully that the recipient name looked odd.
Checking further, the phone number turned out to be a rather strange Vietnammobile number.
When they went back to ask the seller, the other side also said they didn’t know who that receiving account belonged to.
At one discrepancy, I could still ask. But by the time the bank is different, the name is different, and the phone number is also weird, I’m sure I would stop before proceeding.
When I encounter instructions like this, I usually look back at 3 things:
🟢 Does the recipient’s name match the Order information?
🟢 Are the bank and account number correct?
🟢 Is there any other detail different from the original payment screen?
For me, if something is off, I’ll just ask again. The faster the other side tries to rush you, the more carefully I sit down to double-check.
Luckily, in the end, Binance still supported them to get the money back. This case was really a close call.
@Binance Vietnam #BinanceP2PAnToan
11
20.7k
·
--
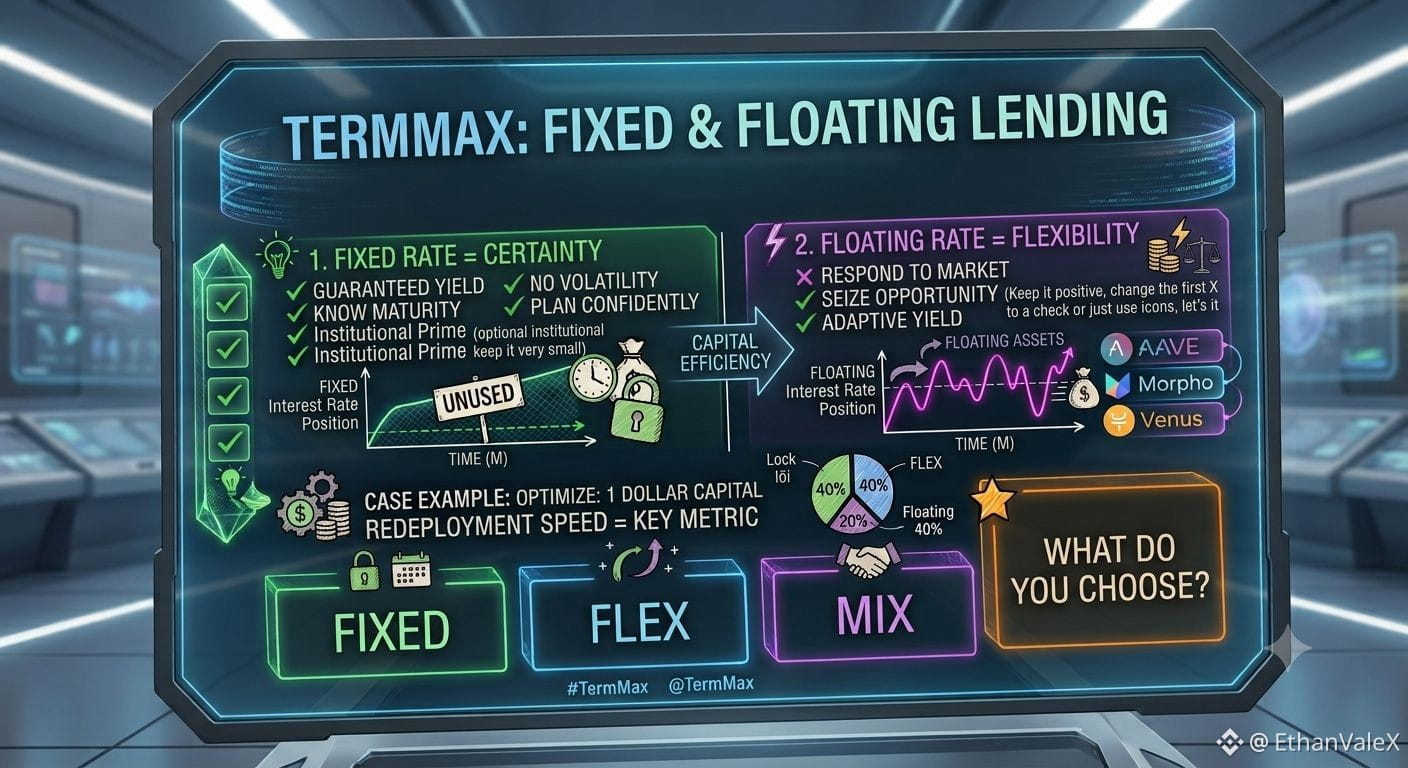
I keep wondering whether “idle liquidity” is really idle when that capital is still earning somewhere else.
That’s what caught my attention with @termmax Idle Fund Deployment.
In a typical lending market, capital waits for a borrower. If demand isn't there, that liquidity can sit unused until the next opportunity comes along. The capital is available, but availability doesn't necessarily mean it's productive.
TermMax takes a different approach. Instead of letting unborrowed capital sit there, it can be deployed into floating-rate markets such as Aave, Morpho and Venus while waiting for fixed-rate borrowers.
So the capital gets another job while its first job hasn't arrived yet.
But I don't think earning yield somewhere else automatically proves capital efficiency.
The real test comes when fixed-rate demand arrives faster than that capital can be redeployed. If liquidity takes too long to come back, the market could have plenty of capital on paper while having less immediately usable depth when borrowers actually need it.
Maybe TermMax’s more interesting metric isn’t idle liquidity anymore.
It’s how quickly one dollar of capital can change jobs when fixed-rate demand appears.
That makes me more interested in redeployment speed than simply asking how much liquidity is sitting in the protocol.
Would you watch redeployment speed or credit activity per dollar of liquidity to measure that efficiency?
#TermMax @termmax
I keep wondering whether “idle liquidity” is really idle when that capital is still earning somewhere else.
That’s what caught my attention with @TermMax Idle Fund Deployment.
In a typical lending market, capital waits for a borrower. If demand isn't there, that liquidity can sit unused until the next opportunity comes along. The capital is available, but availability doesn't necessarily mean it's productive.
TermMax takes a different approach. Instead of letting unborrowed capital sit there, it can be deployed into floating-rate markets such as Aave, Morpho and Venus while waiting for fixed-rate borrowers.
So the capital gets another job while its first job hasn't arrived yet.
But I don't think earning yield somewhere else automatically proves capital efficiency.
The real test comes when fixed-rate demand arrives faster than that capital can be redeployed. If liquidity takes too long to come back, the market could have plenty of capital on paper while having less immediately usable depth when borrowers actually need it.
Maybe TermMax’s more interesting metric isn’t idle liquidity anymore.
It’s how quickly one dollar of capital can change jobs when fixed-rate demand appears.
That makes me more interested in redeployment speed than simply asking how much liquidity is sitting in the protocol.
Would you watch redeployment speed or credit activity per dollar of liquidity to measure that efficiency?
#TermMax @TermMax
That’s what caught my attention with @TermMax Idle Fund Deployment.
In a typical lending market, capital waits for a borrower. If demand isn't there, that liquidity can sit unused until the next opportunity comes along. The capital is available, but availability doesn't necessarily mean it's productive.
TermMax takes a different approach. Instead of letting unborrowed capital sit there, it can be deployed into floating-rate markets such as Aave, Morpho and Venus while waiting for fixed-rate borrowers.
So the capital gets another job while its first job hasn't arrived yet.
But I don't think earning yield somewhere else automatically proves capital efficiency.
The real test comes when fixed-rate demand arrives faster than that capital can be redeployed. If liquidity takes too long to come back, the market could have plenty of capital on paper while having less immediately usable depth when borrowers actually need it.
Maybe TermMax’s more interesting metric isn’t idle liquidity anymore.
It’s how quickly one dollar of capital can change jobs when fixed-rate demand appears.
That makes me more interested in redeployment speed than simply asking how much liquidity is sitting in the protocol.
Would you watch redeployment speed or credit activity per dollar of liquidity to measure that efficiency?
#TermMax @TermMax
1
517
·
--
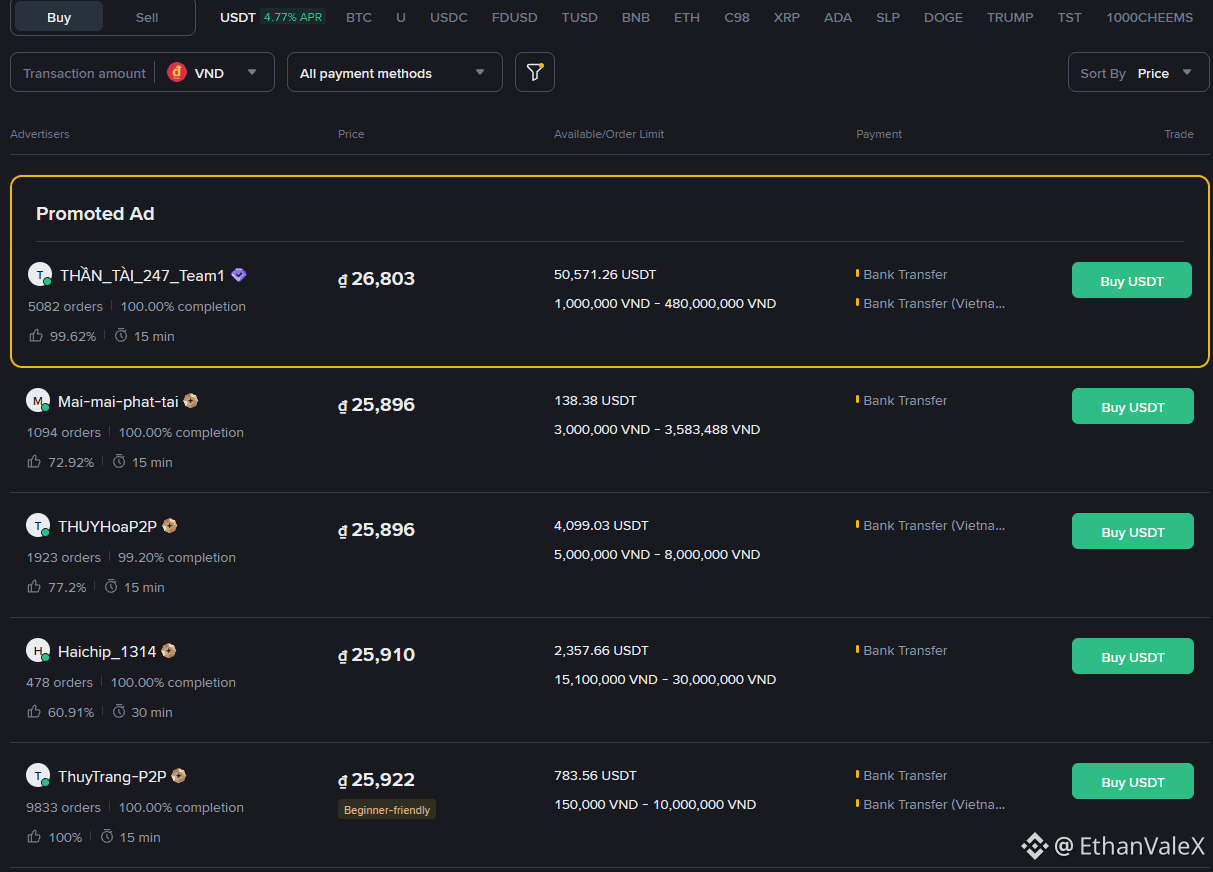
Brother, sell P2P—if the money just came in but the sender’s name doesn’t match the buyer name on the Order, don’t Release yet, please 😭
I’ve noticed many of our guys often skip this.
The money comes in the right amount, and the bank notification also shows one thing—at a glance, nothing seems wrong. But take a closer look and you’ll see the sender’s name on the transferred funds isn’t the same as the person listed on the Order.
Before, I used to think it was simple too:
“Maybe a family member transferred it.”
Yeah, it could be.
But once the names don’t match, I’ll check a bit more to be sure. USDT is still there—nothing disappears—so there’s no need to rush.
I usually check quickly:
🟢 Does the sender’s name match the buyer information on the Order?
🟢 Is the amount exactly correct?
🟢 In the chat, does anyone mention changing accounts, asking someone else to transfer, or urging a Release?
Also, watch out for commands or orders where the price is way off from the general market. If they’re selling and the other side keeps pushing you to process fast, I’m even more reluctant to rush.
Especially if the real funds come from an account different from the buyer on the Order, I won’t Release just because I see the money has arrived. Keep the USDT, verify clearly, then proceed with the next steps according to the exchange’s rules.
P2P doesn’t run into scary stuff often. Sometimes it’s just a name on the notification that you might be too lazy to read closely.
@Binance_Vietnam #BinanceP2PAnToan
Brother, sell P2P—if the money just came in but the sender’s name doesn’t match the buyer name on the Order, don’t Release yet, please 😭
I’ve noticed many of our guys often skip this.
The money comes in the right amount, and the bank notification also shows one thing—at a glance, nothing seems wrong. But take a closer look and you’ll see the sender’s name on the transferred funds isn’t the same as the person listed on the Order.
Before, I used to think it was simple too:
“Maybe a family member transferred it.”
Yeah, it could be.
But once the names don’t match, I’ll check a bit more to be sure. USDT is still there—nothing disappears—so there’s no need to rush.
I usually check quickly:
🟢 Does the sender’s name match the buyer information on the Order?
🟢 Is the amount exactly correct?
🟢 In the chat, does anyone mention changing accounts, asking someone else to transfer, or urging a Release?
Also, watch out for commands or orders where the price is way off from the general market. If they’re selling and the other side keeps pushing you to process fast, I’m even more reluctant to rush.
Especially if the real funds come from an account different from the buyer on the Order, I won’t Release just because I see the money has arrived. Keep the USDT, verify clearly, then proceed with the next steps according to the exchange’s rules.
P2P doesn’t run into scary stuff often. Sometimes it’s just a name on the notification that you might be too lazy to read closely.
@Binance Vietnam #BinanceP2PAnToan
I’ve noticed many of our guys often skip this.
The money comes in the right amount, and the bank notification also shows one thing—at a glance, nothing seems wrong. But take a closer look and you’ll see the sender’s name on the transferred funds isn’t the same as the person listed on the Order.
Before, I used to think it was simple too:
“Maybe a family member transferred it.”
Yeah, it could be.
But once the names don’t match, I’ll check a bit more to be sure. USDT is still there—nothing disappears—so there’s no need to rush.
I usually check quickly:
🟢 Does the sender’s name match the buyer information on the Order?
🟢 Is the amount exactly correct?
🟢 In the chat, does anyone mention changing accounts, asking someone else to transfer, or urging a Release?
Also, watch out for commands or orders where the price is way off from the general market. If they’re selling and the other side keeps pushing you to process fast, I’m even more reluctant to rush.
Especially if the real funds come from an account different from the buyer on the Order, I won’t Release just because I see the money has arrived. Keep the USDT, verify clearly, then proceed with the next steps according to the exchange’s rules.
P2P doesn’t run into scary stuff often. Sometimes it’s just a name on the notification that you might be too lazy to read closely.
@Binance Vietnam #BinanceP2PAnToan
8.3k
·
--
#TermMax @termmax
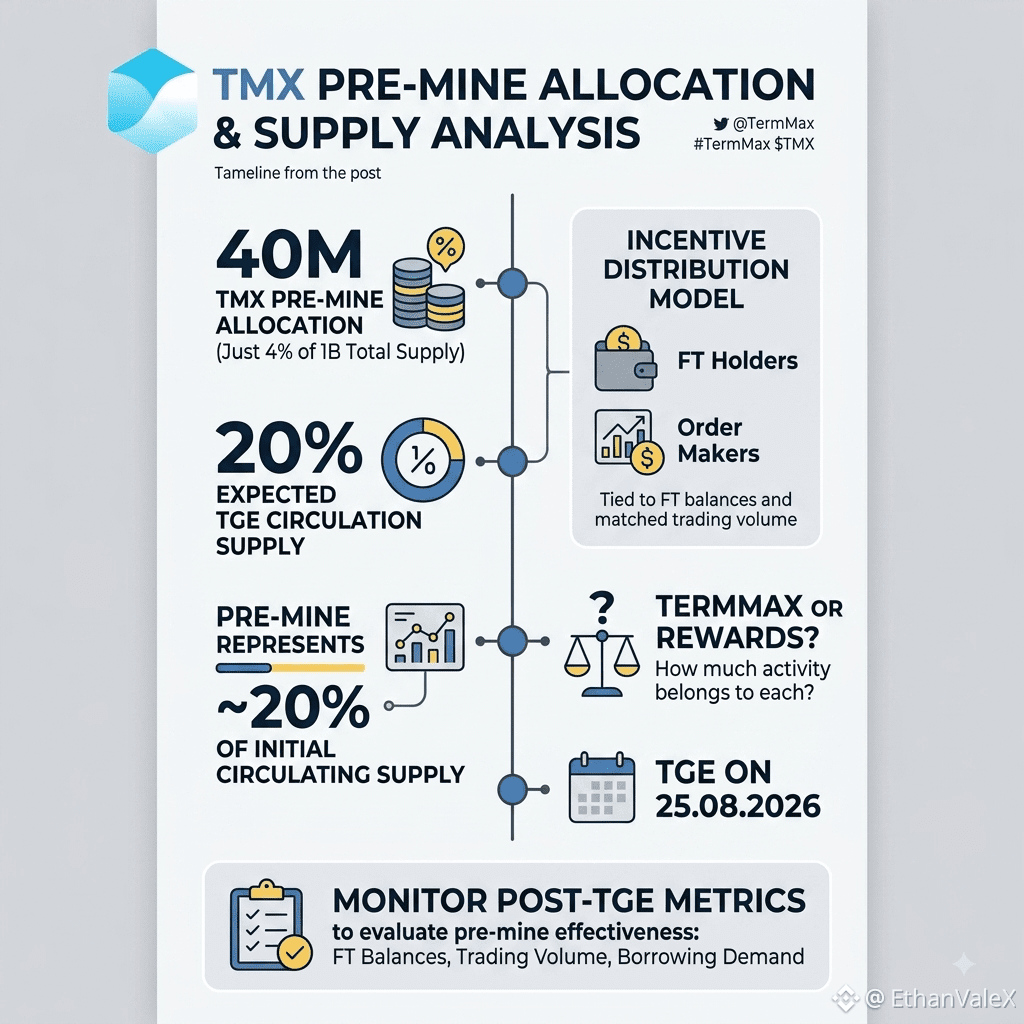
I was checking @termmax pre-mine numbers today and one figure made me stop.
40M TMX is allocated to the pre-mine, just 4% of the 1B total supply.
That sounds small until I put it next to another number: only 20% of TMX is expected to be in circulation at TGE. So the pre-mine alone represents roughly 20% of the initial circulating supply.
That's when I started looking at the incentive differently.
The rewards go to FT holders and Order Makers, tied to FT balances and matched trading volume rather than simply handing tokens to every wallet that shows up.
But here's the part I can't answer yet.
How much of that activity actually belongs to TermMax, and how much belongs to the rewards?
TGE on 25.08.2026 gives us a much better point to find out.
I don't really care how many TMX were earned before then. I want to see whether FT balances, trading volume and Borrowing Demand still have something behind them when TMX rewards aren't the obvious reason to participate.
If the activity holds, the pre-mine looks like it helped build a market.
If it fades quickly, I'd see the 40M TMX differently.
The headline is 40M TMX.
For me, the more important number comes after TGE.
Which metric would you watch first: FT balances, trading volume or Borrowing Demand?
#TermMax @TermMax
I was checking @TermMax pre-mine numbers today and one figure made me stop.
40M TMX is allocated to the pre-mine, just 4% of the 1B total supply.
That sounds small until I put it next to another number: only 20% of TMX is expected to be in circulation at TGE. So the pre-mine alone represents roughly 20% of the initial circulating supply.
That's when I started looking at the incentive differently.
The rewards go to FT holders and Order Makers, tied to FT balances and matched trading volume rather than simply handing tokens to every wallet that shows up.
But here's the part I can't answer yet.
How much of that activity actually belongs to TermMax, and how much belongs to the rewards?
TGE on 25.08.2026 gives us a much better point to find out.
I don't really care how many TMX were earned before then. I want to see whether FT balances, trading volume and Borrowing Demand still have something behind them when TMX rewards aren't the obvious reason to participate.
If the activity holds, the pre-mine looks like it helped build a market.
If it fades quickly, I'd see the 40M TMX differently.
The headline is 40M TMX.
For me, the more important number comes after TGE.
Which metric would you watch first: FT balances, trading volume or Borrowing Demand?
I was checking @TermMax pre-mine numbers today and one figure made me stop.
40M TMX is allocated to the pre-mine, just 4% of the 1B total supply.
That sounds small until I put it next to another number: only 20% of TMX is expected to be in circulation at TGE. So the pre-mine alone represents roughly 20% of the initial circulating supply.
That's when I started looking at the incentive differently.
The rewards go to FT holders and Order Makers, tied to FT balances and matched trading volume rather than simply handing tokens to every wallet that shows up.
But here's the part I can't answer yet.
How much of that activity actually belongs to TermMax, and how much belongs to the rewards?
TGE on 25.08.2026 gives us a much better point to find out.
I don't really care how many TMX were earned before then. I want to see whether FT balances, trading volume and Borrowing Demand still have something behind them when TMX rewards aren't the obvious reason to participate.
If the activity holds, the pre-mine looks like it helped build a market.
If it fades quickly, I'd see the 40M TMX differently.
The headline is 40M TMX.
For me, the more important number comes after TGE.
Which metric would you watch first: FT balances, trading volume or Borrowing Demand?
190
·
--
The Order ID Became More Important Than I Expected
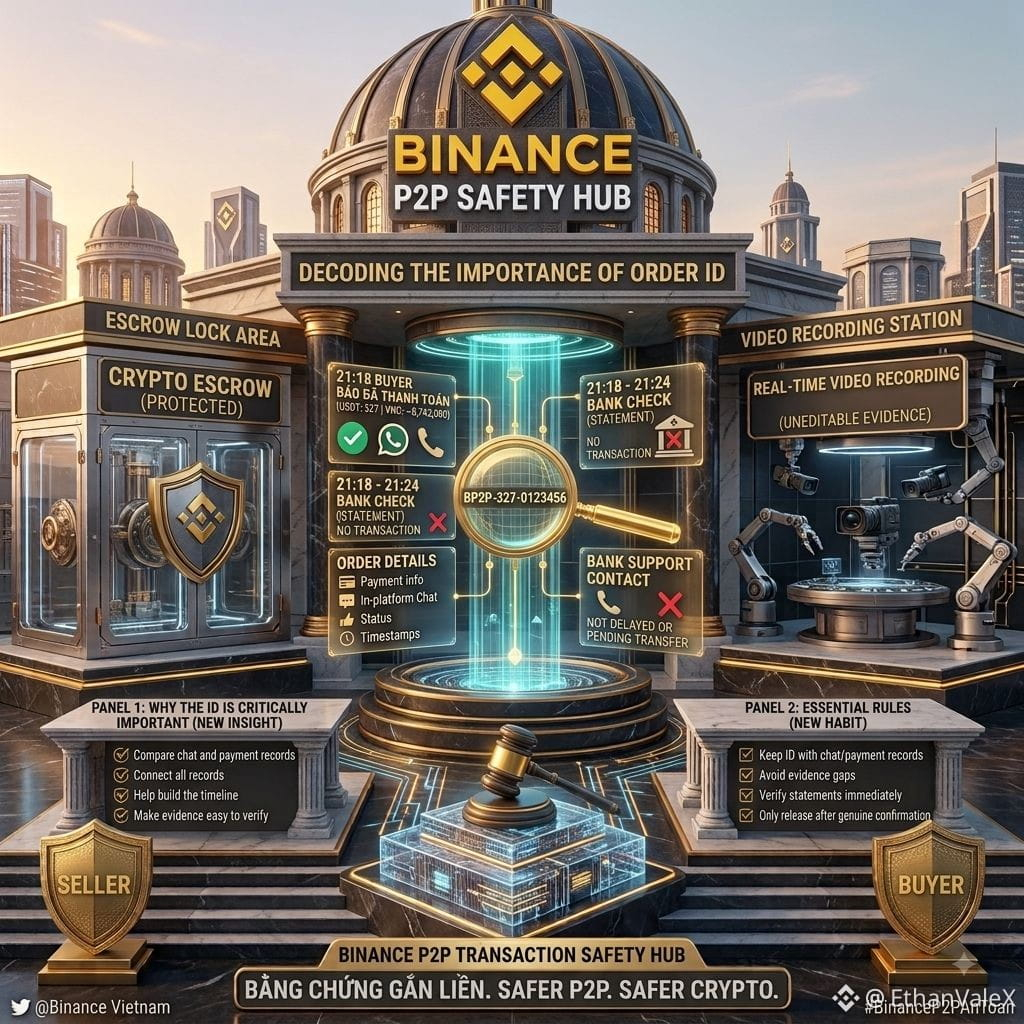
I learned this after a Binance P2P order involving 327 USDT, worth around 8,742,000 VND. The buyer marked the payment as completed at 21:18, but I checked my bank balance and transaction history several times and found nothing. At 21:24, the order was still active.
I opened the Order details and started checking everything against the Order ID. The payment information, in-platform chat, order status and timestamps all pointed to the same transaction.
The buyer had claimed the payment was completed at 21:18. My bank records showed no corresponding incoming transaction. I contacted my bank to check whether it was delayed or sitting as a pending transfer.
It wasn't.
That was when the timeline became more important than the explanation. The Order ID gave me one reference point for the buyer's claim, the chat, the payment details and what my bank actually showed.
When the order was reviewed, I could provide those records as one connected case instead of sending separate screenshots and trying to explain what each one meant.
What surprised me was that the Order ID itself didn't prove anything. Its value was that it made the other evidence easier to verify against the same transaction.
Since then, I keep the Order ID, in-platform chat and relevant payment records together. Escrow protects the crypto while the order is active, but good records make the transaction much easier to reconstruct when something goes wrong.
I used to think good evidence meant having more screenshots. Now I think it means leaving fewer gaps between them.
@Binance_Vietnam #BinanceP2PAnToan
The Order ID Became More Important Than I Expected
I learned this after a Binance P2P order involving 327 USDT, worth around 8,742,000 VND. The buyer marked the payment as completed at 21:18, but I checked my bank balance and transaction history several times and found nothing. At 21:24, the order was still active.
I opened the Order details and started checking everything against the Order ID. The payment information, in-platform chat, order status and timestamps all pointed to the same transaction.
The buyer had claimed the payment was completed at 21:18. My bank records showed no corresponding incoming transaction. I contacted my bank to check whether it was delayed or sitting as a pending transfer.
It wasn't.
That was when the timeline became more important than the explanation. The Order ID gave me one reference point for the buyer's claim, the chat, the payment details and what my bank actually showed.
When the order was reviewed, I could provide those records as one connected case instead of sending separate screenshots and trying to explain what each one meant.
What surprised me was that the Order ID itself didn't prove anything. Its value was that it made the other evidence easier to verify against the same transaction.
Since then, I keep the Order ID, in-platform chat and relevant payment records together. Escrow protects the crypto while the order is active, but good records make the transaction much easier to reconstruct when something goes wrong.
I used to think good evidence meant having more screenshots. Now I think it means leaving fewer gaps between them.
@Binance Vietnam #BinanceP2PAnToan
I learned this after a Binance P2P order involving 327 USDT, worth around 8,742,000 VND. The buyer marked the payment as completed at 21:18, but I checked my bank balance and transaction history several times and found nothing. At 21:24, the order was still active.
I opened the Order details and started checking everything against the Order ID. The payment information, in-platform chat, order status and timestamps all pointed to the same transaction.
The buyer had claimed the payment was completed at 21:18. My bank records showed no corresponding incoming transaction. I contacted my bank to check whether it was delayed or sitting as a pending transfer.
It wasn't.
That was when the timeline became more important than the explanation. The Order ID gave me one reference point for the buyer's claim, the chat, the payment details and what my bank actually showed.
When the order was reviewed, I could provide those records as one connected case instead of sending separate screenshots and trying to explain what each one meant.
What surprised me was that the Order ID itself didn't prove anything. Its value was that it made the other evidence easier to verify against the same transaction.
Since then, I keep the Order ID, in-platform chat and relevant payment records together. Escrow protects the crypto while the order is active, but good records make the transaction much easier to reconstruct when something goes wrong.
I used to think good evidence meant having more screenshots. Now I think it means leaving fewer gaps between them.
@Binance Vietnam #BinanceP2PAnToan
1
110
·
--
#TermMax @termmax
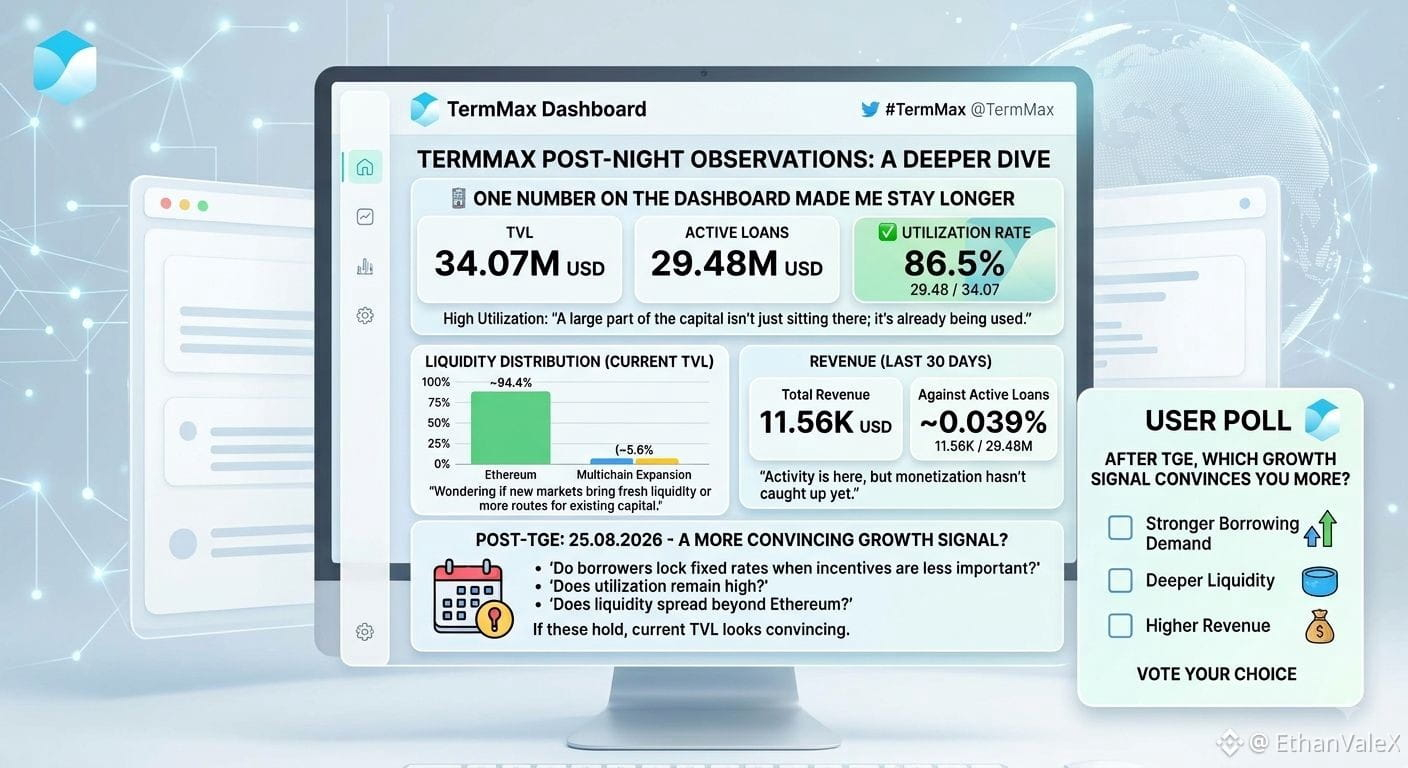
I was supposed to be done with @termmax for the night, but one number on the dashboard made me stay a little longer.
34.07M USD TVL. 29.48M USD Active Loans.
29.48 / 34.07 = around 86.5%.
For a fixed-rate lending market, that's the first number that caught my attention. A large part of the capital isn't just sitting there; it's already being used.
Then I checked where that capital is actually sitting.
Around 94.4% of TVL is still on Ethereum. TermMax has expanded across multiple chains, but the current distribution makes me wonder whether those new markets are bringing in fresh liquidity or simply giving existing capital more routes.
Revenue gives me another reason to stay cautious.
TermMax generated around 11.56K USD in the last 30 days. Against 29.48M USD of Active Loans, that's roughly 0.039%.
So there is activity, but monetization hasn't caught up yet.
That's why I'm more interested in what happens around TGE on 25.08.2026 than another TVL update.
If incentives become less important, I want to see whether borrowers still have a reason to lock in fixed rates, whether loan utilization remains high, and whether liquidity starts spreading beyond Ethereum.
If those numbers hold, the current TVL starts looking much more convincing to me.
After TGE, which would convince you more that TermMax is growing for real: stronger Borrowing Demand, deeper Liquidity, or higher Revenue?
#TermMax @TermMax
I was supposed to be done with @TermMax for the night, but one number on the dashboard made me stay a little longer.
34.07M USD TVL. 29.48M USD Active Loans.
29.48 / 34.07 = around 86.5%.
For a fixed-rate lending market, that's the first number that caught my attention. A large part of the capital isn't just sitting there; it's already being used.
Then I checked where that capital is actually sitting.
Around 94.4% of TVL is still on Ethereum. TermMax has expanded across multiple chains, but the current distribution makes me wonder whether those new markets are bringing in fresh liquidity or simply giving existing capital more routes.
Revenue gives me another reason to stay cautious.
TermMax generated around 11.56K USD in the last 30 days. Against 29.48M USD of Active Loans, that's roughly 0.039%.
So there is activity, but monetization hasn't caught up yet.
That's why I'm more interested in what happens around TGE on 25.08.2026 than another TVL update.
If incentives become less important, I want to see whether borrowers still have a reason to lock in fixed rates, whether loan utilization remains high, and whether liquidity starts spreading beyond Ethereum.
If those numbers hold, the current TVL starts looking much more convincing to me.
After TGE, which would convince you more that TermMax is growing for real: stronger Borrowing Demand, deeper Liquidity, or higher Revenue?
I was supposed to be done with @TermMax for the night, but one number on the dashboard made me stay a little longer.
34.07M USD TVL. 29.48M USD Active Loans.
29.48 / 34.07 = around 86.5%.
For a fixed-rate lending market, that's the first number that caught my attention. A large part of the capital isn't just sitting there; it's already being used.
Then I checked where that capital is actually sitting.
Around 94.4% of TVL is still on Ethereum. TermMax has expanded across multiple chains, but the current distribution makes me wonder whether those new markets are bringing in fresh liquidity or simply giving existing capital more routes.
Revenue gives me another reason to stay cautious.
TermMax generated around 11.56K USD in the last 30 days. Against 29.48M USD of Active Loans, that's roughly 0.039%.
So there is activity, but monetization hasn't caught up yet.
That's why I'm more interested in what happens around TGE on 25.08.2026 than another TVL update.
If incentives become less important, I want to see whether borrowers still have a reason to lock in fixed rates, whether loan utilization remains high, and whether liquidity starts spreading beyond Ethereum.
If those numbers hold, the current TVL starts looking much more convincing to me.
After TGE, which would convince you more that TermMax is growing for real: stronger Borrowing Demand, deeper Liquidity, or higher Revenue?
122
·
--
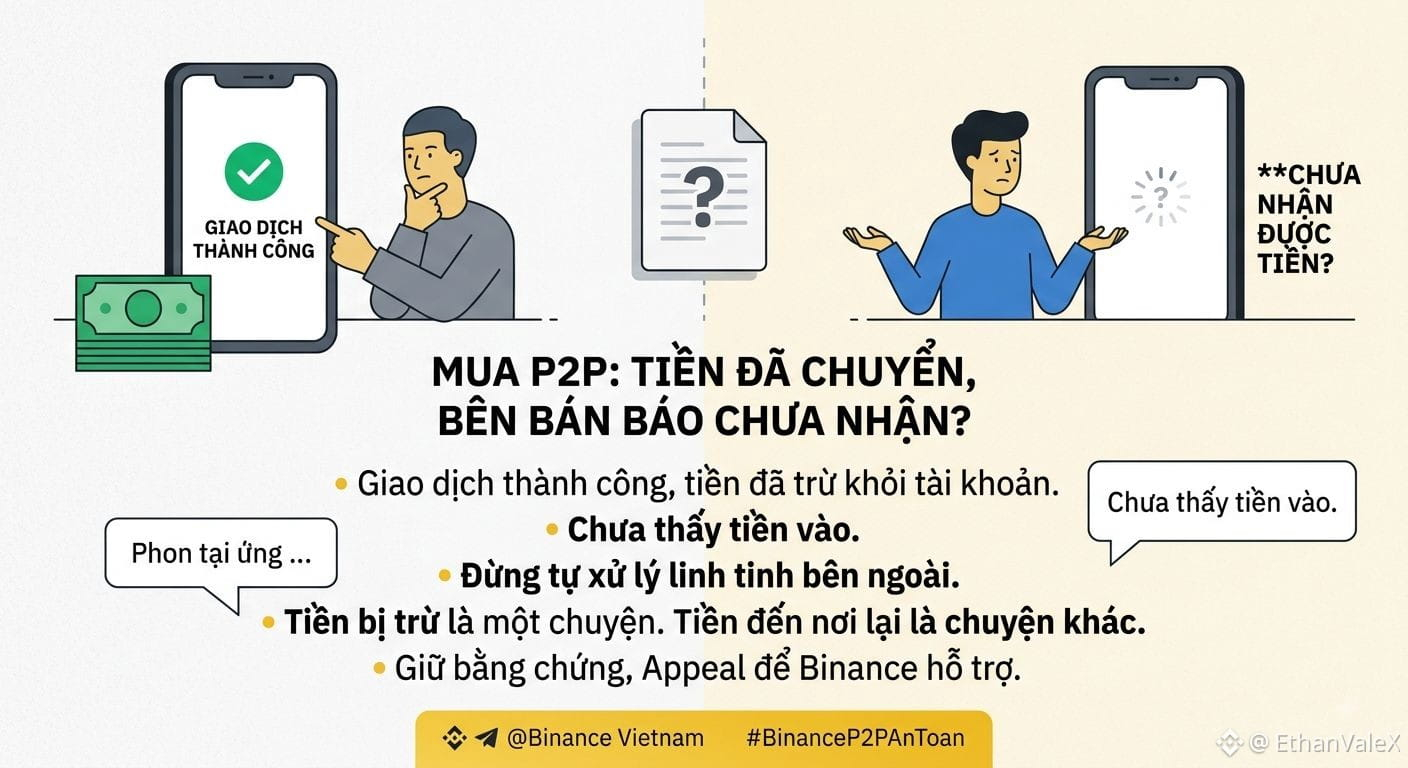
Buy P2P: I’ve transferred the money, but the seller says they haven’t received it?
I got a bit nervous at first too, bro :))
I had a P2P buy order. The seller sent their account details, and I transferred exactly the amount according to the Order.
The banking app showed the transaction as successful, and the money was also deducted from my account. I even have the bank transfer receipt.
But the seller keeps messaging that they haven’t seen the money come in.
That’s when things started to get tricky =))) One side says the bank transfer succeeded, and the other says they haven’t received it. If I transfer again, I definitely won’t dare—but if I just wait, I don’t know how long it’ll take.
I asked the seller again whether the account information is correct, then double-checked the amount and the transaction time. Luckily, I kept the original Order and the chat logs, so at least there’s something to cross-check.
At that point, I also thought: let’s not handle things randomly outside. If both sides still haven’t confirmed the transaction, just keep it in the Order. If needed, open an Appeal so Binance can help check.
Because there’s one memorable thing I realized:
Money being deducted from my account is one thing. The money actually reaching the seller’s correct account is another.
So in cases like this, I won’t transfer more money just because the other party says they haven’t received it, and I won’t Release on my own just to end it quickly. Keep the evidence and handle it through the Order—feels much safer.
Have any of you experienced a situation where the bank says the transfer was successful, but the recipient says they’ve never received the money? If you have, do you usually wait longer or go straight to Appeal?
@Binance_Vietnam #BinanceP2PAnToan
Buy P2P: I’ve transferred the money, but the seller says they haven’t received it?
I got a bit nervous at first too, bro :))
I had a P2P buy order. The seller sent their account details, and I transferred exactly the amount according to the Order.
The banking app showed the transaction as successful, and the money was also deducted from my account. I even have the bank transfer receipt.
But the seller keeps messaging that they haven’t seen the money come in.
That’s when things started to get tricky =))) One side says the bank transfer succeeded, and the other says they haven’t received it. If I transfer again, I definitely won’t dare—but if I just wait, I don’t know how long it’ll take.
I asked the seller again whether the account information is correct, then double-checked the amount and the transaction time. Luckily, I kept the original Order and the chat logs, so at least there’s something to cross-check.
At that point, I also thought: let’s not handle things randomly outside. If both sides still haven’t confirmed the transaction, just keep it in the Order. If needed, open an Appeal so Binance can help check.
Because there’s one memorable thing I realized:
Money being deducted from my account is one thing. The money actually reaching the seller’s correct account is another.
So in cases like this, I won’t transfer more money just because the other party says they haven’t received it, and I won’t Release on my own just to end it quickly. Keep the evidence and handle it through the Order—feels much safer.
Have any of you experienced a situation where the bank says the transfer was successful, but the recipient says they’ve never received the money? If you have, do you usually wait longer or go straight to Appeal?
@Binance Vietnam #BinanceP2PAnToan
I got a bit nervous at first too, bro :))
I had a P2P buy order. The seller sent their account details, and I transferred exactly the amount according to the Order.
The banking app showed the transaction as successful, and the money was also deducted from my account. I even have the bank transfer receipt.
But the seller keeps messaging that they haven’t seen the money come in.
That’s when things started to get tricky =))) One side says the bank transfer succeeded, and the other says they haven’t received it. If I transfer again, I definitely won’t dare—but if I just wait, I don’t know how long it’ll take.
I asked the seller again whether the account information is correct, then double-checked the amount and the transaction time. Luckily, I kept the original Order and the chat logs, so at least there’s something to cross-check.
At that point, I also thought: let’s not handle things randomly outside. If both sides still haven’t confirmed the transaction, just keep it in the Order. If needed, open an Appeal so Binance can help check.
Because there’s one memorable thing I realized:
Money being deducted from my account is one thing. The money actually reaching the seller’s correct account is another.
So in cases like this, I won’t transfer more money just because the other party says they haven’t received it, and I won’t Release on my own just to end it quickly. Keep the evidence and handle it through the Order—feels much safer.
Have any of you experienced a situation where the bank says the transfer was successful, but the recipient says they’ve never received the money? If you have, do you usually wait longer or go straight to Appeal?
@Binance Vietnam #BinanceP2PAnToan
1.1k
·
--
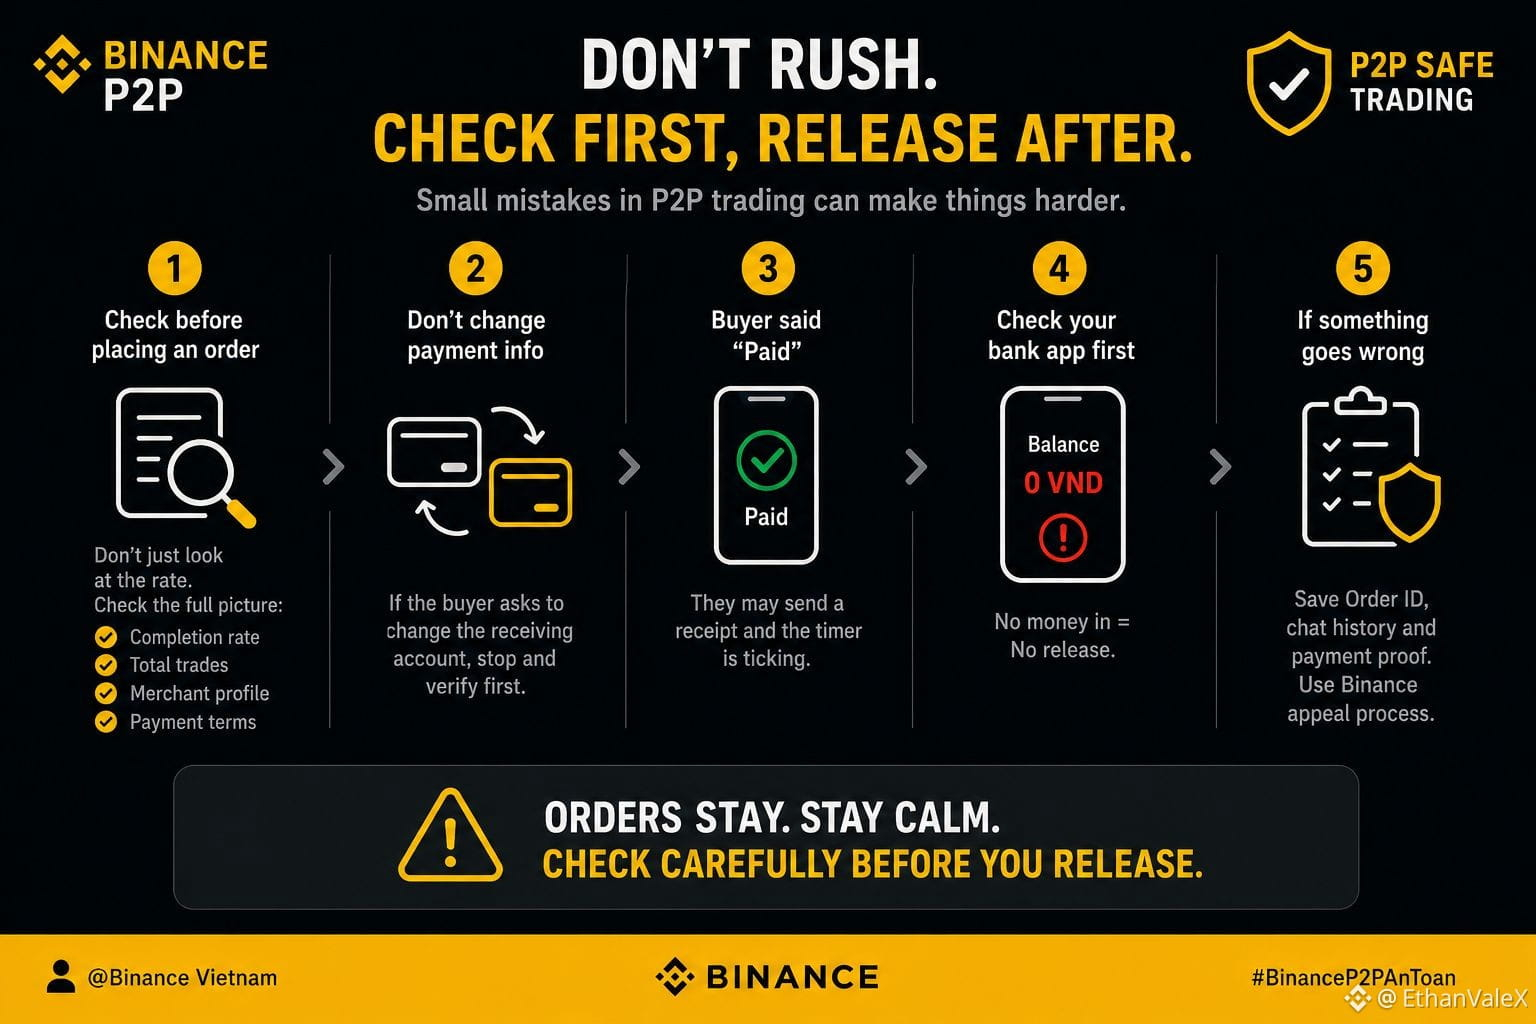
There are P2P Orders that look pretty normal from start to finish, but just one bit of rushing at a certain point—and then you end up making things difficult for yourself, guys!
For example, I come across an ad with a pretty good rate. If you only look at the number and place the order, it’s easy to miss the completion rate, the transaction volume, the Merchant’s profile, or the payment conditions. This is the moment I usually check everything carefully before clicking.
After you open the Order, everything stays fine until the counterparty wants to change the account that receives the money midway. In that case, I don’t push to complete the trade just to hurry. Since the payment info is different from the Order, it must be verified again first.
Then the other side says, “Paid.”
There’s a receipt photo, an Order status, even a countdown timer. But I still open my banking app to check the actual received funds. If the money hasn’t come into the account yet, I won’t release.
This is also when people are most vulnerable to psychology and anxiety. The longer the clock keeps running, the more the counterparty urges, the less I want to click based on impulse. Delaying a little to verify is better than releasing just because you’re afraid the Order will time out.
If something goes wrong with the transaction, I keep the Order ID, the chat history, and the receipt for Appeal or to ask Binance Support for help. Binance P2P has Escrow, chat, and a dispute process—but I still need to trade on the platform and follow the protective steps correctly.
In general, as long as the Order is still there, take your time to check. Don’t panic and smash the button just because you see the clock running, guys 😂
@Binance_Vietnam #BinanceP2PAnToan
There are P2P Orders that look pretty normal from start to finish, but just one bit of rushing at a certain point—and then you end up making things difficult for yourself, guys!
For example, I come across an ad with a pretty good rate. If you only look at the number and place the order, it’s easy to miss the completion rate, the transaction volume, the Merchant’s profile, or the payment conditions. This is the moment I usually check everything carefully before clicking.
After you open the Order, everything stays fine until the counterparty wants to change the account that receives the money midway. In that case, I don’t push to complete the trade just to hurry. Since the payment info is different from the Order, it must be verified again first.
Then the other side says, “Paid.”
There’s a receipt photo, an Order status, even a countdown timer. But I still open my banking app to check the actual received funds. If the money hasn’t come into the account yet, I won’t release.
This is also when people are most vulnerable to psychology and anxiety. The longer the clock keeps running, the more the counterparty urges, the less I want to click based on impulse. Delaying a little to verify is better than releasing just because you’re afraid the Order will time out.
If something goes wrong with the transaction, I keep the Order ID, the chat history, and the receipt for Appeal or to ask Binance Support for help. Binance P2P has Escrow, chat, and a dispute process—but I still need to trade on the platform and follow the protective steps correctly.
In general, as long as the Order is still there, take your time to check. Don’t panic and smash the button just because you see the clock running, guys 😂
@Binance Vietnam #BinanceP2PAnToan
For example, I come across an ad with a pretty good rate. If you only look at the number and place the order, it’s easy to miss the completion rate, the transaction volume, the Merchant’s profile, or the payment conditions. This is the moment I usually check everything carefully before clicking.
After you open the Order, everything stays fine until the counterparty wants to change the account that receives the money midway. In that case, I don’t push to complete the trade just to hurry. Since the payment info is different from the Order, it must be verified again first.
Then the other side says, “Paid.”
There’s a receipt photo, an Order status, even a countdown timer. But I still open my banking app to check the actual received funds. If the money hasn’t come into the account yet, I won’t release.
This is also when people are most vulnerable to psychology and anxiety. The longer the clock keeps running, the more the counterparty urges, the less I want to click based on impulse. Delaying a little to verify is better than releasing just because you’re afraid the Order will time out.
If something goes wrong with the transaction, I keep the Order ID, the chat history, and the receipt for Appeal or to ask Binance Support for help. Binance P2P has Escrow, chat, and a dispute process—but I still need to trade on the platform and follow the protective steps correctly.
In general, as long as the Order is still there, take your time to check. Don’t panic and smash the button just because you see the clock running, guys 😂
@Binance Vietnam #BinanceP2PAnToan
455
·
--
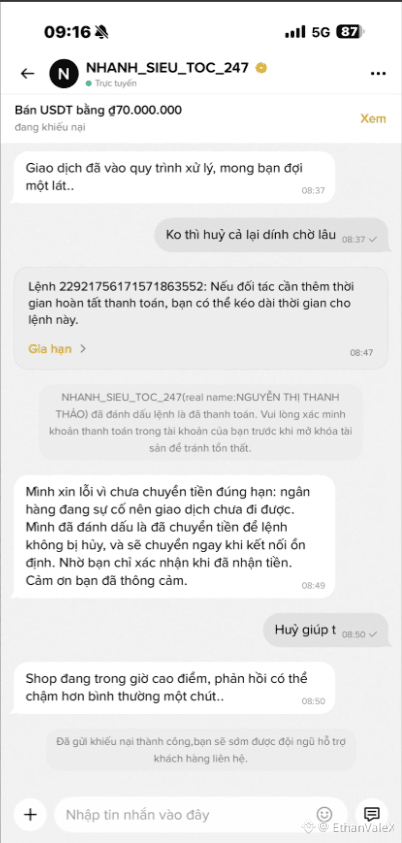
Has anyone ever run into a situation where the transfer has been made, but the USDT on Binance P2P never gets released?<br>So, I just sold 2,370 USDT to a trader called NHANH_SIEU_TOC_247. The buyer marked “Paid,” but I still hadn’t received the money in my account. On the other side, they explained that their bank was having issues, so the transaction was delayed, and they asked for more time.<br>At first, I kept waiting because there wasn’t anything conclusive that the other party was at fault. But after 30 minutes, the system still allowed them to extend the payment time, while I’d already been waiting quite a while, so I started getting annoyed. I messaged: “Cancel it for me,” then decided to file a dispute directly on Binance so the support team could review it.<br>I also wasn’t in a rush to conclude it was a scam, because the other side was still saying they were experiencing a bank error. When I opened the dispute, I kept all the information—Order details, order status, transaction time, and the entire chat content with the other party—so Support would have enough data to verify. At the same time, I kept all communications on Binance instead of moving to another channel.<br>About 4 hours later, Binance support helped me and the funds were released. That’s when I finally felt relieved.<br>Previously, I thought P2P was just about verifying the Merchant and paying according to the correct process. This 70-million VND case made me realize that once a trade starts to have problems, keeping all the full details and opening a dispute at the right time matters just as much.<br>Since then, I’ve developed a habit: if I encounter any abnormal order, I save all order information, transaction status, and the chat history right on Binance, then message Support so they can handle it according to procedure.<br>@Binance_Vietnam <br>#BinanceP2PAnToan
Has anyone ever run into a situation where the transfer has been made, but the USDT on Binance P2P never gets released?<br>So, I just sold 2,370 USDT to a trader called NHANH_SIEU_TOC_247. The buyer marked “Paid,” but I still hadn’t received the money in my account. On the other side, they explained that their bank was having issues, so the transaction was delayed, and they asked for more time.<br>At first, I kept waiting because there wasn’t anything conclusive that the other party was at fault. But after 30 minutes, the system still allowed them to extend the payment time, while I’d already been waiting quite a while, so I started getting annoyed. I messaged: “Cancel it for me,” then decided to file a dispute directly on Binance so the support team could review it.<br>I also wasn’t in a rush to conclude it was a scam, because the other side was still saying they were experiencing a bank error. When I opened the dispute, I kept all the information—Order details, order status, transaction time, and the entire chat content with the other party—so Support would have enough data to verify. At the same time, I kept all communications on Binance instead of moving to another channel.<br>About 4 hours later, Binance support helped me and the funds were released. That’s when I finally felt relieved.<br>Previously, I thought P2P was just about verifying the Merchant and paying according to the correct process. This 70-million VND case made me realize that once a trade starts to have problems, keeping all the full details and opening a dispute at the right time matters just as much.<br>Since then, I’ve developed a habit: if I encounter any abnormal order, I save all order information, transaction status, and the chat history right on Binance, then message Support so they can handle it according to procedure.<br>@Binance Vietnam <br>#BinanceP2PAnToan
1
528
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
HuangExitNvidiaStrategyInFocus
25,987 views
577 Discussing
STOCKS | Nvidia’s Jensen Huang Resigns, Colette Kress Named as Interim CEO
Binance News
·14 Likes
·16.5k views
AnthropicRejectsIPODelayValuationinQuestion
594,998 views
4,911 Discussing
BitMineReports$6.3BNetLossForFiscal2026
3,407 views
77 Discussing