
Web3投研江南雨
101 Posts
Web3投研江南雨
Report
Block User
前Web3投资机构研究员。目前全职做合约超短线交易,一天交易几十次。推特同名。

Top 30D Traders by Volume
Open Trade

BNB Holder
High-Frequency Trader
9.2 Years
3.2K+ Following
755 Followers
121 Liked
1 Badges
Posts
Portfolio
All
Quotes
PINNED
·
--
About the AI public chain tau.net (token name AGRS)
Tau
Tau is a universe built from your ideas, suggestions and knowledge. It is the first-ever decentralized blockchain social network capable of gaining consensus from its users and updating its own software in real time, allowing all users to control what the software does for them.
All in all, Tau can aggregate the ideas, suggestions and knowledge of various users, and upgrade its own code in real time, using logical artificial intelligence to bridge the gap between humans and machines.
Notice the difference? If you have recently learned about artificial intelligence and used ChatGPT, you will know that most AI uses machine learning, which relies on huge Internet data sets and makes it difficult to grasp the correct meaning and knowledge of interpersonal communication.
What about logic-based Al? It is more effective than machine learning in:
1. Explainability: Logic-based AI provides clear and transparent explanations of how decisions are made, which can be useful in certain applications, such as legal or medical diagnostics. In these application scenarios, accountability and explainability are important.
2. Predictability: Logic-based systems are deterministic, meaning that given the same input, they always produce the same output.
3. Efficiency: For simple tasks, logic-based AI can be faster than machine learning algorithms because they require no training to make decisions based on a small number of well-defined rules.
4. Adaptability: Logic-based AI can be easily modified and updated to adapt to new knowledge or environmental changes.
These advantages form Tau's moat. Artificial intelligence using logic has uniquely created a model of communication between people with machines as the mediator.
A team of PhDs and professors with expertise in artificial intelligence, logic and mathematics has been working on Tau since 2015. Founder and CEO Ohad Asor is a software developer and machine learning expert with a background in mathematics and experience at GE Healthcare.
About the AI public chain tau.net (token name AGRS)
Tau
Tau is a universe built from your ideas, suggestions and knowledge. It is the first-ever decentralized blockchain social network capable of gaining consensus from its users and updating its own software in real time, allowing all users to control what the software does for them.
All in all, Tau can aggregate the ideas, suggestions and knowledge of various users, and upgrade its own code in real time, using logical artificial intelligence to bridge the gap between humans and machines.
Notice the difference? If you have recently learned about artificial intelligence and used ChatGPT, you will know that most AI uses machine learning, which relies on huge Internet data sets and makes it difficult to grasp the correct meaning and knowledge of interpersonal communication.
What about logic-based Al? It is more effective than machine learning in:
1. Explainability: Logic-based AI provides clear and transparent explanations of how decisions are made, which can be useful in certain applications, such as legal or medical diagnostics. In these application scenarios, accountability and explainability are important.
2. Predictability: Logic-based systems are deterministic, meaning that given the same input, they always produce the same output.
3. Efficiency: For simple tasks, logic-based AI can be faster than machine learning algorithms because they require no training to make decisions based on a small number of well-defined rules.
4. Adaptability: Logic-based AI can be easily modified and updated to adapt to new knowledge or environmental changes.
These advantages form Tau's moat. Artificial intelligence using logic has uniquely created a model of communication between people with machines as the mediator.
A team of PhDs and professors with expertise in artificial intelligence, logic and mathematics has been working on Tau since 2015. Founder and CEO Ohad Asor is a software developer and machine learning expert with a background in mathematics and experience at GE Healthcare.
Tau
Tau is a universe built from your ideas, suggestions and knowledge. It is the first-ever decentralized blockchain social network capable of gaining consensus from its users and updating its own software in real time, allowing all users to control what the software does for them.
All in all, Tau can aggregate the ideas, suggestions and knowledge of various users, and upgrade its own code in real time, using logical artificial intelligence to bridge the gap between humans and machines.
Notice the difference? If you have recently learned about artificial intelligence and used ChatGPT, you will know that most AI uses machine learning, which relies on huge Internet data sets and makes it difficult to grasp the correct meaning and knowledge of interpersonal communication.
What about logic-based Al? It is more effective than machine learning in:
1. Explainability: Logic-based AI provides clear and transparent explanations of how decisions are made, which can be useful in certain applications, such as legal or medical diagnostics. In these application scenarios, accountability and explainability are important.
2. Predictability: Logic-based systems are deterministic, meaning that given the same input, they always produce the same output.
3. Efficiency: For simple tasks, logic-based AI can be faster than machine learning algorithms because they require no training to make decisions based on a small number of well-defined rules.
4. Adaptability: Logic-based AI can be easily modified and updated to adapt to new knowledge or environmental changes.
These advantages form Tau's moat. Artificial intelligence using logic has uniquely created a model of communication between people with machines as the mediator.
A team of PhDs and professors with expertise in artificial intelligence, logic and mathematics has been working on Tau since 2015. Founder and CEO Ohad Asor is a software developer and machine learning expert with a background in mathematics and experience at GE Healthcare.
5
153
·
--
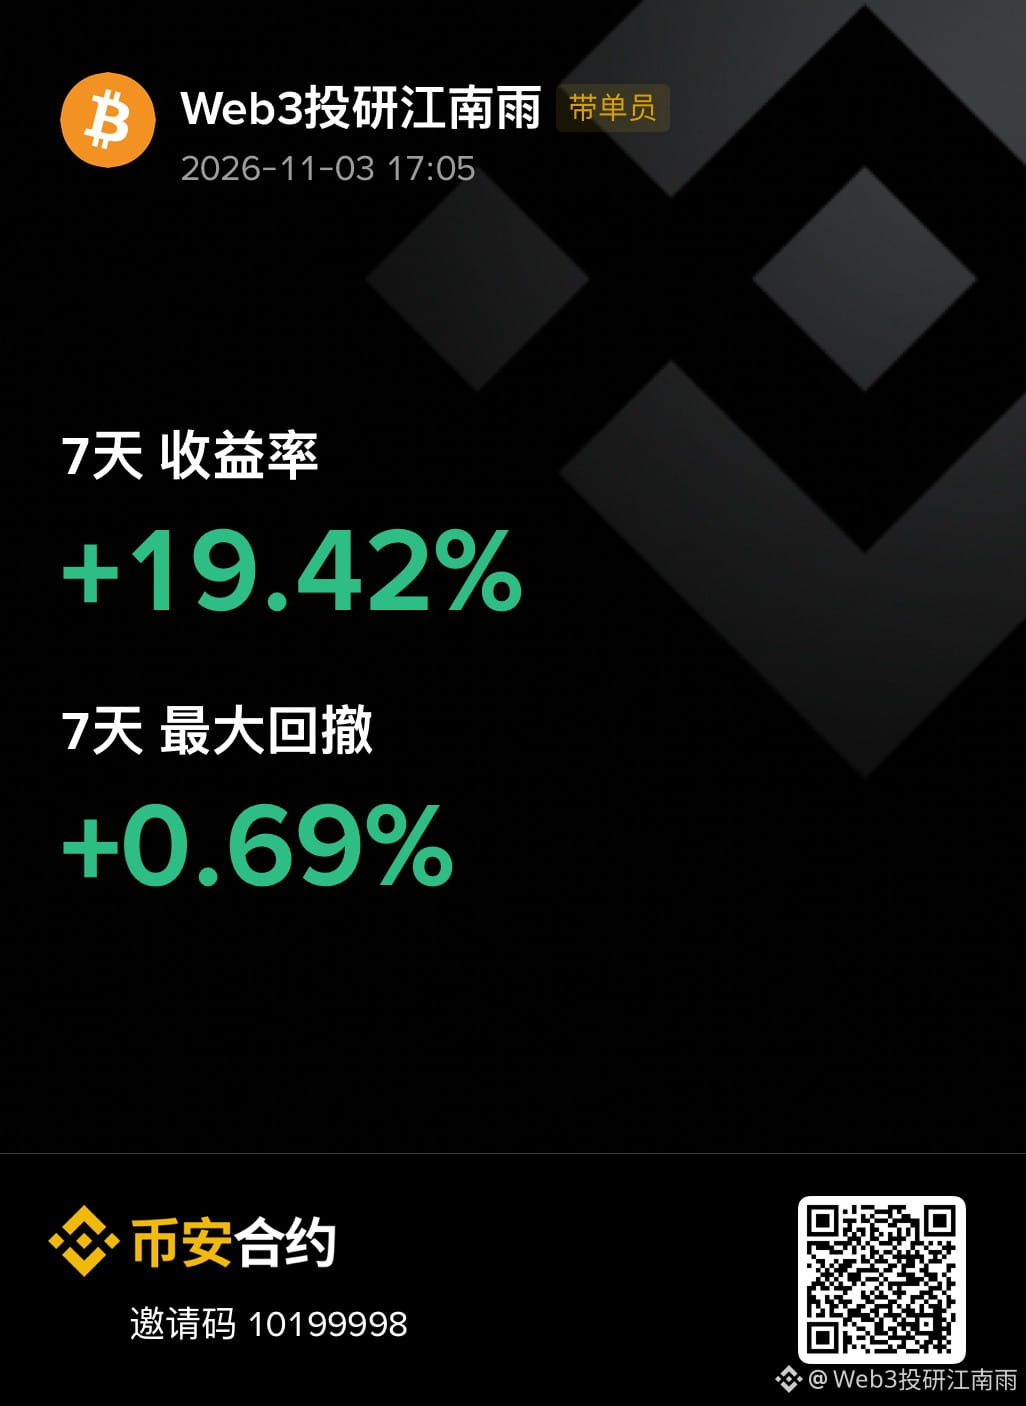
With 10,000 USDT in principal, I made 19% in 7 days, with a 0.69% drawdown. Since I mainly do arbitrage, the risk is low.
With 10,000 USDT in principal, I made 19% in 7 days, with a 0.69% drawdown. Since I mainly do arbitrage, the risk is low.
41
·
--
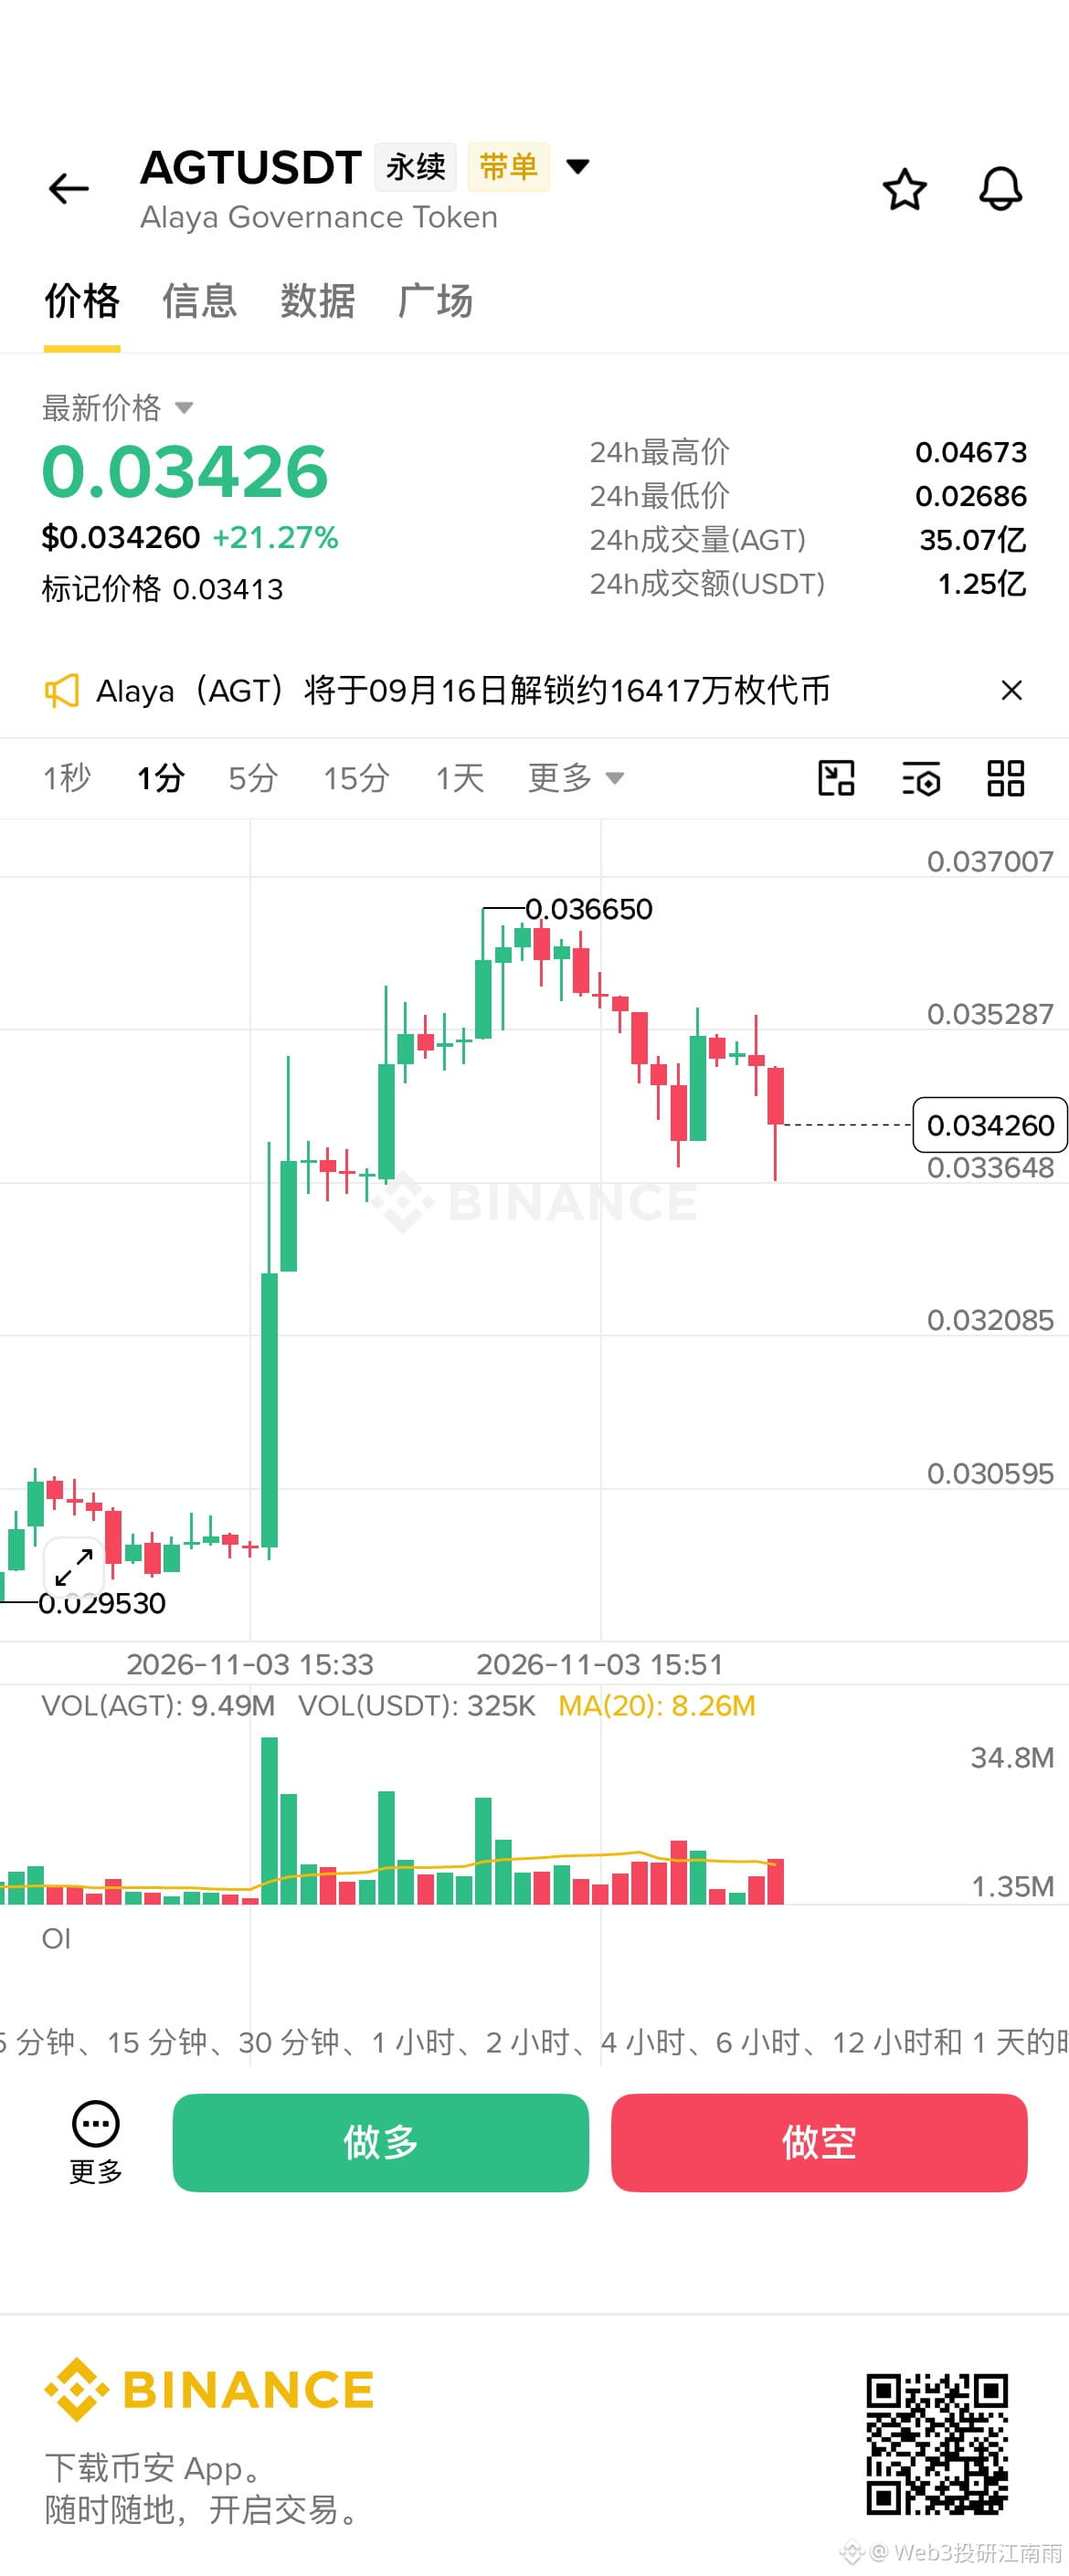
AGT is being shorted and has started to plummet $AGT
{future}(AGTUSDT)
AGT is being shorted and has started to plummet $AGT
Sourced by user sharing on Binance
109
·
--
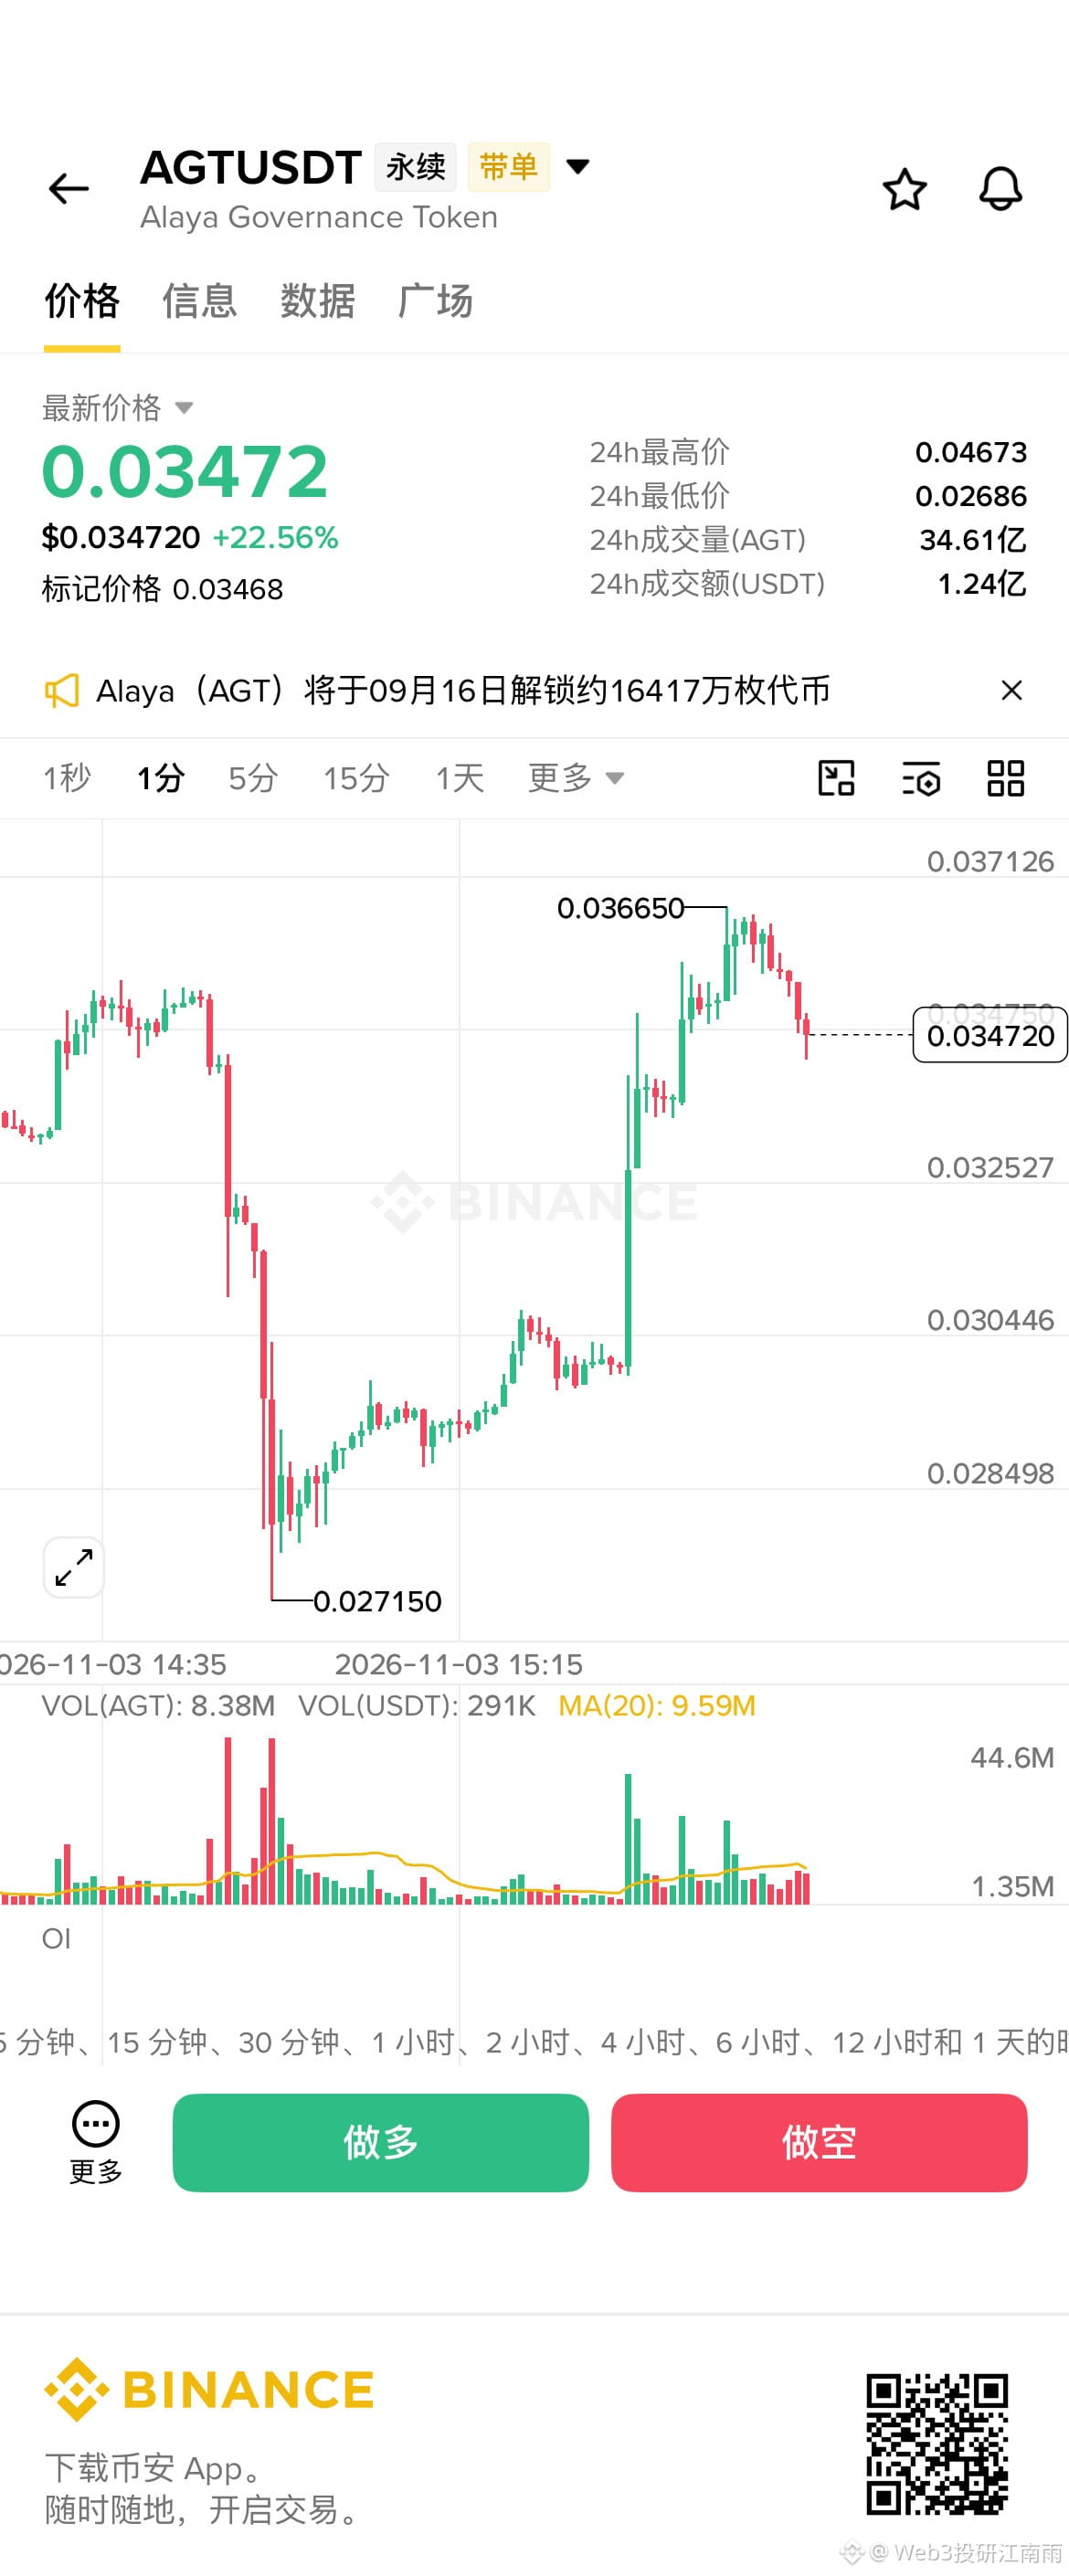
AGT, try short selling and short-term trading; if it doesn't work, exit immediately $AGT
{future}(AGTUSDT)
AGT, try short selling and short-term trading; if it doesn't work, exit immediately $AGT
Sourced by user sharing on Binance
300
·
--
Tracking AGT. I suspect it’s a shakeout, and there may be another rally. I’m keeping an eye on it and waiting for a possible bottom to form before buying in batches.
$AGT
{future}(AGTUSDT)
Tracking AGT. I suspect it’s a shakeout, and there may be another rally. I’m keeping an eye on it and waiting for a possible bottom to form before buying in batches.
$AGT
$AGT
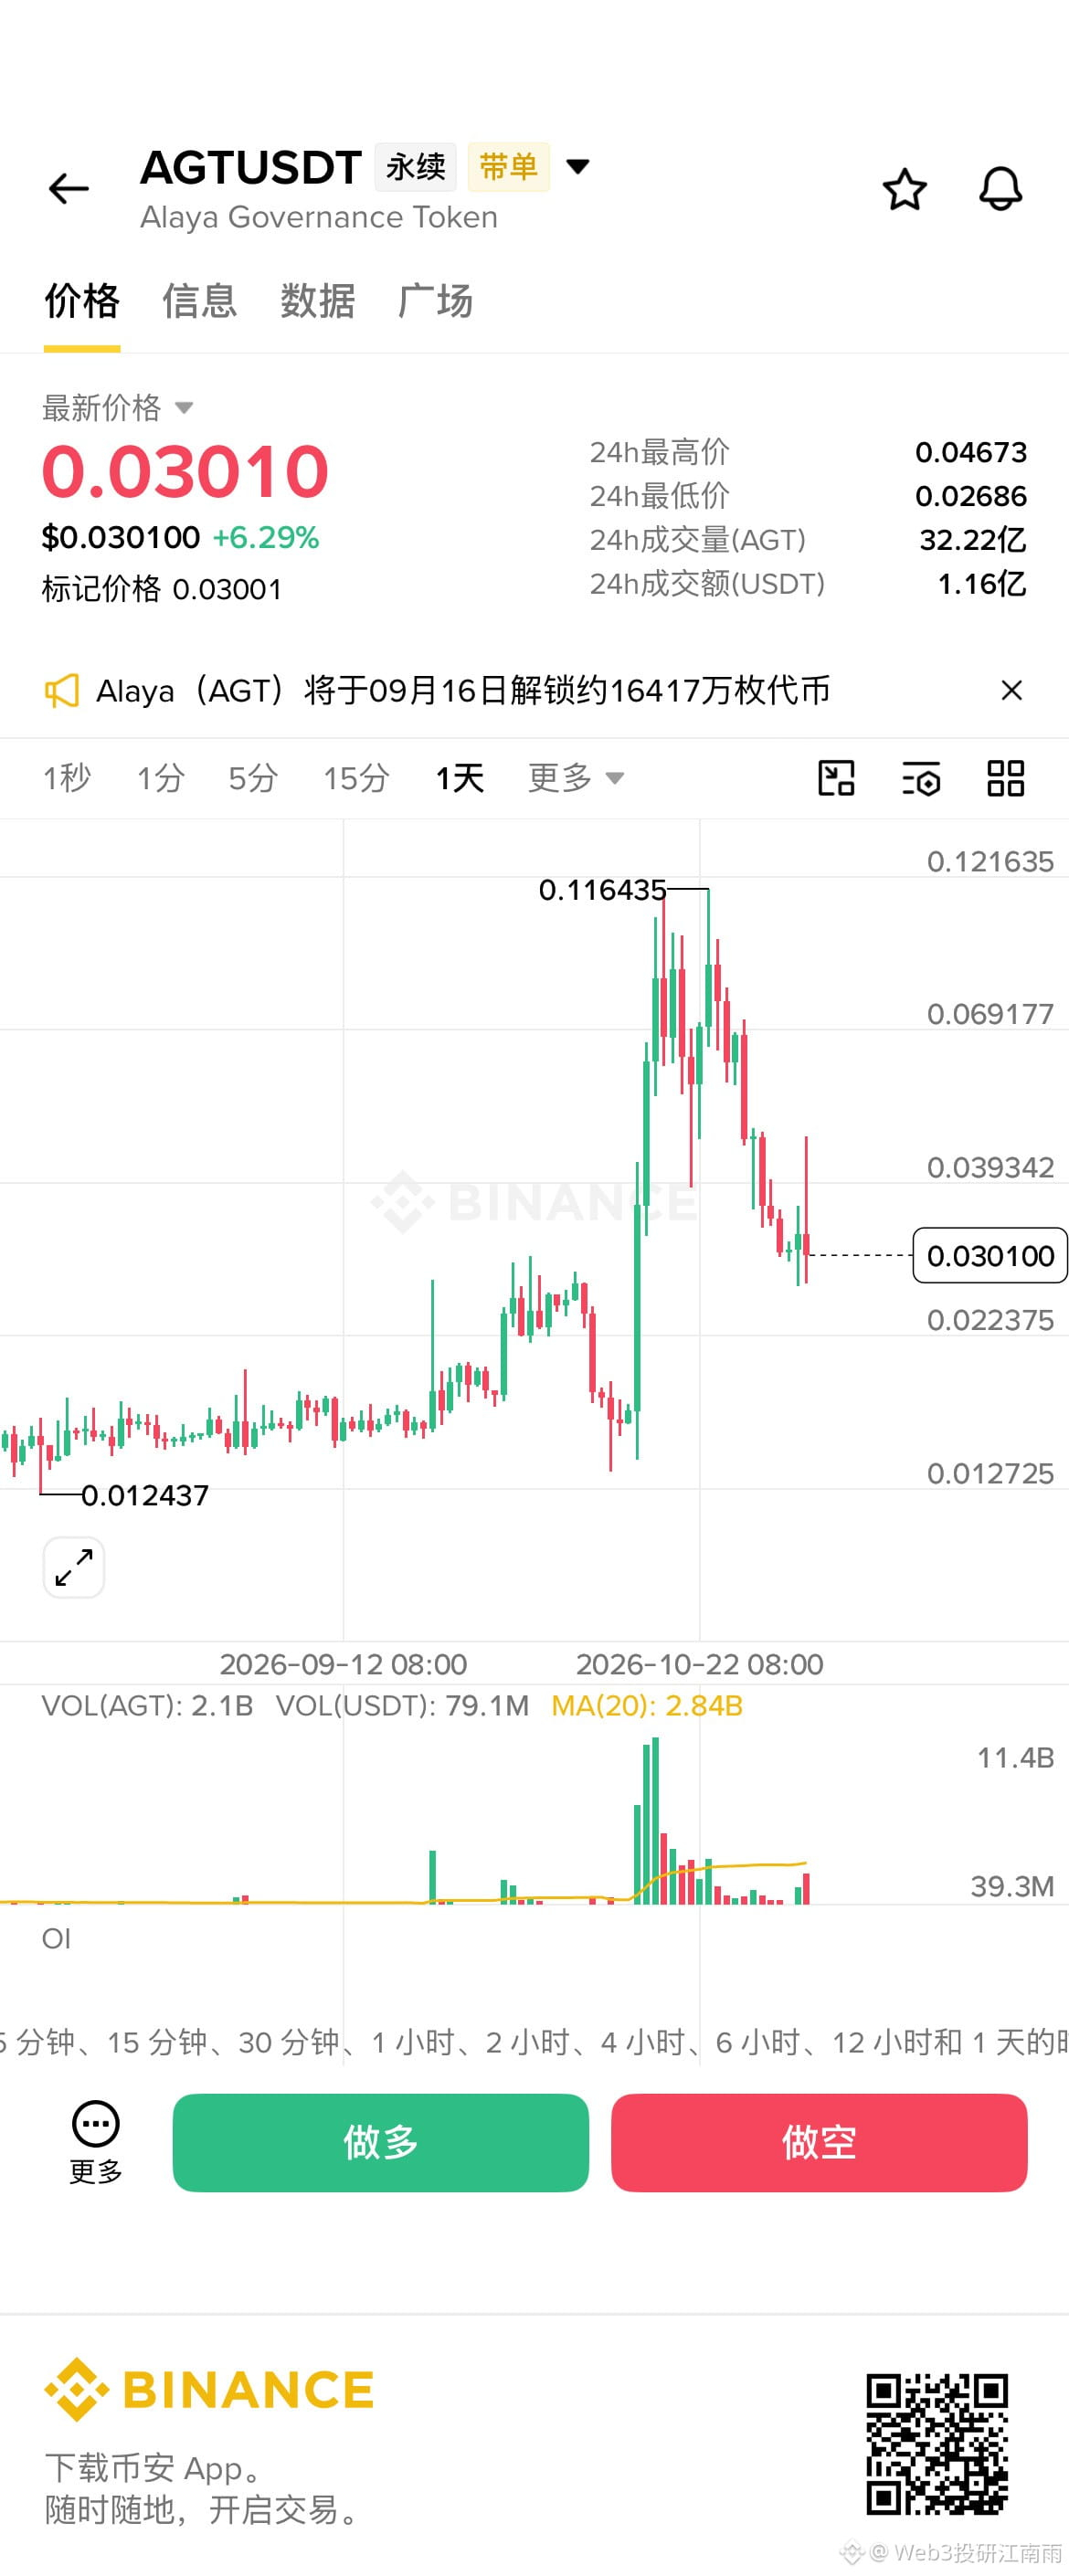
Sourced by user sharing on Binance
1
414
·
--
30D trade $SKHYNIX 4.2M USDT
The Big Short crew is back together. Steve Eisman, the real-life inspiration for the character who shorted the subprime mortgage crisis, and his longtime partner Danny Moses have reunited to expose the so-called “new subprime” Wall Street has just dressed up in AI computing power.
A few months ago, BlackRock CEO Larry Fink publicly praised on CNBC a computing-power securitization deal jointly put together by Nvidia and major Wall Street banks, saying it reminded him of the mortgage-backed securities they created in the 1970s. Watching on screen, Moses was stunned. He said it was an exact replay of the subprime playbook from 2006 to 2007: back then, Wall Street gave subprime lenders warehouse lines of credit. After making loans, the lenders sold them back to Wall Street to be packaged and distributed. Once loan prices fell below the 102.5 cost threshold, Wall Street pulled the credit lines, and the subprime firms immediately went bust.
234
His longtime partner Steve Eisman took a look at Nvidia’s earnings report from last month. The day after revenue surged 110%, its quarterly 10-Q filing revealed that 70% of the world’s largest company by market capitalization’s accounts receivable was concentrated among just five customers. Downstream, CoreWeave is taking on $51 billion in debt, including lease obligations, to buy chips and rent out computing capacity on short-term contracts. Moses said he would never buy the company: its balance sheet is mismatched, and with GPU prices falling and open-source models catching up, he simply can’t see how it will make money.
Computing power isn’t the only thing that doesn’t add up. Several trillion dollars in private credit operates outside bank regulation, with much of it lent to tech companies. Meanwhile, on the private equity side, the 10-year Treasury yield is stuck between 5.27% and 5.3%, and funds’ exit timelines have stretched from three to four years five or six years ago to seven to 10 years now. Redemption requests at many funds have exceeded the 5% cap, triggering restrictions and shutdowns. Moses warned retail investors: when these high-end private-market products start landing in your inbox, there’s only one reason—the institutions don’t want them anymore and are looking for retail investors to take them off their hands.
U.S. national debt has surged from $8 trillion in 2008 to more than $40 trillion. This year, another $500 billion in AI-related debt is expected to be issued in private markets. For the first time in history, private financing has grown so large that it is crowding out Treasuries. Moses said that the Treasury buying $20 billion in long-term bonds is like an ant in the face of the market. Gold has become the largest holding of central banks worldwide, accounting for 27% of their reserves, and the Federal Reserve will ultimately have no choice but to restart the money printers to get out of this jam.
#美股 $SKHYNIX
The Big Short crew is back together. Steve Eisman, the real-life inspiration for the character who shorted the subprime mortgage crisis, and his longtime partner Danny Moses have reunited to expose the so-called “new subprime” Wall Street has just dressed up in AI computing power.
A few months ago, BlackRock CEO Larry Fink publicly praised on CNBC a computing-power securitization deal jointly put together by Nvidia and major Wall Street banks, saying it reminded him of the mortgage-backed securities they created in the 1970s. Watching on screen, Moses was stunned. He said it was an exact replay of the subprime playbook from 2006 to 2007: back then, Wall Street gave subprime lenders warehouse lines of credit. After making loans, the lenders sold them back to Wall Street to be packaged and distributed. Once loan prices fell below the 102.5 cost threshold, Wall Street pulled the credit lines, and the subprime firms immediately went bust.
234
His longtime partner Steve Eisman took a look at Nvidia’s earnings report from last month. The day after revenue surged 110%, its quarterly 10-Q filing revealed that 70% of the world’s largest company by market capitalization’s accounts receivable was concentrated among just five customers. Downstream, CoreWeave is taking on $51 billion in debt, including lease obligations, to buy chips and rent out computing capacity on short-term contracts. Moses said he would never buy the company: its balance sheet is mismatched, and with GPU prices falling and open-source models catching up, he simply can’t see how it will make money.
Computing power isn’t the only thing that doesn’t add up. Several trillion dollars in private credit operates outside bank regulation, with much of it lent to tech companies. Meanwhile, on the private equity side, the 10-year Treasury yield is stuck between 5.27% and 5.3%, and funds’ exit timelines have stretched from three to four years five or six years ago to seven to 10 years now. Redemption requests at many funds have exceeded the 5% cap, triggering restrictions and shutdowns. Moses warned retail investors: when these high-end private-market products start landing in your inbox, there’s only one reason—the institutions don’t want them anymore and are looking for retail investors to take them off their hands.
U.S. national debt has surged from $8 trillion in 2008 to more than $40 trillion. This year, another $500 billion in AI-related debt is expected to be issued in private markets. For the first time in history, private financing has grown so large that it is crowding out Treasuries. Moses said that the Treasury buying $20 billion in long-term bonds is like an ant in the face of the market. Gold has become the largest holding of central banks worldwide, accounting for 27% of their reserves, and the Federal Reserve will ultimately have no choice but to restart the money printers to get out of this jam.
#美股 $SKHYNIX
A few months ago, BlackRock CEO Larry Fink publicly praised on CNBC a computing-power securitization deal jointly put together by Nvidia and major Wall Street banks, saying it reminded him of the mortgage-backed securities they created in the 1970s. Watching on screen, Moses was stunned. He said it was an exact replay of the subprime playbook from 2006 to 2007: back then, Wall Street gave subprime lenders warehouse lines of credit. After making loans, the lenders sold them back to Wall Street to be packaged and distributed. Once loan prices fell below the 102.5 cost threshold, Wall Street pulled the credit lines, and the subprime firms immediately went bust.
234
His longtime partner Steve Eisman took a look at Nvidia’s earnings report from last month. The day after revenue surged 110%, its quarterly 10-Q filing revealed that 70% of the world’s largest company by market capitalization’s accounts receivable was concentrated among just five customers. Downstream, CoreWeave is taking on $51 billion in debt, including lease obligations, to buy chips and rent out computing capacity on short-term contracts. Moses said he would never buy the company: its balance sheet is mismatched, and with GPU prices falling and open-source models catching up, he simply can’t see how it will make money.
Computing power isn’t the only thing that doesn’t add up. Several trillion dollars in private credit operates outside bank regulation, with much of it lent to tech companies. Meanwhile, on the private equity side, the 10-year Treasury yield is stuck between 5.27% and 5.3%, and funds’ exit timelines have stretched from three to four years five or six years ago to seven to 10 years now. Redemption requests at many funds have exceeded the 5% cap, triggering restrictions and shutdowns. Moses warned retail investors: when these high-end private-market products start landing in your inbox, there’s only one reason—the institutions don’t want them anymore and are looking for retail investors to take them off their hands.
U.S. national debt has surged from $8 trillion in 2008 to more than $40 trillion. This year, another $500 billion in AI-related debt is expected to be issued in private markets. For the first time in history, private financing has grown so large that it is crowding out Treasuries. Moses said that the Treasury buying $20 billion in long-term bonds is like an ant in the face of the market. Gold has become the largest holding of central banks worldwide, accounting for 27% of their reserves, and the Federal Reserve will ultimately have no choice but to restart the money printers to get out of this jam.
#美股 $SKHYNIX
282
·
--
$MU Micron earnings report excerpt
① Most of the HBM bit supply volume for calendar year 2027 has been contracted.
② Contract prices have risen significantly from the previous year, and the gross margin gap versus traditional DRAM will also narrow.
③ The growth rate of HBM sales revenue will be faster than the growth rate of the company’s overall sales revenue in the fourth quarter.
$MU Micron earnings report excerpt
① Most of the HBM bit supply volume for calendar year 2027 has been contracted.
② Contract prices have risen significantly from the previous year, and the gross margin gap versus traditional DRAM will also narrow.
③ The growth rate of HBM sales revenue will be faster than the growth rate of the company’s overall sales revenue in the fourth quarter.
① Most of the HBM bit supply volume for calendar year 2027 has been contracted.
② Contract prices have risen significantly from the previous year, and the gross margin gap versus traditional DRAM will also narrow.
③ The growth rate of HBM sales revenue will be faster than the growth rate of the company’s overall sales revenue in the fourth quarter.
193
·
--
Micron (MU) Earnings$MU
A memo to the market: The market and ignorance are once again working hand in hand.
I just listened to Micron's (MU) earnings call, and a large part of the market still underestimates how persistently Micron, SK hynix, and Samsung’s earnings potential may hold up.
We’ve seen adjusted gross margins of 80% and 87%; next quarter will be 86.25%. This is where the focus will be.
I’m going to pull you away from the numbers, because the story behind them matters far more than the numbers themselves.
There are bandwidth issues, and also supply issues. Then there’s demand—driven by data center buildouts and server-class memory components, demand has been growing explosively for the past year and a half.
Micron (MU) Earnings
$MU
A memo to the market: The market and ignorance are once again working hand in hand.
I just listened to Micron's (MU) earnings call, and a large part of the market still underestimates how persistently Micron, SK hynix, and Samsung’s earnings potential may hold up.
We’ve seen adjusted gross margins of 80% and 87%; next quarter will be 86.25%. This is where the focus will be.
I’m going to pull you away from the numbers, because the story behind them matters far more than the numbers themselves.
There are bandwidth issues, and also supply issues. Then there’s demand—driven by data center buildouts and server-class memory components, demand has been growing explosively for the past year and a half.
A memo to the market: The market and ignorance are once again working hand in hand.
I just listened to Micron's (MU) earnings call, and a large part of the market still underestimates how persistently Micron, SK hynix, and Samsung’s earnings potential may hold up.
We’ve seen adjusted gross margins of 80% and 87%; next quarter will be 86.25%. This is where the focus will be.
I’m going to pull you away from the numbers, because the story behind them matters far more than the numbers themselves.
There are bandwidth issues, and also supply issues. Then there’s demand—driven by data center buildouts and server-class memory components, demand has been growing explosively for the past year and a half.
442
·
--
Micron has signed 26 strategic customer agreements, some of which have been extended to 2031. Yes, you heard that right—2031.
10 more SCAs than the previous quarter.
$MU
Micron has signed 26 strategic customer agreements, some of which have been extended to 2031. Yes, you heard that right—2031.
10 more SCAs than the previous quarter.
$MU
10 more SCAs than the previous quarter.
$MU
219
·
--
The US starts directly extracting money from residents—dollar liquidity tides flow from institutional desks, all the way down to ordinary people around the world.
🔹 This year, in July the DTCC runs tokenized securities; in October the Tokenization Service goes live; and on December 6 Nasdaq extends trading to 5 days a week, nearly 23 hours.
🔹 Stablecoins solve the money, 23-hour trading solves the time, and asset tokenization solves what to buy. With these three pieces in place, America’s next round of “pulling in” won’t be just money from central banks and banks, but also global residents’ savings.
🔹 Japan “sucks up,” China doesn’t provide a backstop, and the US holds first. Once the gates open on January 18, the dollar system will plunge straight from B2B to B2C.
🔹 The shifting period will be volatile—maybe even violently so. Where the money comes from, and where it goes, is where the next highly certain opportunities lie. What do you think?
The US starts directly extracting money from residents—dollar liquidity tides flow from institutional desks, all the way down to ordinary people around the world.
🔹 This year, in July the DTCC runs tokenized securities; in October the Tokenization Service goes live; and on December 6 Nasdaq extends trading to 5 days a week, nearly 23 hours.
🔹 Stablecoins solve the money, 23-hour trading solves the time, and asset tokenization solves what to buy. With these three pieces in place, America’s next round of “pulling in” won’t be just money from central banks and banks, but also global residents’ savings.
🔹 Japan “sucks up,” China doesn’t provide a backstop, and the US holds first. Once the gates open on January 18, the dollar system will plunge straight from B2B to B2C.
🔹 The shifting period will be volatile—maybe even violently so. Where the money comes from, and where it goes, is where the next highly certain opportunities lie. What do you think?
🔹 This year, in July the DTCC runs tokenized securities; in October the Tokenization Service goes live; and on December 6 Nasdaq extends trading to 5 days a week, nearly 23 hours.
🔹 Stablecoins solve the money, 23-hour trading solves the time, and asset tokenization solves what to buy. With these three pieces in place, America’s next round of “pulling in” won’t be just money from central banks and banks, but also global residents’ savings.
🔹 Japan “sucks up,” China doesn’t provide a backstop, and the US holds first. Once the gates open on January 18, the dollar system will plunge straight from B2B to B2C.
🔹 The shifting period will be volatile—maybe even violently so. Where the money comes from, and where it goes, is where the next highly certain opportunities lie. What do you think?
2.3k
·
--
Next year, capital expenditures for the super-large cloud service providers are expected to be between $1.1 trillion and $1.2 trillion, and storage alone could account for 50% to 60% of that—roughly $500 billion to $700 billion. UBS even estimates that spending on storage alone next year will reach $900 billion.
$SKHYNIX
Next year, capital expenditures for the super-large cloud service providers are expected to be between $1.1 trillion and $1.2 trillion, and storage alone could account for 50% to 60% of that—roughly $500 billion to $700 billion. UBS even estimates that spending on storage alone next year will reach $900 billion.
$SKHYNIX
$SKHYNIX
508
·
--
Partly True
260918
U.S. stock market closes; memory stocks plunge sharply. It is said to be caused by a report about China’s ChangXin increasing memory production.
$SKHYNIX
260918
U.S. stock market closes; memory stocks plunge sharply. It is said to be caused by a report about China’s ChangXin increasing memory production.
$SKHYNIX
U.S. stock market closes; memory stocks plunge sharply. It is said to be caused by a report about China’s ChangXin increasing memory production.
$SKHYNIX
237
·
--
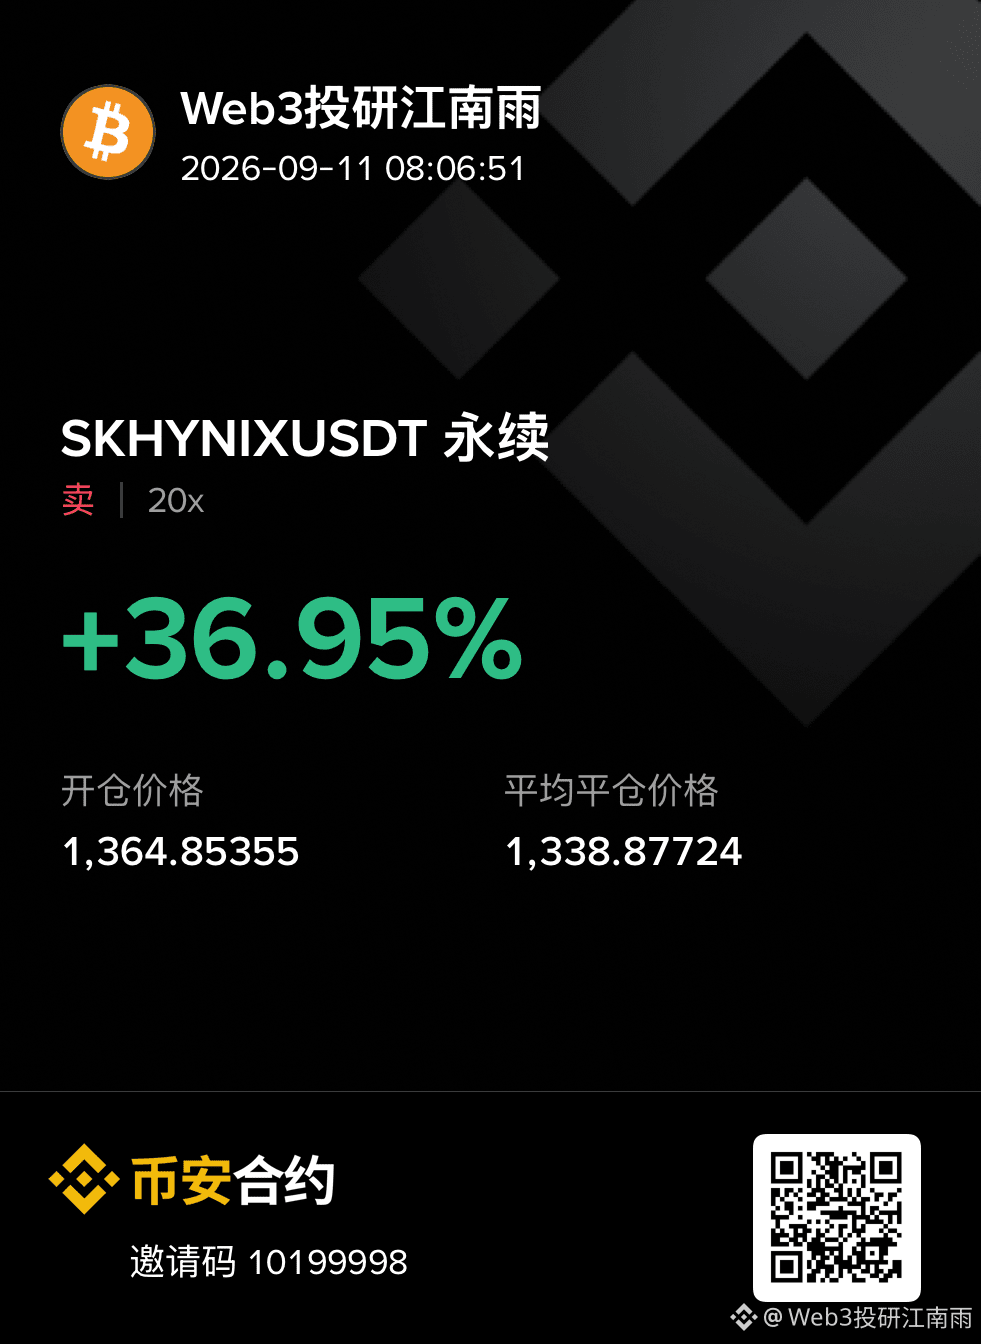
30D trade $SKHYNIX 2.6M USDT
$SKHYNIX
{future}(SKHYNIXUSDT)
Seeing the U.S. market decline, I went short on Hynix and closed the position at the next day’s open.
$SKHYNIX
Seeing the U.S. market decline, I went short on Hynix and closed the position at the next day’s open.
Seeing the U.S. market decline, I went short on Hynix and closed the position at the next day’s open.
669
·
--
Partly True
30D trade $SKHYNIX 2.8M USDT
Nomura Securities
SK hynix currently holds about 25% of global memory revenue…… If these Nomura estimates are correct, and SK hynix maintains its current market share…… then this would mean that SK hynix’s revenue in 2030 will be about $918 billion (US dollars).
From 2026 to 2030…… SK hynix will generate $1.8 trillion in net profit, which is 80% more than its current market value.
$SKHYNIX
Nomura Securities
SK hynix currently holds about 25% of global memory revenue…… If these Nomura estimates are correct, and SK hynix maintains its current market share…… then this would mean that SK hynix’s revenue in 2030 will be about $918 billion (US dollars).
From 2026 to 2030…… SK hynix will generate $1.8 trillion in net profit, which is 80% more than its current market value.
$SKHYNIX
SK hynix currently holds about 25% of global memory revenue…… If these Nomura estimates are correct, and SK hynix maintains its current market share…… then this would mean that SK hynix’s revenue in 2030 will be about $918 billion (US dollars).
From 2026 to 2030…… SK hynix will generate $1.8 trillion in net profit, which is 80% more than its current market value.
$SKHYNIX
273
·
--
Nomura has set an undeniable number for the memory market.
It expects the entire market to be about $1 trillion in 2026. Then it will reach $3.7 trillion by 2030. That means growth of more than 3.5 times in four years.
Data centers will account for 83% of the total by 2030. AI data centers will become the largest single share.
Growth is not smooth.
In 2024 it is about $185 billion.
In 2025 $270 billion.
Then in 2026 it jumps to $1 trillion, after which it keeps rising.
$SKHYNIX
Nomura has set an undeniable number for the memory market.
It expects the entire market to be about $1 trillion in 2026. Then it will reach $3.7 trillion by 2030. That means growth of more than 3.5 times in four years.
Data centers will account for 83% of the total by 2030. AI data centers will become the largest single share.
Growth is not smooth.
In 2024 it is about $185 billion.
In 2025 $270 billion.
Then in 2026 it jumps to $1 trillion, after which it keeps rising.
$SKHYNIX
It expects the entire market to be about $1 trillion in 2026. Then it will reach $3.7 trillion by 2030. That means growth of more than 3.5 times in four years.
Data centers will account for 83% of the total by 2030. AI data centers will become the largest single share.
Growth is not smooth.
In 2024 it is about $185 billion.
In 2025 $270 billion.
Then in 2026 it jumps to $1 trillion, after which it keeps rising.
$SKHYNIX
213
·
--
Memory Industry Information Notes
260909
Rumor: Changxin's HBM yield is only 25%. Therefore, Changxin does not pose a threat to other HBM manufacturers.
260908
Rumor: The manufacturer's memory inventory is insufficient for more than 10 days.
260908
It is expected that in 2027, global DRAM production will increase by only a little over 20%.
$SKHYNIX
{future}(SKHYNIXUSDT)
Memory Industry Information Notes
260909
Rumor: Changxin's HBM yield is only 25%. Therefore, Changxin does not pose a threat to other HBM manufacturers.
260908
Rumor: The manufacturer's memory inventory is insufficient for more than 10 days.
260908
It is expected that in 2027, global DRAM production will increase by only a little over 20%.
$SKHYNIX
260909
Rumor: Changxin's HBM yield is only 25%. Therefore, Changxin does not pose a threat to other HBM manufacturers.
260908
Rumor: The manufacturer's memory inventory is insufficient for more than 10 days.
260908
It is expected that in 2027, global DRAM production will increase by only a little over 20%.
$SKHYNIX
106
·
--
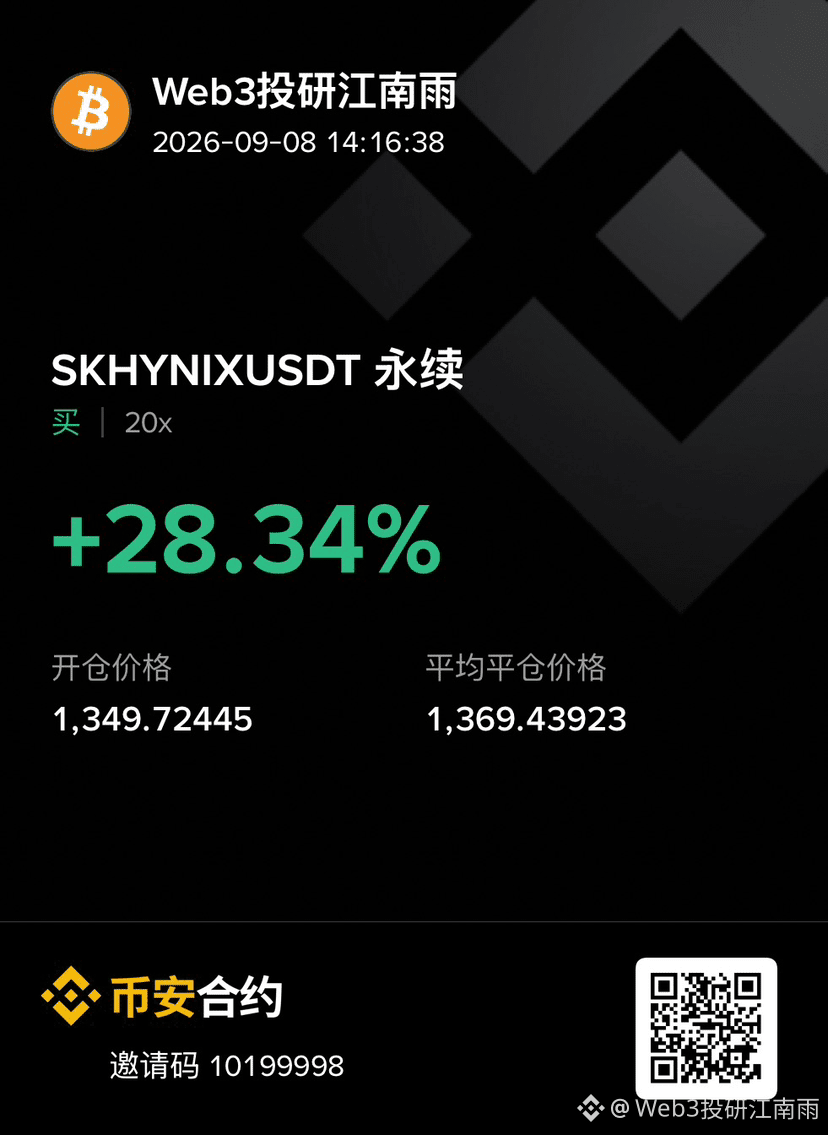
This morning, go long on $SKHYNIX on a short-term basis. After about 20 minutes from the opening, close all positions.
This morning, go long on $SKHYNIX on a short-term basis. After about 20 minutes from the opening, close all positions.
822
·
--
Last Friday, storage stocks on the U.S. stock market surged. So, I went long at the opening today at $SKHYNIX and made some profit
Last Friday, storage stocks on the U.S. stock market surged. So, I went long at the opening today at $SKHYNIX and made some profit
273
·
--
Nomura released its view on the global memory market and stated the things we all already know
Here are the key points from Nomura’s view on the global memory market
Global memory:
- Manufacturers claim that severe supply shortages will continue
- LTAs will restructure their businesses to make them visible and stable
- Customers are willing to accept unattractive terms to secure supply
- Memory spec degradation is inevitable due to supply shortages
- By 2027, data center demand is expected to be met only 70%, and non-data center demand about 50%
- Nomura believes that, due to shortages, $NVDA cannot broadly adopt high-stack HBM
- Challenges from Chinese players are unlikely to pose a significant threat
- Interest rates and foreign exchange are threats
- The capex train is expected to keep rolling
LTAs:
- There is significant uncertainty because negotiations are still ongoing, forcing institutions to make some assumptions
- LTAs will account for about 50-70% of total $DRAM NAND and SSD sales. Mainly targeted at CSPs (10-20 customers)
- The remaining 30-50% will be sold directly to the market at spot prices
- LTAs mainly run for 5 years, with strong agreements for the first 3 years and flexibility for the next 2 years
- Prepayments account for about 20-30% of revenue. The penalty for customers breaking commitments is equivalent to about 1 year of purchasing value
- In short, LTAs provide tremendous visibility, pricing power, and cash flow for the business
Investment perspective
- Nomura believes memory stocks can maintain strong growth
- It believes a rebound and growth are only a matter of time
- Total DRAM
- $DRAM wafer capacity utilization is about 100%
- The share of data centers in memory revenue is expected to rise from 40% in 2025 to 83% in 2030
- Memory revenue is expected to reach $3 trillion by 2029
- Samsung Electronics at 5.2x FY26E P/E and 2.2x P/B. At 2.9x FY27E P/E and 1.4x P/B
- $SKHY at 4.8x FY26E P/E and 2.8x P/B. At 3.1x FY27E P/E and 1.7x P/B
- Both companies are rated "Buy" based on improving margins, free cash flow, and the likelihood of higher shareholder returns
Samsung’s target price is set at 670K (167.5% upside), and SK Hynix’s target price is set at 4.7M (191.4% upside)
#美股 #TradFi
$SKHYNIX
{future}(SKHYNIXUSDT)
Nomura released its view on the global memory market and stated the things we all already know
Here are the key points from Nomura’s view on the global memory market
Global memory:
- Manufacturers claim that severe supply shortages will continue
- LTAs will restructure their businesses to make them visible and stable
- Customers are willing to accept unattractive terms to secure supply
- Memory spec degradation is inevitable due to supply shortages
- By 2027, data center demand is expected to be met only 70%, and non-data center demand about 50%
- Nomura believes that, due to shortages, $NVDA cannot broadly adopt high-stack HBM
- Challenges from Chinese players are unlikely to pose a significant threat
- Interest rates and foreign exchange are threats
- The capex train is expected to keep rolling
LTAs:
- There is significant uncertainty because negotiations are still ongoing, forcing institutions to make some assumptions
- LTAs will account for about 50-70% of total $DRAM NAND and SSD sales. Mainly targeted at CSPs (10-20 customers)
- The remaining 30-50% will be sold directly to the market at spot prices
- LTAs mainly run for 5 years, with strong agreements for the first 3 years and flexibility for the next 2 years
- Prepayments account for about 20-30% of revenue. The penalty for customers breaking commitments is equivalent to about 1 year of purchasing value
- In short, LTAs provide tremendous visibility, pricing power, and cash flow for the business
Investment perspective
- Nomura believes memory stocks can maintain strong growth
- It believes a rebound and growth are only a matter of time
- Total DRAM
- $DRAM wafer capacity utilization is about 100%
- The share of data centers in memory revenue is expected to rise from 40% in 2025 to 83% in 2030
- Memory revenue is expected to reach $3 trillion by 2029
- Samsung Electronics at 5.2x FY26E P/E and 2.2x P/B. At 2.9x FY27E P/E and 1.4x P/B
- $SKHY at 4.8x FY26E P/E and 2.8x P/B. At 3.1x FY27E P/E and 1.7x P/B
- Both companies are rated "Buy" based on improving margins, free cash flow, and the likelihood of higher shareholder returns
Samsung’s target price is set at 670K (167.5% upside), and SK Hynix’s target price is set at 4.7M (191.4% upside)
#美股 #TradFi
$SKHYNIX
Here are the key points from Nomura’s view on the global memory market
Global memory:
- Manufacturers claim that severe supply shortages will continue
- LTAs will restructure their businesses to make them visible and stable
- Customers are willing to accept unattractive terms to secure supply
- Memory spec degradation is inevitable due to supply shortages
- By 2027, data center demand is expected to be met only 70%, and non-data center demand about 50%
- Nomura believes that, due to shortages, $NVDA cannot broadly adopt high-stack HBM
- Challenges from Chinese players are unlikely to pose a significant threat
- Interest rates and foreign exchange are threats
- The capex train is expected to keep rolling
LTAs:
- There is significant uncertainty because negotiations are still ongoing, forcing institutions to make some assumptions
- LTAs will account for about 50-70% of total $DRAM NAND and SSD sales. Mainly targeted at CSPs (10-20 customers)
- The remaining 30-50% will be sold directly to the market at spot prices
- LTAs mainly run for 5 years, with strong agreements for the first 3 years and flexibility for the next 2 years
- Prepayments account for about 20-30% of revenue. The penalty for customers breaking commitments is equivalent to about 1 year of purchasing value
- In short, LTAs provide tremendous visibility, pricing power, and cash flow for the business
Investment perspective
- Nomura believes memory stocks can maintain strong growth
- It believes a rebound and growth are only a matter of time
- Total DRAM
- $DRAM wafer capacity utilization is about 100%
- The share of data centers in memory revenue is expected to rise from 40% in 2025 to 83% in 2030
- Memory revenue is expected to reach $3 trillion by 2029
- Samsung Electronics at 5.2x FY26E P/E and 2.2x P/B. At 2.9x FY27E P/E and 1.4x P/B
- $SKHY at 4.8x FY26E P/E and 2.8x P/B. At 3.1x FY27E P/E and 1.7x P/B
- Both companies are rated "Buy" based on improving margins, free cash flow, and the likelihood of higher shareholder returns
Samsung’s target price is set at 670K (167.5% upside), and SK Hynix’s target price is set at 4.7M (191.4% upside)
#美股 #TradFi
$SKHYNIX
232
·
--
Verified
Micron’s own HBM architect, on site at the Hot Chips conference:
“Computing power grows by about 3x every two years. Although HBM has solved many bandwidth issues and improved bandwidth, it still lags behind demand, growing only about 2x every two years. Therefore, the memory wall problem still exists, and in fact, it may be getting worse.”
— Raghu Sreeramaneni, Micron Fellow, HBM Design Architecture
This is a structural gap that keeps widening with each generation of products. The market has not yet realized this difference.
#美股 $SKHYNIX $MU
Micron’s own HBM architect, on site at the Hot Chips conference:
“Computing power grows by about 3x every two years. Although HBM has solved many bandwidth issues and improved bandwidth, it still lags behind demand, growing only about 2x every two years. Therefore, the memory wall problem still exists, and in fact, it may be getting worse.”
— Raghu Sreeramaneni, Micron Fellow, HBM Design Architecture
This is a structural gap that keeps widening with each generation of products. The market has not yet realized this difference.
#美股 $SKHYNIX $MU
“Computing power grows by about 3x every two years. Although HBM has solved many bandwidth issues and improved bandwidth, it still lags behind demand, growing only about 2x every two years. Therefore, the memory wall problem still exists, and in fact, it may be getting worse.”
— Raghu Sreeramaneni, Micron Fellow, HBM Design Architecture
This is a structural gap that keeps widening with each generation of products. The market has not yet realized this difference.
#美股 $SKHYNIX $MU
271
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
BitcoinRebounds$75KAsChipsLead
10,225 views
145 Discussing
Market Watch | Bitcoin Rebounds to $75,600 After Dip Below $75,000 as Chip Stocks Lead Rally on Jobs Beat
Binance News
·17 Likes
·5.1k views
JobsReportRaisesHikeOdds
131,412 views
1,142 Discussing
US Data Center Rules May Constrain AI Expansion
19,429 views
109 Discussing