

EquityPlainTalk
1.4k Posts
EquityPlainTalk
Report
Block User
Clear, common-sense market notes for U.S. stock investors navigating noise, data, and human behavior.
0 Following
158 Followers
377 Liked
Posts
Something weird is happening with $AAPL.
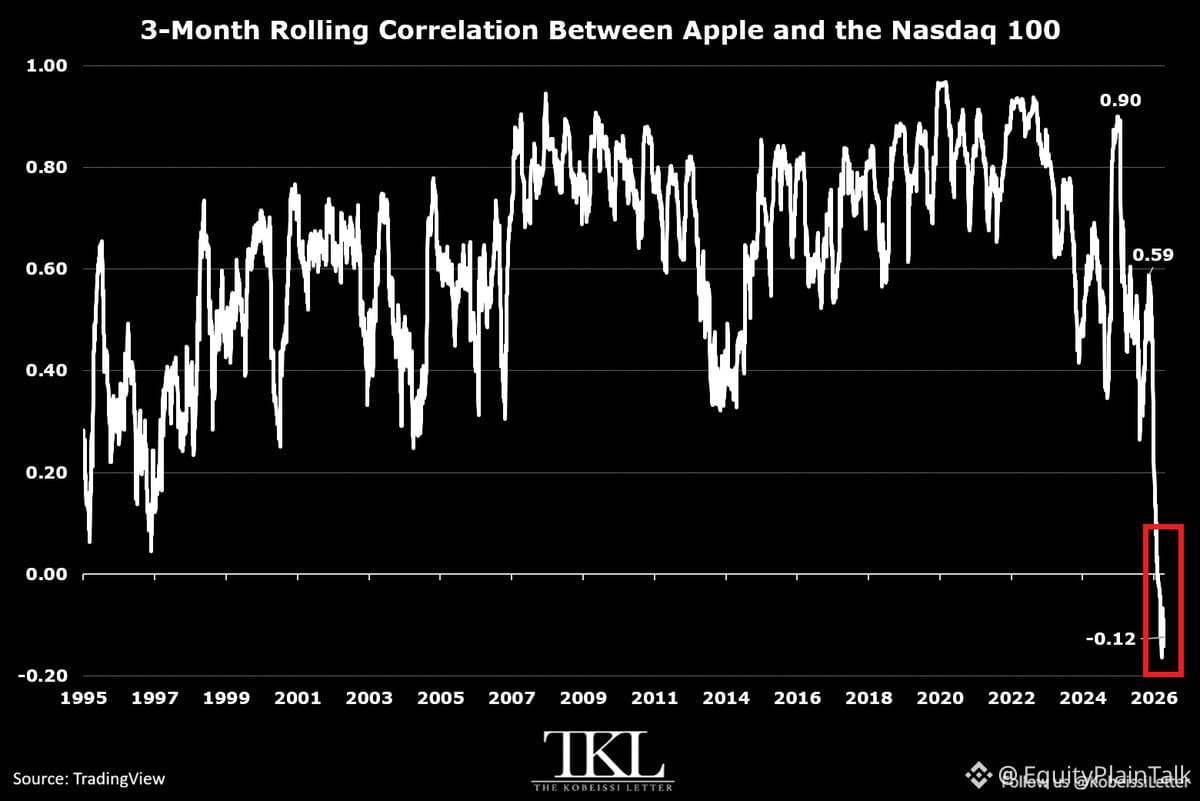
For the first time since the early 1980s, Apple's 3-month correlation with the Nasdaq 100 just turned negative at -0.12. It's been negative for two straight months now.
While $AAPL climbed 9.7% during this period, the Nasdaq 100 barely moved—up just 0.2%.
Just last June, that correlation sat at +0.90. Apple and tech moved together like clockwork. From 2006 to 2025, the correlation never dropped below +0.30.
Now it's negative.
This isn't a small divergence. Apple is decoupling from the rest of big tech in a way we've never seen before. Whether it's AI positioning, buyback activity, or something else entirely, the market is treating Apple like it's in a different category now.
When the largest stock in the index starts moving opposite to the index itself, that's worth paying attention to.
25
Verified
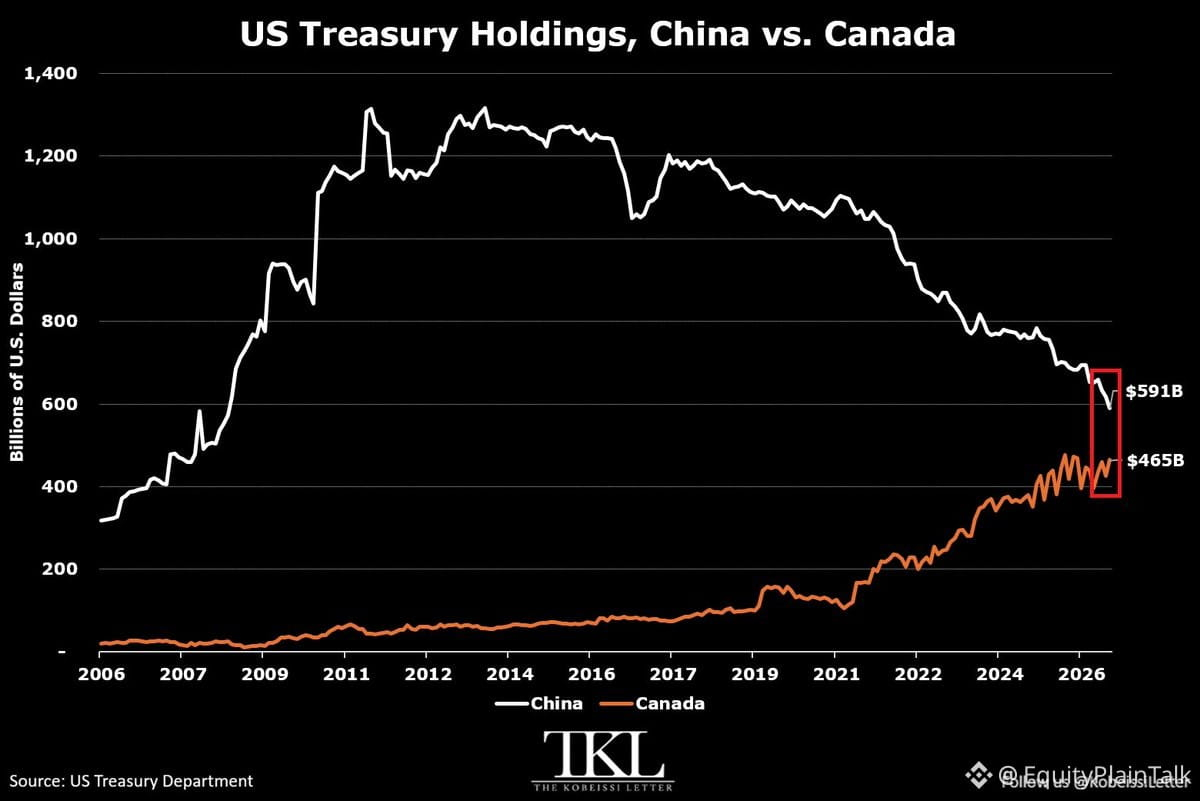
China officially dumped $27B in Treasuries in August—now at $591B, lowest since 2008.
But here's the thing: Canada's holdings jumped $38B that same month to $465B. Since 2019, Canada's up 384% while China's down 48%.
Coincidence? Probably not.
Belgium and Luxembourg—known custodial havens—also hit all-time highs in August at $491B and $448B respectively.
China might just be moving its Treasury exposure through third-party custodians to make its Dollar exposure look smaller than it really is. Classic shell game.
The headline says "decoupling." The data says "relabeling."
Don't confuse optics with reality. China's Dollar ties are likely stickier than the official numbers suggest.
AGGETF+0.08%
975
October just delivered the biggest rotation out of AI stocks we've ever seen.
The S&P 500 ex-AI is beating the full index by +6.4% this month — on pace for the largest monthly spread on record. Just last month, AI names led by 5.1%. That's a complete reversal in 30 days.
Last 3 weeks alone? +7.4% outperformance for non-AI stocks. Never happened before.
What's driving this?
Profit-taking. After a monster run, AI winners are getting trimmed while everything else catches a bid. Sector rotation is real. Money's flowing into stuff that got left behind — industrials, financials, consumer names.
This year's been a ping-pong match. Non-AI outperformed 4 months, AI led 6. Wild swings both ways.
Bottom line: when one corner of the market gets crowded, the snap-back can be violent. AI isn't dead, but the easy money got pulled. Now the question is whether this broadening holds or if we rotate right back in.
Watch how the next earnings cycle plays out. That'll tell you if this is a real shift or just a breather.
7
Boeing $BA just tanked 10%+ after missing Q3 and cutting guidance. Biggest single-day drop since April 2025.
$15 billion in market cap evaporated in one session.
When a blue-chip industrial misses and lowers the bar, it's not just about one quarter. It's a signal that demand, production, or both are weaker than expected. Defense and commercial aviation are both cyclical—when they soften, it shows up fast in the stock price.
This kind of move often precedes broader sector weakness or a reassessment of growth expectations across industrials. Watch how peers like $RTX and $LMT react in coming days.
31
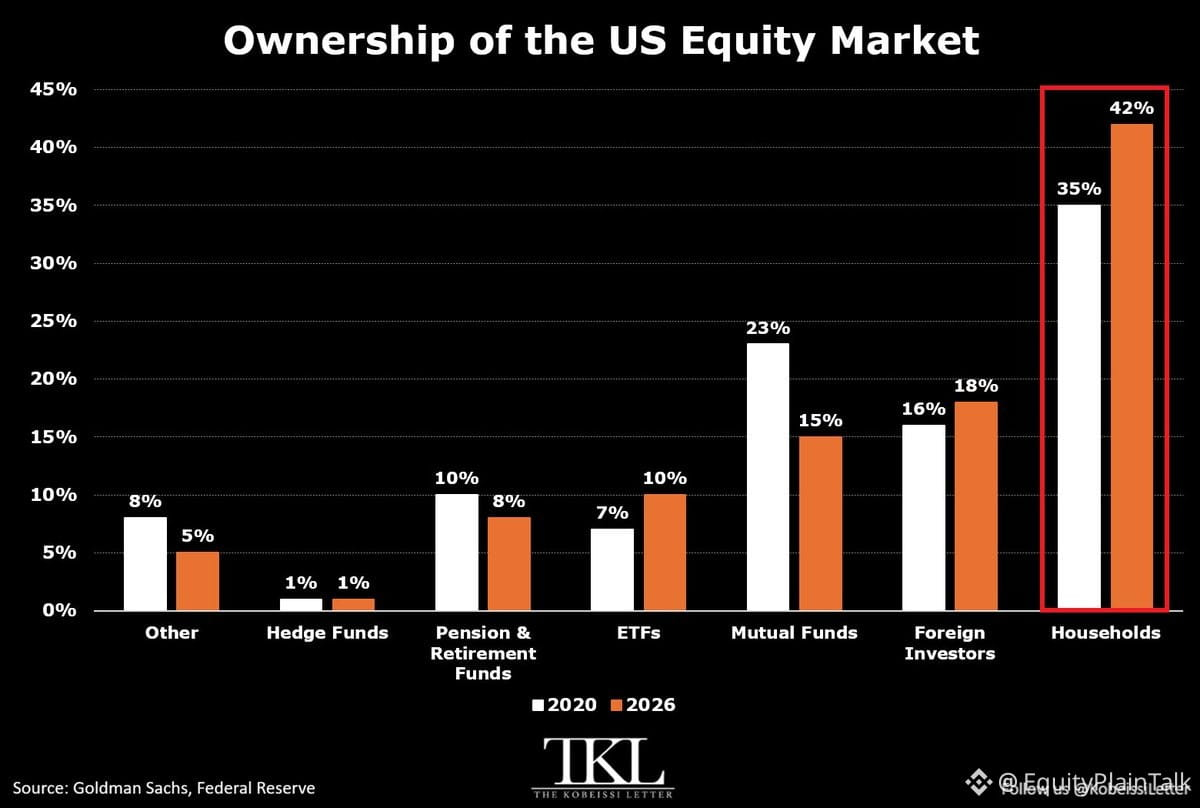
US households now own ~42% of the equity market—highest since the late 1990s. That's a +7 point jump since 2020.
Foreign investors hold 18%, up from 16% in 2020. Mutual funds dropped hard, from 23% to 15%.
ETFs? Up to 10%, a record. Pension funds at 8%. Hedge funds? Just 1%.
Retail appetite for stocks is as strong as it's been in decades. The shift from mutual funds to ETFs and direct ownership is real. Household conviction is back in a big way.
187
Post-midterm years have been historically kind to stocks.
Since 1950, the $SPY has averaged +17.2% in the year after midterms—the best performance in the entire presidential cycle. It's finished positive in 17 out of 19 times.
That's almost 4x the +4.6% average return during midterm years themselves, which only saw gains in 11 of 19 years.
For context, presidential election years (Year 4) average +8.1%, with 16 of 19 positive.
Even Q4 of midterm years tends to be strong—averaging +6.6%, the best quarterly return in the cycle.
History doesn't guarantee anything, but the pattern is clear: markets tend to breathe easier once midterm uncertainty lifts.
181
Partly True
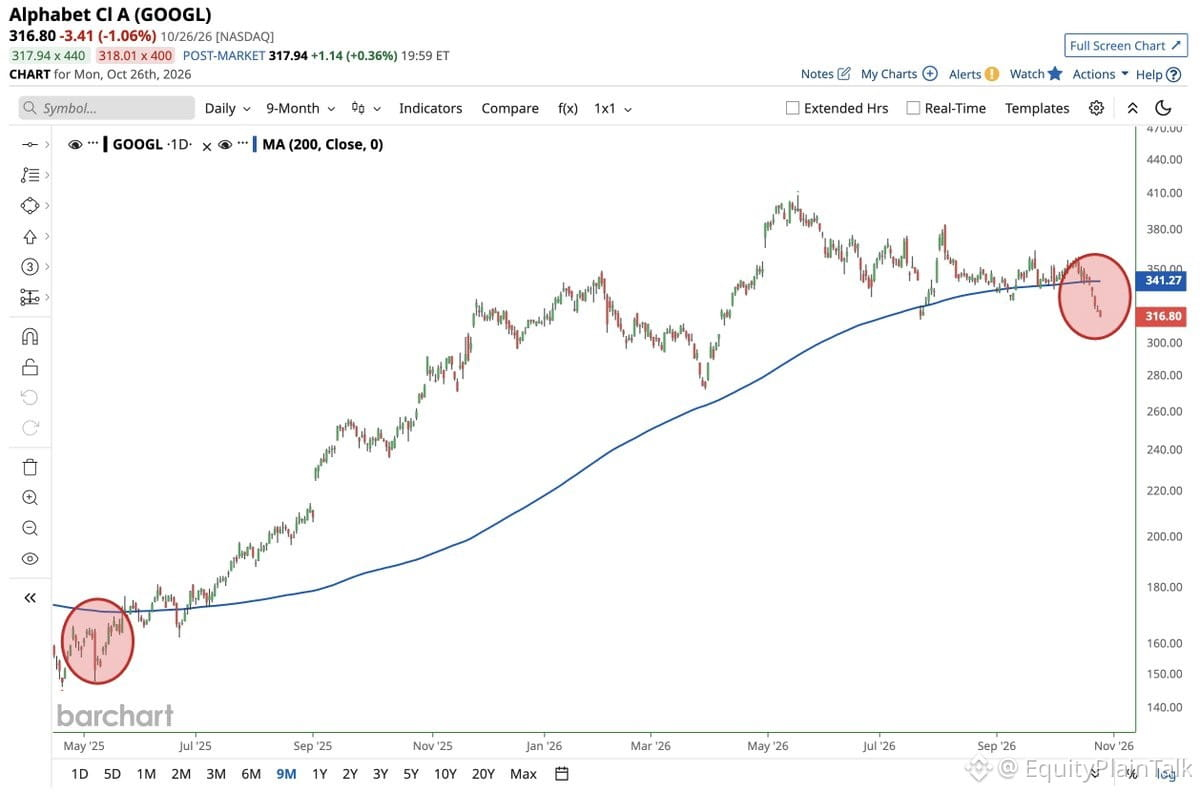
$GOOGL just broke below its 200-day moving average by the widest margin we've seen in a year and a half. That's a meaningful technical breakdown.
When a mega-cap tech name like Alphabet falls this far below a key long-term trend line, it usually means one of two things: either the market's pricing in real trouble ahead, or we're setting up for a solid entry if fundamentals hold.
Google's still printing cash, search dominance intact, cloud growing. But the Street's clearly worried about something—AI competition, regulatory pressure, or just rotation out of big tech.
Watch how it behaves around this level. If it bounces hard, could be a shakeout. If it keeps sliding, we might see deeper support tests.
1
1.2k
Disputed
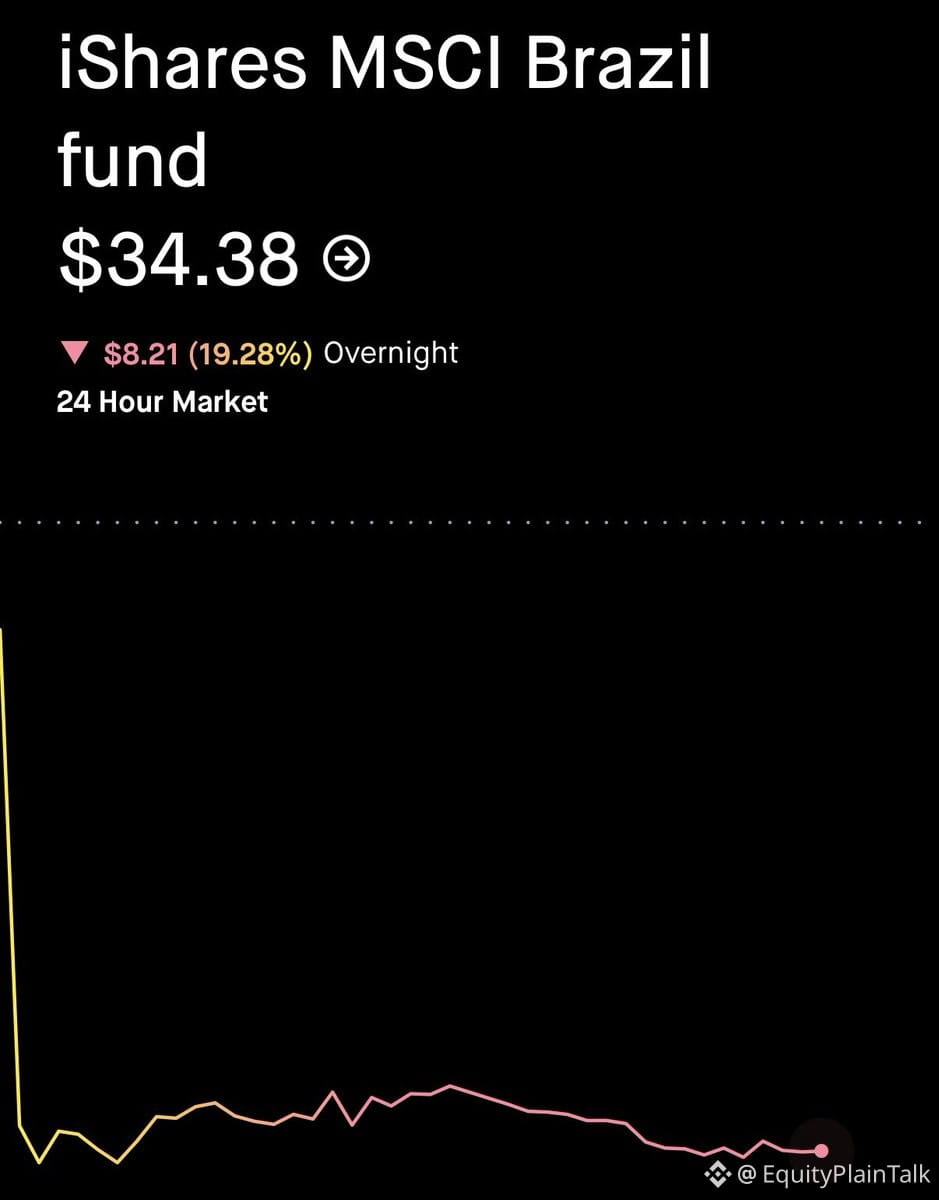
Brazilian stocks just had their second-worst day ever—down nearly 20%. That's worse than most days during the 2008 financial crisis.
For context: we're talking about a move that ranks among the most extreme equity selloffs in modern emerging market history. Only one other day was worse for Brazil.
This isn't just noise. When a major economy's stock market drops this hard in a single session, it reflects deep structural concerns—currency crisis, political instability, capital flight, or some combination.
If you hold $EWZ or have EM exposure, this is a reminder that risk in developing markets can materialize fast and violently. Diversification and position sizing matter.
3
601
Retail traders are going all-in on options right now.
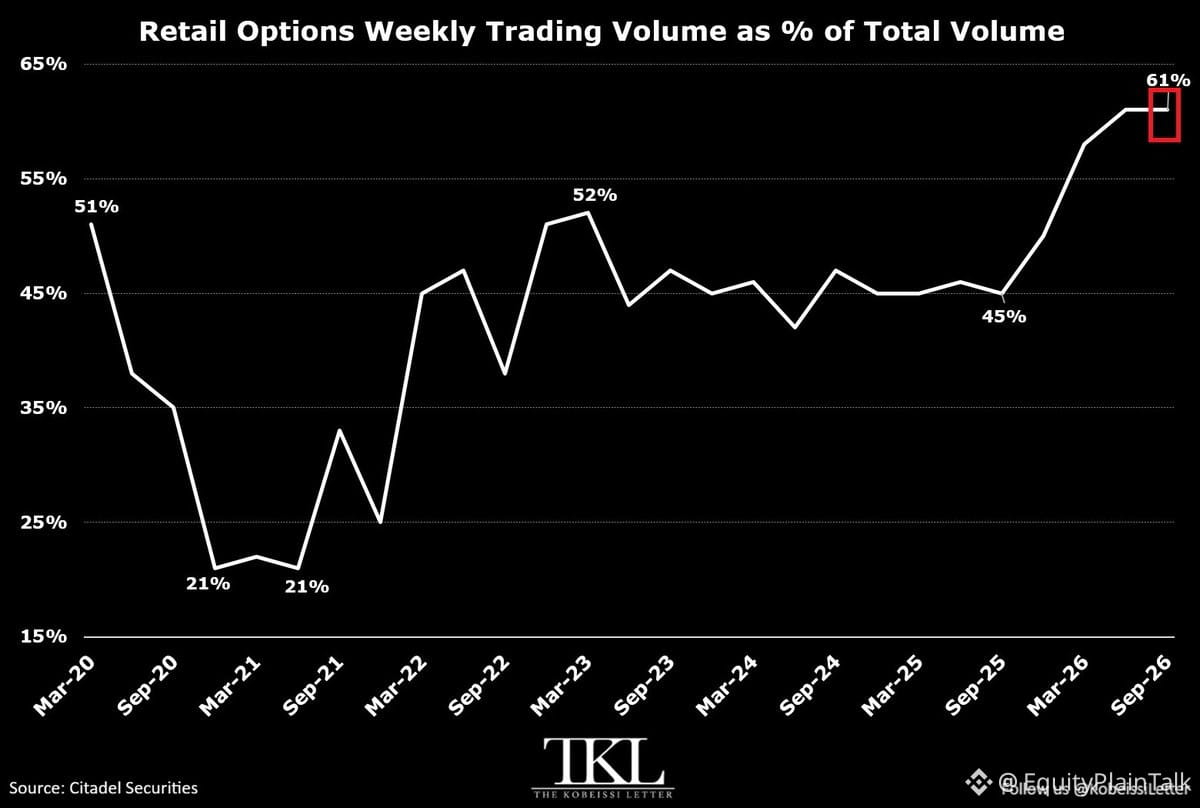
Last week, retail options hit 61% of total volume on Citadel's platform—nearly a record high. That's up 16 percentage points from a year ago and 10 points above the 2020 pandemic peak.
What's interesting: most of this action is in index and ETF options, not individual stocks. For every single-stock options contract, there are 1.7 index/ETF contracts being traded.
$SPY and $QQQ alone made up 47% of all retail options trades on Thursday.
This tells us retail isn't just gambling on meme stocks anymore. They're betting on broad market moves through ETFs—easier access, more liquidity, less single-stock risk.
But when retail options activity hits these levels, it usually signals extreme positioning. Markets can move fast when everyone's crowded on one side.
486
Retail traders are going all-in on leverage right now.
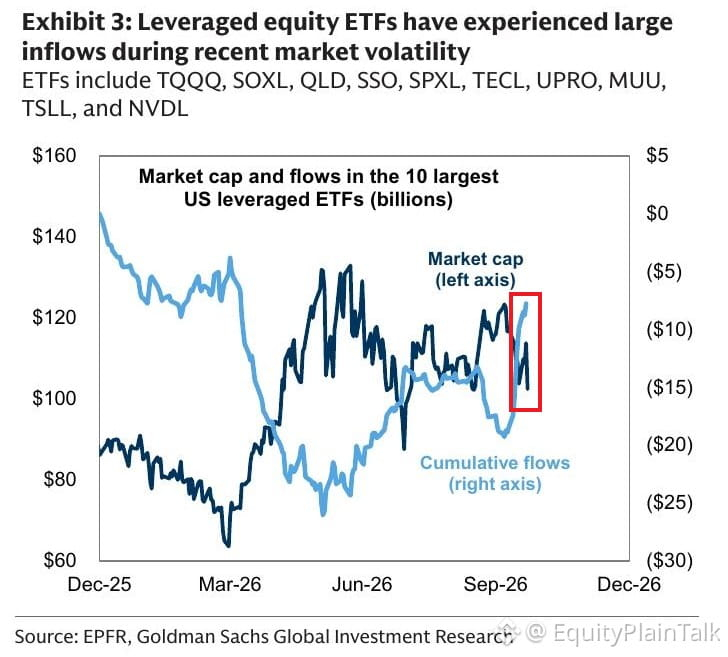
The 10 biggest leveraged equity ETFs pulled in $12 billion last month—even as their total market cap dropped $20 billion. That's fresh money chasing falling prices.
$SOXL (3x leveraged semis) alone saw $9 billion in two weeks. Record inflow. $TQQQ (3x Nasdaq) added $1.3 billion, its second-biggest intake this year.
Over five months, these funds have sucked in $19 billion.
This is classic late-cycle behavior. People aren't buying the dip—they're buying the dip with triple leverage. When everyone's reaching for max exposure at the same time, it usually doesn't end quietly.
2
1.3k
Global equity funds just pulled in $28.2B last week — their 5th straight week of inflows. That's $138.6B over 5 weeks.
Asian stocks led the charge with $11.5B, the biggest weekly haul since at least Dec 2022. Europe added $9.1B, US $5.1B.
Tech funds flipped back to positive too — $5.1B in after bleeding $4.8B the week before.
People are buying the dip. Money's moving fast and it's not sitting on the sidelines anymore.
22
Partly True
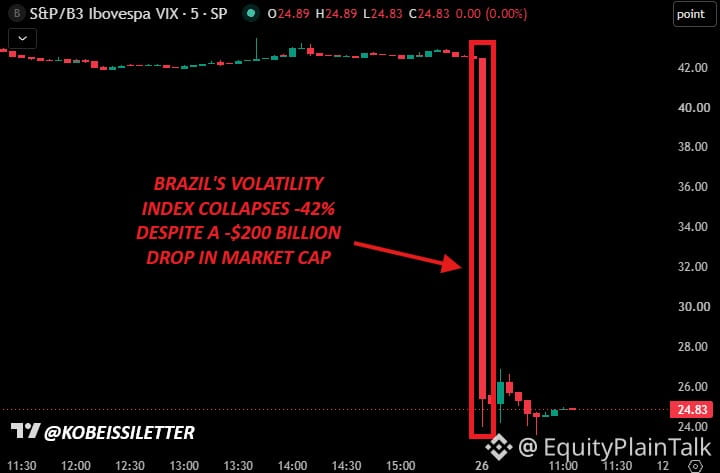
Brazil's market just dropped $200B and shed 30% after their Presidential election.
But here's the weird part: their volatility index fell 40%.
Usually when markets crash, volatility spikes. People panic, hedging demand surges, option prices explode.
But Brazil's vol is collapsing while the market bleeds.
This tells you something unusual is happening under the hood. Either:
• The crash was anticipated and already priced into options
• Implied vol was artificially inflated before the election
• Liquidity dried up so badly that vol measures broke
• Hedges are being unwound faster than new fear is building
Whatever the reason, when vol drops during a selloff, it usually means the move is orderly, not panicked. Institutions likely positioned ahead of time.
This is a textbook case of why you can't just look at price action. You need to watch how the market is moving, not just where it's going.
4
2k
Microsoft just offered buyouts to 60,000 employees—roughly 27% of their workforce.
This isn't a mass layoff. It's voluntary. But it's happening across the US, Canada, India, and UK, targeting roles from VP-level down.
The reason? Cost-cutting as AI changes how the company operates.
Microsoft has been one of the biggest AI spenders. Now they're restructuring to match that new reality. Fewer people doing traditional work. More resources going into AI infrastructure and talent.
This is the trade-off. AI doesn't just add—it replaces. And even the most profitable tech companies are making that math work.
Watch how $MSFT stock reacts. If the market sees this as efficiency, it rallies. If it reads as weakness or over-reliance on unproven AI ROI, it hesitates.
Either way, this is a signal. The AI transition isn't just about new products. It's about shrinking old cost structures.
16
Meta just announced plans to raise up to $95 billion through stock offerings to fund AI development.
This comes right after they said they'd spend up to $145 billion in CapEx this year.
That's real money. $META is betting the farm on AI infrastructure.
For context: $95B is roughly the entire market cap of companies like Starbucks or AMD. They're raising that amount just to keep pace in the AI race.
The question isn't whether AI is important anymore. It's whether these massive capital commitments will generate returns that justify the dilution and spending.
Zuckerberg is all-in. Shareholders will find out if it pays off.
342
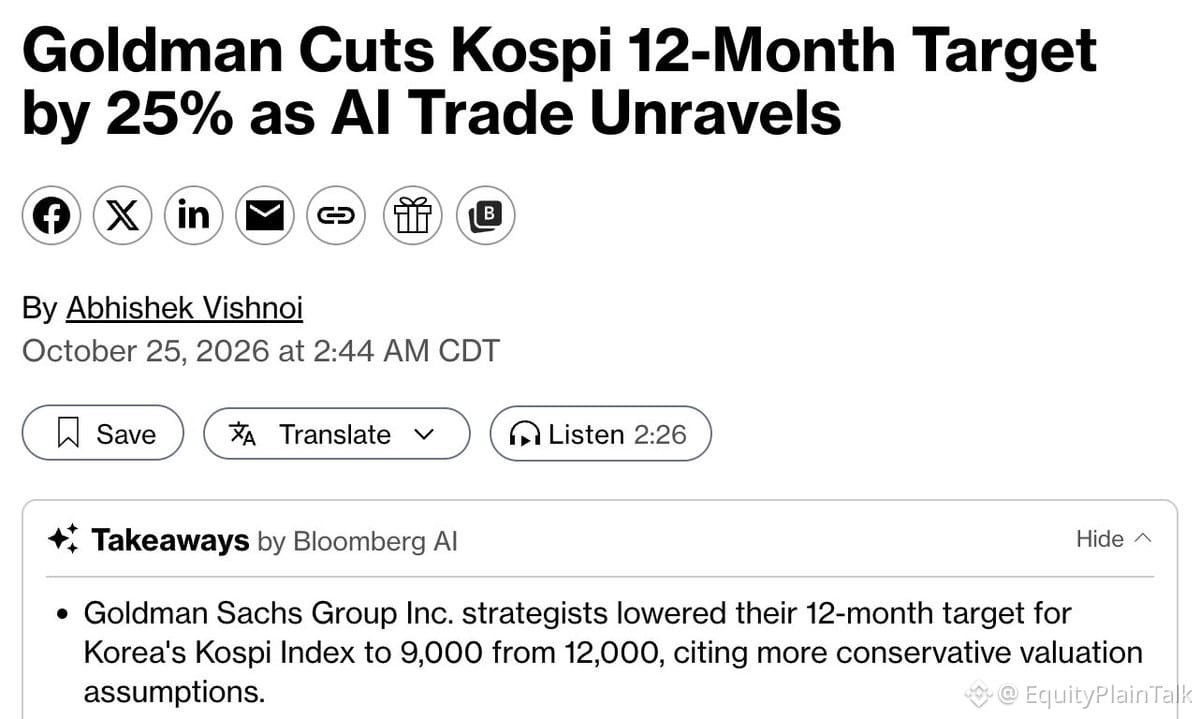
Goldman just slashed their Kospi target by 25%.
That's not a trim. That's a statement.
South Korea's been caught in the crossfire — weak semiconductor demand, China slowdown, and won weakness making things messier. The Kospi's already been underperforming most Asian indices this year.
When a major bank cuts that aggressively, it's worth watching how foreign flows react. Korean equities have been a favorite for global allocators, but sentiment's shifting.
If you're tracking Asia exposure or semis, this matters.
311
Verified
Brazilian stocks ($EWZ) are getting hammered after Lula's reelection win.
Markets don't love uncertainty, and Lula's return brings questions about fiscal policy, state intervention, and the direction of economic reforms. Investors are repricing risk in real-time.
This is a reminder that political outcomes can move markets violently, especially in emerging markets where policy shifts carry heavy weight. If you're holding exposure to Brazil, expect volatility until there's more clarity on his economic agenda.
2
1.1k
Brazil's stock market just cratered 20% after Lula's unexpected re-election win.
Markets hate uncertainty. When a left-leaning candidate wins against expectations, investors immediately price in potential policy shifts—higher taxes, more regulation, increased government spending.
This isn't about politics. It's about capital flows and risk assessment. Foreign investors pull back. Domestic money moves to the sidelines. Currency weakens. Equities get hammered.
We've seen this pattern before in emerging markets. The initial shock is often overdone. But the repricing is real. Brazilian equities were already trading at a discount to other emerging markets. Now that gap just widened.
Watch the Brazilian Real and how it impacts dollar-denominated debt. Also keep an eye on commodity exporters—Brazil is a major player in iron ore, soybeans, and oil. A weaker Real could actually help exporters over time.
Short term pain. Long term? Depends entirely on policy execution and whether Lula can reassure markets he won't wreck the fiscal situation.
181
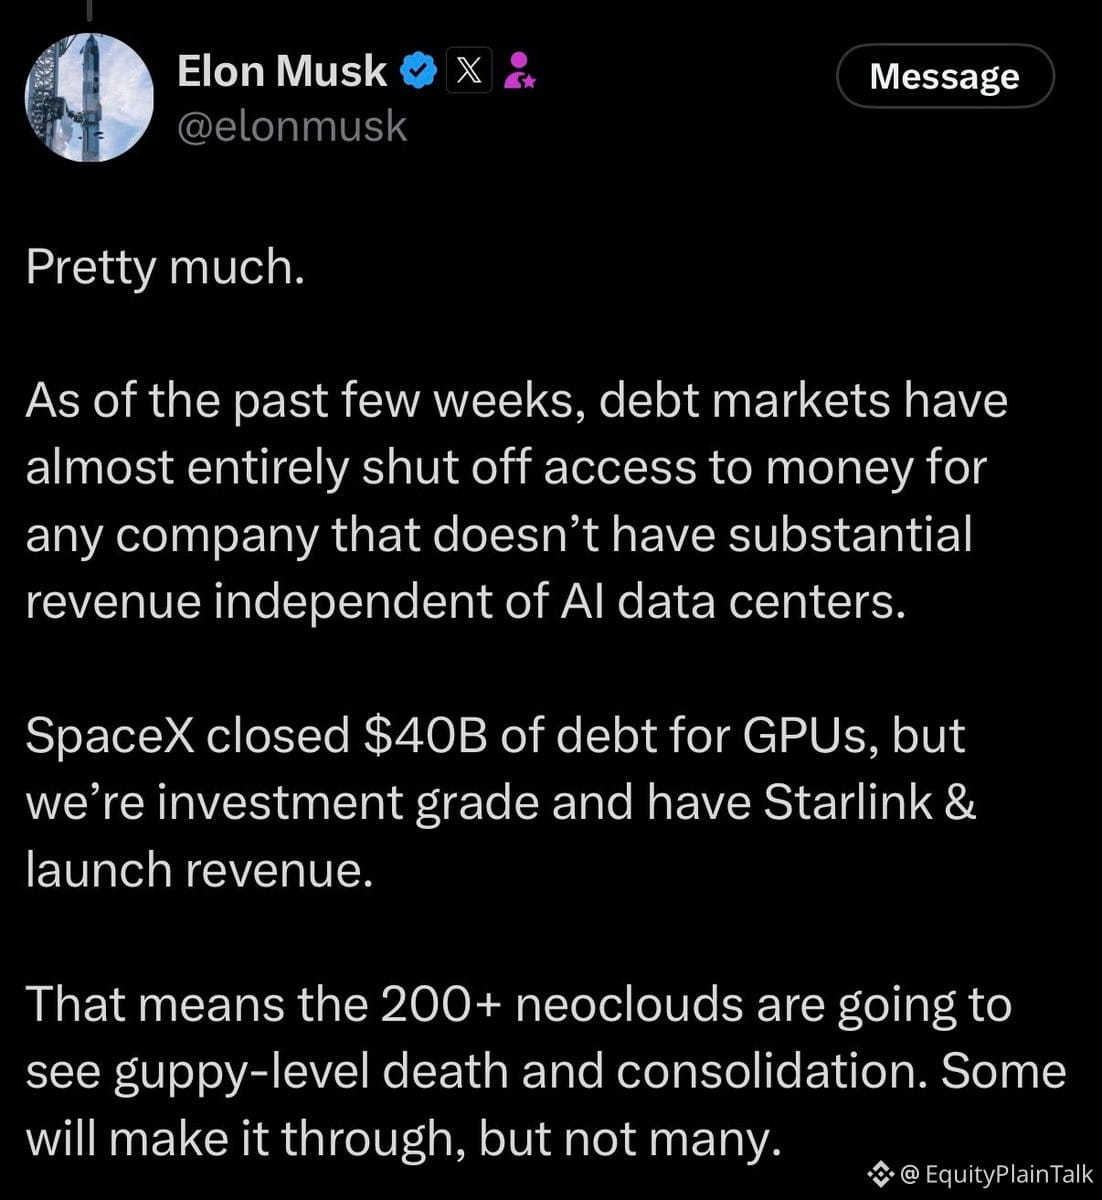
Musk just dropped a bomb: debt markets have basically frozen out any company that isn't making real money outside of AI data centers.
Translation? If you're not generating substantial revenue on your own, good luck raising capital right now.
He's predicting a bloodbath in the neocloud space—"guppy-level death and consolidation" were his exact words. Meaning the small players are about to get eaten alive or disappear entirely.
This matters because it shows how fast credit conditions tighten when the narrative shifts. A year ago, anything AI-adjacent could raise money. Now? Lenders want proof of actual cash flow.
Watch the smaller cloud infrastructure names. If they're burning cash and relying on debt to stay alive, they're in trouble. The survivors will be the ones with real revenue or deep-pocketed backers.
Credit markets don't mess around when sentiment turns.
170
Markets just exhaled. Trump says no Iran strike today, and futures immediately popped:
$SPX +0.5%
$NDX +0.7%
$DJI +0.4%
Oil reversed hard—WTI down 1.5%, Brent off 1%, natural gas dropped 2.5%. Classic risk-off unwind.
S&P 500 now just 3% from all-time highs. Geopolitical risk premium came out fast. When war fears fade, money rotates back into equities and out of energy. Simple as that.
Watch how quickly sentiment can flip on headline risk.
1
765
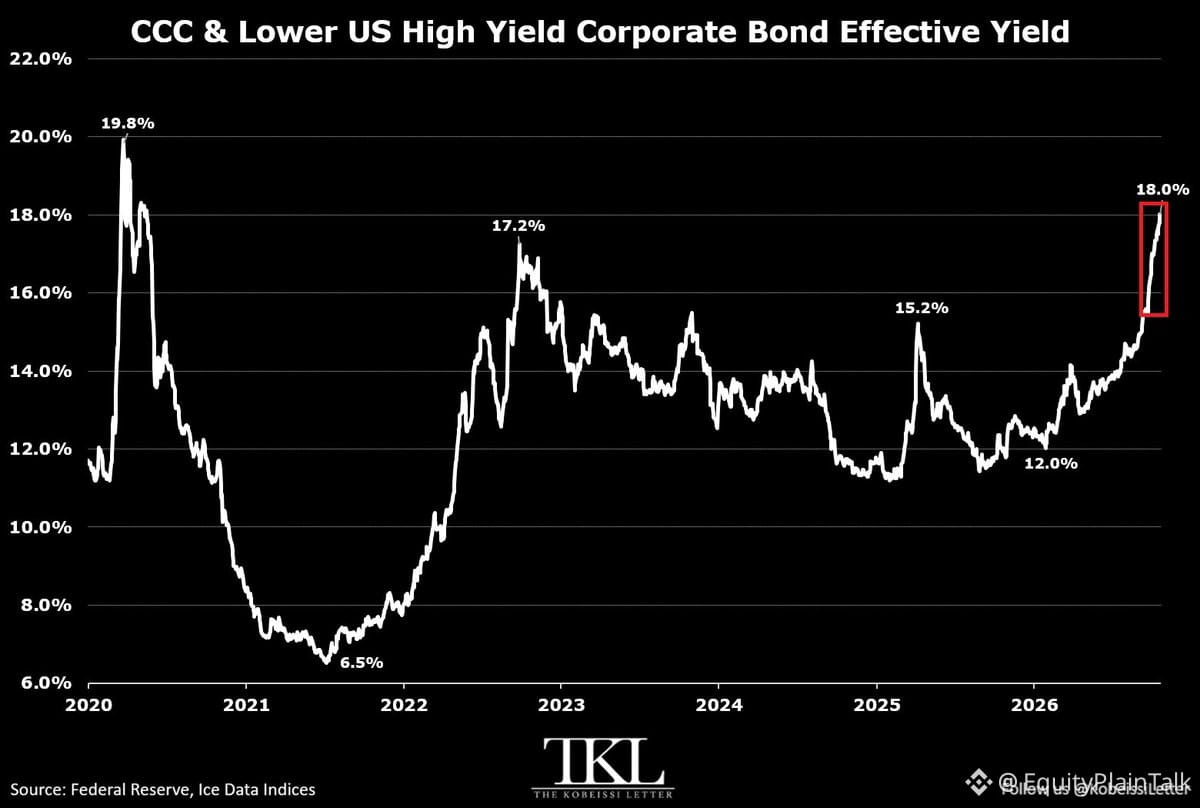
Junk bonds are flashing warning signs right now.
US CCC-rated corporate bonds are yielding 18% — highest since the pandemic crash in 2020. That's a 500 basis point jump in just 6 months, the sharpest spike since the 2022 bear market.
To put that in perspective: during the 2008 financial crisis, these yields hit 45%. We're nowhere near that, but the speed of the move matters.
Credit spreads over Treasuries have also blown out to 13.4%, wider than the 2022 peak of 12.8%. Translation: investors are demanding a lot more compensation to hold risky debt.
This isn't front-page news yet, but it's exactly the kind of thing that shows up quietly before bigger problems surface. When the lowest-quality borrowers start getting squeezed, it usually means something is breaking under the hood.
Keep an eye on this. Credit markets tend to crack before equities do.
AGGETF+0.08%
39
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number