

火星Trader
419 Posts

火星Trader
Report
Block User
美股交易分享
25 Following
710 Followers
380 Liked
Posts
All
Quotes
Live
·
--
NXP lands Volkswagen partnership—don’t mistake platform qualification for order value
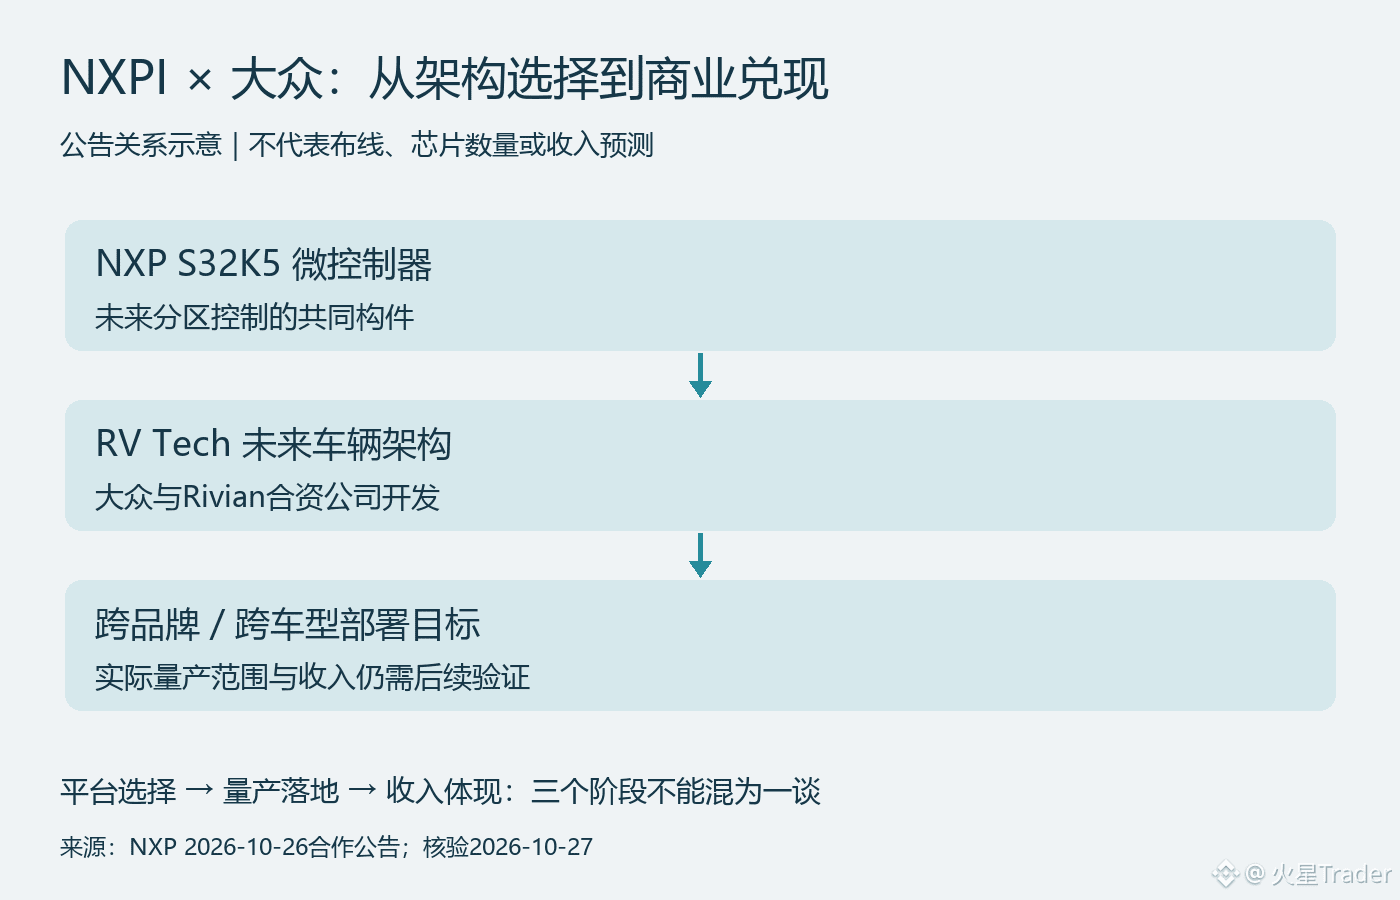
The significance of this new NXPI news is that NXP has been selected for a key component in future vehicle architectures—not that the announcement has already specified how much revenue it will generate. On October 26, Volkswagen and NXP announced a strategic partnership under which the S32K5 microcontroller will become a shared building block for future zonal software-defined vehicle architectures. The direction is worth watching, but we shouldn’t fill in the financial figures ourselves.
The announcement links this architecture to RV Tech, the joint venture between Rivian and Volkswagen, and aims to support applications across brands and vehicle models. In my view, what makes this attractive for a chipmaker is the potential for platform reuse: if the same technological foundation can be deployed across multiple models, R&D and validation investments could serve a larger production base. This is an assessment of commercial potential, not confirmation of vehicle sales or supply revenue.
But “across brands” does not mean that all of Volkswagen’s existing vehicles are already equipped with the same chip, let alone that the chip value per vehicle is certain to increase. The scope of future adoption, the number of chips per vehicle, pricing, and production ramp-up all need to be assessed separately. Without those inputs, multiplying Volkswagen’s annual sales by an imagined chip price to arrive at a supposed order value has no evidentiary basis.
Another point that can be easy to confuse is treating the entire shift to software-defined vehicles as a move to high-compute chips. The announcement specifically discusses microcontrollers related to zonal control, as well as capabilities such as real-time computing and software updates. These can be different components within the same vehicle architecture as centralized computing; this partnership cannot be described as NXP winning all of the computing chips in the entire vehicle.
For now, I view this as a positive signal for long-term design wins, but in the short term we still need to look at the earnings report. The company is scheduled to release Q3 results after the US market closes on October 27, which is early morning on October 28 Beijing time. Q3 results have not yet been released, and the partnership announcement cannot substitute for actual automotive revenue, inventory, or guidance for the next quarter. Even if management discusses the partnership, we should distinguish qualitative commentary from quantifiable contributions.
The most valuable updates to watch for are a clearer scope of adoption, confirmation of production progress, and verifiable evidence of related revenue. If there is only a partnership headline without progress toward implementation, expectations should not be repeatedly revised upward. If platform reuse genuinely expands, the long-term thesis will gradually gain support from financial data. For now, confirm the design position—don’t prematurely turn possibilities that may take years to materialize into this quarter’s profit.
Sources: NXP partnership announcement, 2026-10-26; earnings schedule announcement, 2026-10-06; verified 2026-10-27. The accompanying image illustrates the relationship described in the announcement; it is not a diagram of actual vehicle wiring or chip counts.
https://www.nxp.com/company/about-nxp/newsroom/NW-VOLKSWAGEN-STRENGTHENS-PARTNERSHIP-NXP
https://www.nxp.com/company/about-nxp/newsroom/NW-NXP-ANNOUNCES-CONFERENCE-CALL-3Q-2026
96
·
--
Lockheed Martin’s orders hit a record high, but cash realization cannot be judged by the headline alone
Lockheed Martin’s (LMT) orders are strong, but orders, revenue, and cash are three different report cards. Seeing $292 billion in backlog and immediately treating it as a profit guarantee skips the most important part: how these projects are produced, delivered, and then turned back into cash.
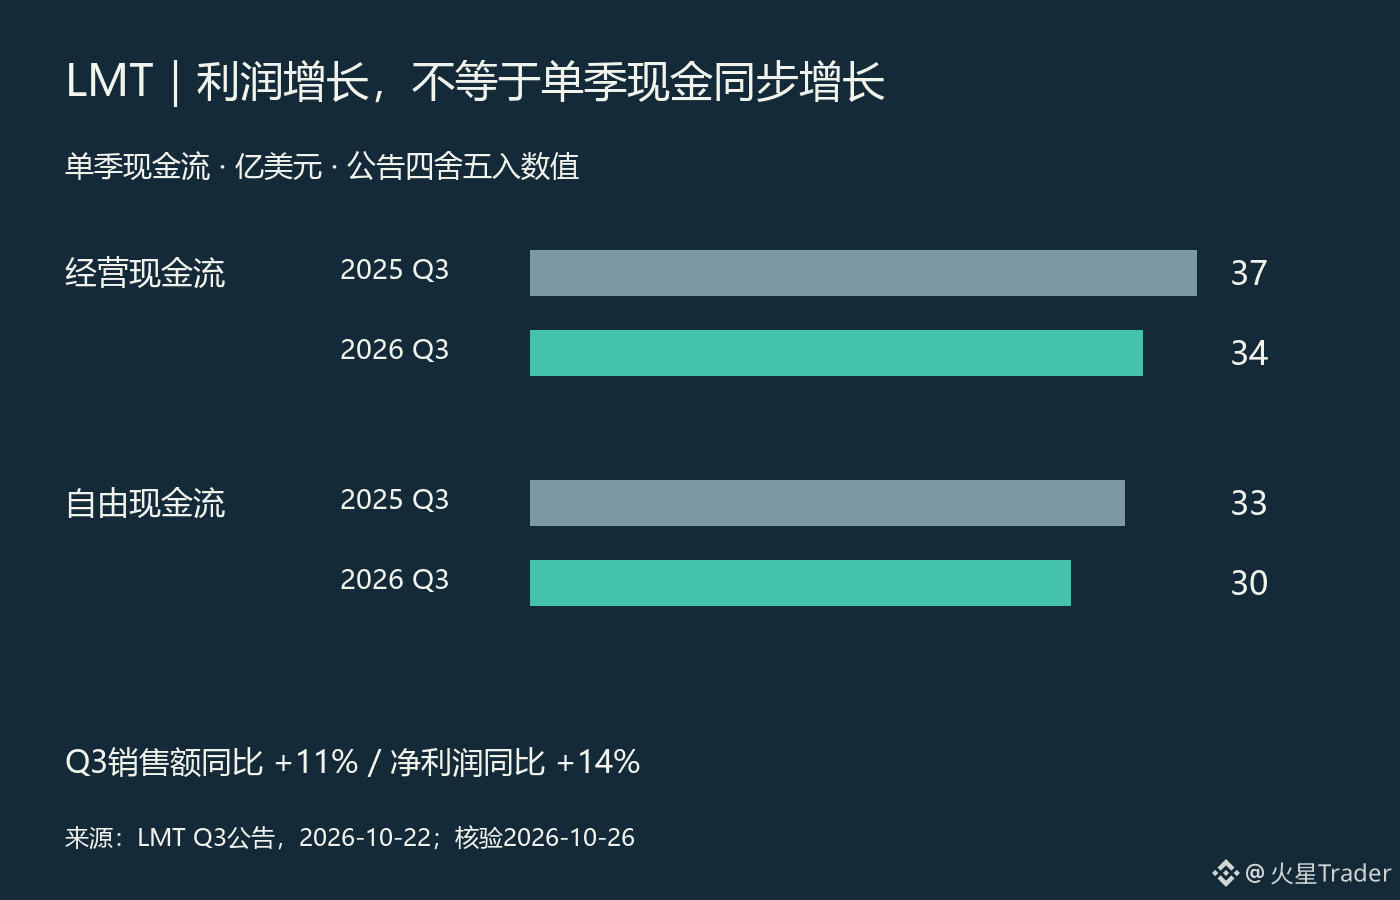
In the Q3 report released on October 22, sales were $20.7 billion, up 11% year over year; net profit was $1.8 billion, up 14%. At the same time, operating cash flow fell from $3.7 billion a year earlier to $3.4 billion, and free cash flow fell from $3.3 billion to $3.0 billion. These figures all come from the same release: profit growth and a decline in cash flow for the quarter are not contradictory, and you cannot pick one side and declare the business has clearly improved or worsened across the board.
The weight of orders also needs to be broken down. Quarter-end backlog was $292 billion, of which $52.5 billion was related to the PAC-3 MSE interceptor multiyear contract. Multiyear contracts increase visibility into future business, but they do not all turn into revenue in the quarter they are signed, and they certainly do not mean the same amount of cash has already arrived. Dividing total backlog by one quarter’s revenue and then treating the result as guaranteed growth over the next few years ignores both execution cycles and project structure.
My view is that orders solve only part of the question of whether there is work to do; realization still depends on whether the work can be completed on cost and on schedule. Capacity ramp-up, supplier deliveries, and milestone-based collections all affect the conversion pace. This is an explanation of the analytical framework, not a claim that the company had a specific delivery failure this quarter; a year-over-year decline in cash flow alone cannot accurately identify the cause.
Likewise, free cash flow of $3.0 billion is still positive, so the decline should not be described as a cash crunch. A more useful observation is whether deliveries and cash in the next few quarters can move along with revenue, rather than demanding that every quarter’s cash growth rate perfectly match profit.
I would place the next round of verification on order conversion, project profitability, and cash realization. If orders keep rising but conversion is slow and cost pressure widens, then the assessment of order quality should be downgraded. If deliveries and cash catch up, then the growth is more solid. The long-term narrative for defense demand can hold, but it cannot replace a line-by-line check of a company’s operating results, nor can it automatically justify chasing the stock at current levels.
Source: Lockheed Martin 2026 Q3, quarter ended September 27; announced October 22, verified October 26. The cash flow figure in the chart refers to the quarter, while orders refer to the ending backlog; the two were not mixed into the same basis.
https://investors.lockheedmartin.com/news-releases/news-release-details/lockheed-martin-reports-third-quarter-2026-financial-results
https://www.sec.gov/Archives/edgar/data/936468/000162828026066780/ex991q32026.htm
36
·
--
CME trading volume hits a record—don’t overlook how much revenue each contract brings in
When markets are volatile, does the exchange automatically make more money? The direction may be right, but there’s a step missing: revenue from additional trading depends on the fees per contract and the product mix. CME’s Q3 earnings report is a good way to clarify this point.
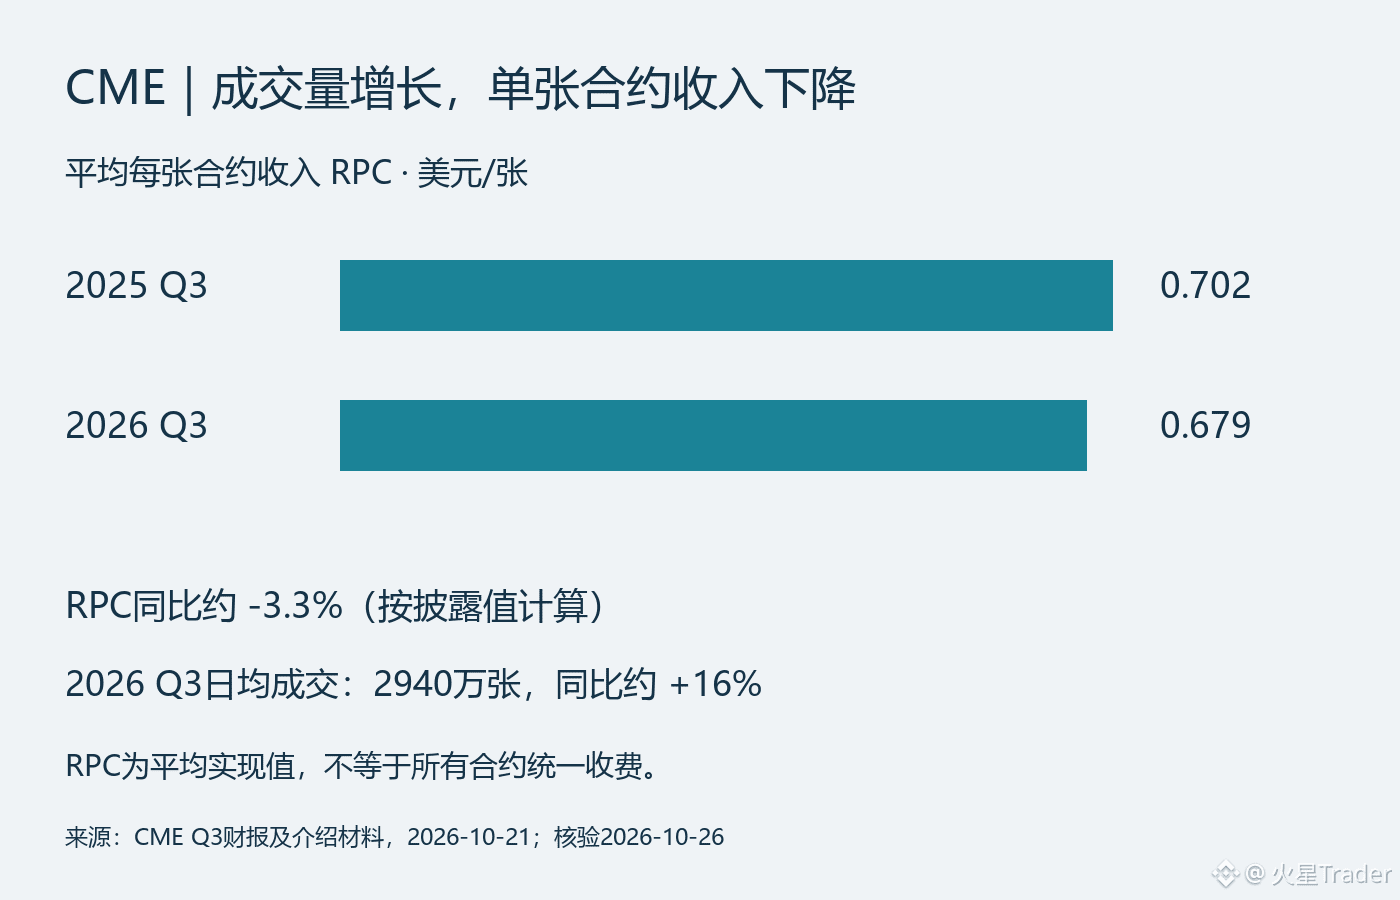
The company announced on October 21 that average daily volume in Q3 was 29.4 million contracts, a third-quarter record and up about 16% year over year. Revenue per contract (RPC) averaged $0.679, compared with $0.702 in the same period last year. Based on these two reported figures, RPC declined about 3.3% year over year. Trading can become more active while revenue per contract falls; both can happen at once, so you can’t draw a conclusion by focusing on just one of those numbers.
RPC is an average based on the actual trading mix. It does not mean the exchange lowered its listed fees across all products. Different contracts, customer types, and discount structures can all affect the average. Without a more detailed breakdown, we can’t attribute the entire decline in the average to competitive price cuts, nor assume that new trading is as valuable as existing trading.
Here’s a rough illustration looking only at volume and price: multiply the 16% increase in volume by the change in RPC: 1.16 × 0.679 ÷ 0.702, which comes to about 1.122, or an increase of roughly 12.2%. This is not a company revenue forecast or an exact reconstruction of reported revenue growth. Average daily volume also needs to be considered alongside the number of trading days, and other revenue cannot be included in this calculation. It simply shows that 16% volume growth does not automatically mean a 16% increase in trading-fee revenue.
There’s another, separate revenue stream: market data revenue reached $243 million in the quarter, up 20% year over year. This adds another dimension to the analysis, but it doesn’t justify treating the entire company as subscription software. Trading and clearing still depend on market activity, while the data business should be assessed separately for its sources of growth and how sustainable they are.
What matters more to me is how much revenue future trading growth will generate. If volume remains strong and RPC stabilizes, volume growth is more likely to translate into revenue. If volume growth slows while RPC continues to fall, “benefiting from volatility” alone won’t be enough. This is a discussion of the company’s operations; it doesn’t mean the stock must rise whenever the broader market falls. Valuation and expectations already priced in are separate questions.
Sources: CME Q3 2026; announcement dated 2026-10-21; verified 2026-10-26. RPC and average daily volume are quarterly figures; 12.2% is a simplified example in this article, not company guidance.
https://www.sec.gov/Archives/edgar/data/1156375/000115637526000065/exhibit9919302026.htm
https://investor.cmegroup.com/static-files/24c9441a-4542-4f83-803a-46fa149de4fb
https://investor.cmegroup.com/static-files/e9660b69-0368-4b23-b2ba-8a0dfb6abc57
42
·
--
It’s not enough to ask how many surgical robots are sold; we also need to see how much hospitals use them
When I look at Intuitive Surgical (ISRG), I care more about whether procedure volumes can keep pace with the expansion of its installed base. Getting a device into a hospital is only the starting point of the commercial cycle; whether it continues to be used is what matters for subsequent instrument, accessory, and leasing revenue. Q3 growth was supported by underlying activity, but new placements shouldn’t be treated as one-off sales that generate immediate cash receipts.
On October 20, the company reported that for the quarter ended September 30, global da Vinci procedure volume grew about 14% year over year, Ion procedure volume grew about 31%, and the two combined grew about 15%. You can’t simply average 14% and 31%: the platforms differ in scale, so the combined growth rate has its own weighting. In line with this, instruments and accessories revenue rose 18% to $1.8 billion, showing that revenue growth isn’t coming from systems alone.
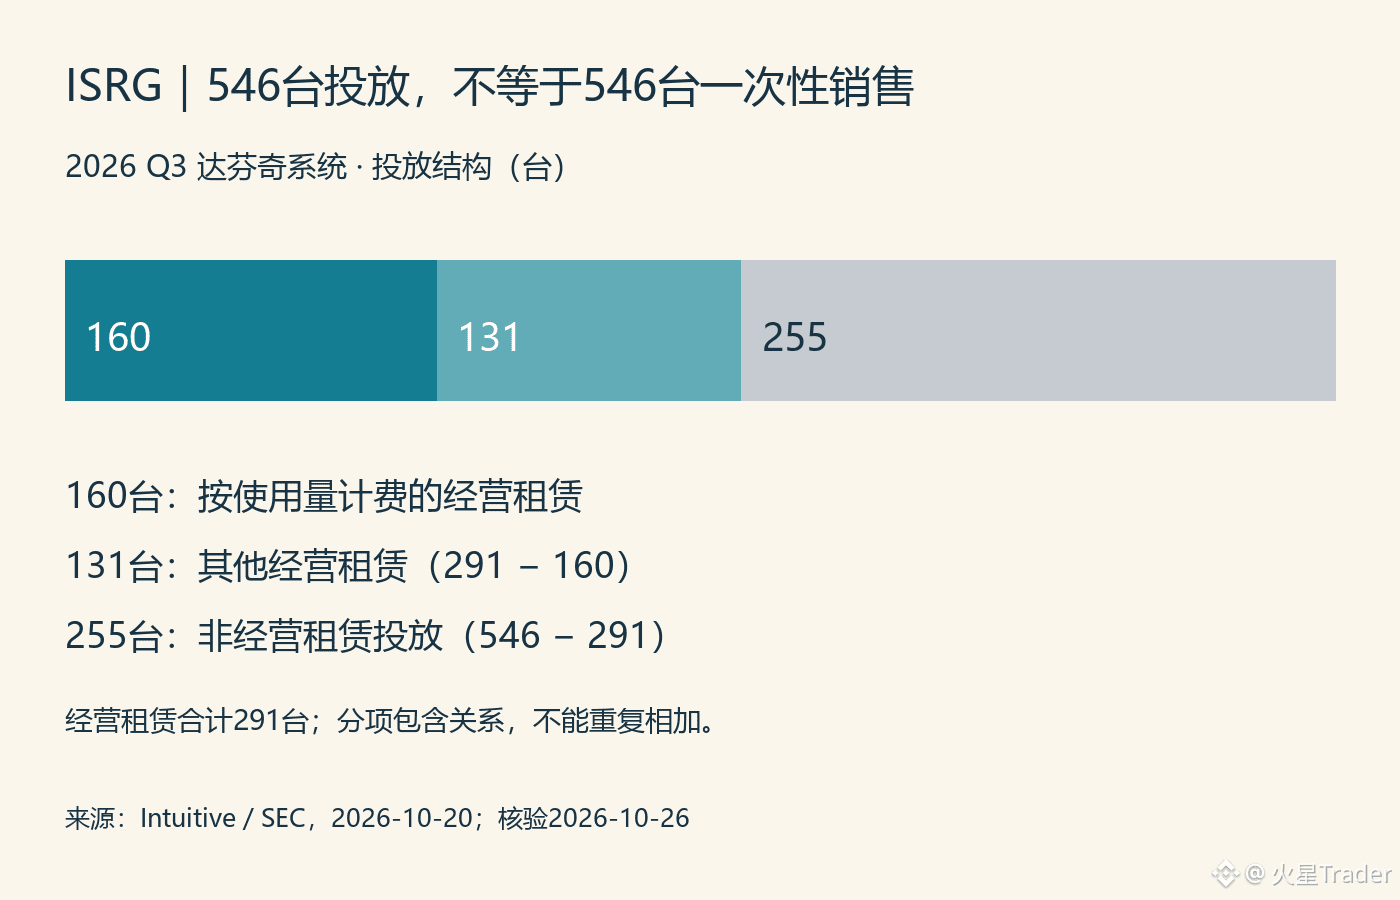
The company placed 546 da Vinci systems during the quarter, 291 of which were under operating leases; of those leased systems, 160 were usage-based. These figures are nested, not three mutually exclusive groups of machines. Since more than half of placements were operating leases, estimating quarterly system revenue by multiplying 546 by an assumed unit price would get the revenue recognition method wrong.
My take is that leasing adds an extra layer of “usage” between system placement and revenue realization. For usage-based systems, how frequently hospitals actually use them is especially worth tracking. But quarterly procedure totals and the installed base at quarter-end alone aren’t enough to calculate the utilization rate of the same cohort of systems precisely; we would also need to account for new versus existing systems, placement timing, and differences between platforms.
This is also why I’m reluctant to characterize the company solely by its robotics theme. Ongoing procedure demand supports instrument consumption, which is a strength of the business model. If system placements expand rapidly in the future but procedure and instrument growth fail to keep up, we’ll need to check whether the devices are truly entering routine use. Conversely, a fluctuation in system placements in a given quarter doesn’t necessarily mean demand has suddenly weakened, as long as usage and subsequent revenue remain steady.
In the next update, I’ll look at placements, procedure volume, and instrument revenue together, and use the leasing mix to help explain changes. The current data supports business expansion, but it isn’t enough on its own to answer whether the valuation is attractive—and sales growth certainly doesn’t mean the share price must rise.
Sources: Intuitive Q3 2026, quarter ended September 30, announced October 20; verified October 26. The accompanying chart shows the mix of placements during the quarter, not the revenue mix.
https://www.sec.gov/Archives/edgar/data/1035267/000103526726000067/q326ex-991earningsrelease.htm
1
69
·
--
IBM’s Earnings Report: Don’t Focus Only on the Words “Software Growth”
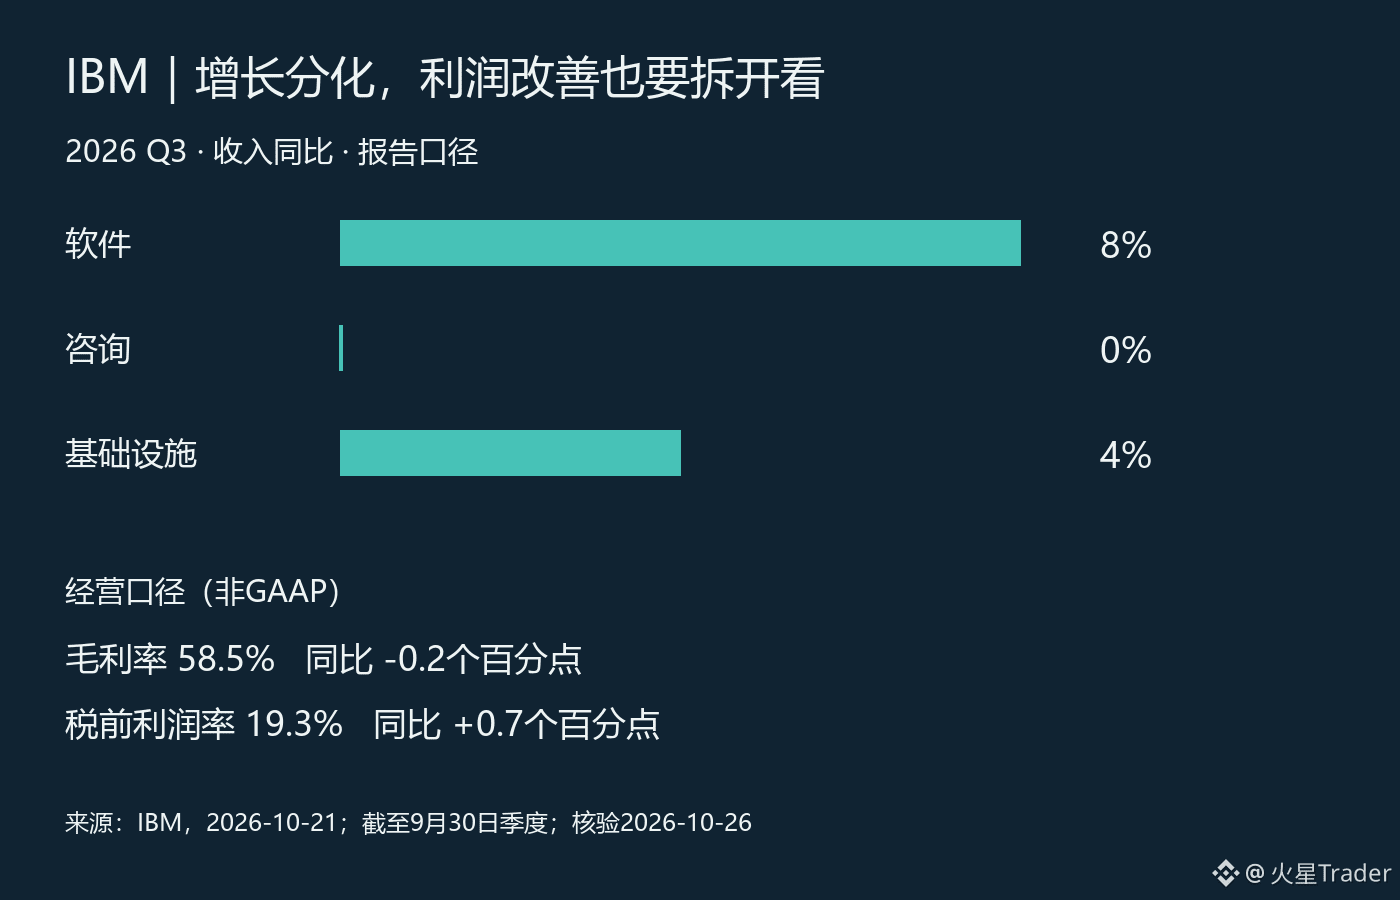
IBM’s Q3 showed improvement, but not every business is moving upward together. What matters more to me is that software is driving growth, while consulting has yet to show a clear pickup; and improved profitability does not mean gross margin has strengthened. Separating these two points makes it easier to see where the company’s earnings are coming from right now.
In the quarterly results announced on October 21, total revenue was $17.1 billion, up 5% year over year, or 6% at constant currency. Software revenue grew 8%, consulting was flat, and infrastructure grew 4%; the latter three figures are all on a reported basis. Results also varied within software: Data grew 19%, while Automation declined 3%. The headline figure for “software growth” masks two very different business conditions.
My view is that it is more appropriate, for now, to see IBM’s growth as reflecting a divergence in its business mix—not as proof of a broad recovery in corporate technology budgets. Stronger software sales do not necessarily mean customers are also increasing spending on implementation, transformation, and consulting; of course, these segment growth rates alone are not enough to conclude that customers are cutting budgets either. To confirm that demand is broadening, we will need to see consulting revenue continue to catch up in subsequent quarters, rather than relying only on management’s technology narrative.
There is also a contrast in profitability. On an operating, non-GAAP basis, pretax margin rose to 19.3%, improving 0.7 percentage points year over year; yet gross margin on the same basis fell 0.2 percentage points to 58.5%. So the improvement in pretax margin cannot be directly taken to mean that the company has gained greater pricing power for its products. Expense efficiency, business mix, and adjusting items all need to be examined separately; don’t conflate margins at different levels. The operating measure also does not replace GAAP results.
Cash flow provides another source of support: the company raised its full-year free cash flow outlook to an increase of more than $1 billion year over year, while maintaining its expectation for full-year revenue growth of 4% to 5% at constant currency. This looks more like an improvement in expected cash realization than a broad increase in the company’s full-year revenue target.
For now, I’m inclined to acknowledge the improvement, but not extrapolate it into a broad-based acceleration. Next quarter, I’ll be watching three things: whether consulting catches up with software, whether the weaker areas within software narrow the gap, and whether gross margin stabilizes. If the only improvement is in expense efficiency, the growth story will need more evidence; if demand broadens and earnings quality improves alongside it, the outlook would merit an upgrade. This is an operating performance analysis and should not be taken as a claim that the current valuation is cheap or that the share price is bound to rise.
Source: IBM Q3 2026, quarter ended September 30; results announced October 21; verified October 26. All percentages are year over year, with the basis specified where relevant.
https://newsroom.ibm.com/2026-10-21-IBM-RELEASES-THIRD-QUARTER-RESULTS
74
·
--
Coca-Cola Q2: Sales Growth, but Asia’s Price/Mix Still a Drag
As of October 25, Coca-Cola’s latest quarterly report is not Q3, but Q2, which was announced on July 28; Q3 is due before the opening of the U.S. stock market on October 27. Right now, the key thing to watch is not the “defensive stock” label, but whether sales growth can translate into more balanced revenue quality.
The disclosed Q2 data show that global unit case volume rose 5% year over year in Q2, net revenue increased 7% to $13.4 billion, and organic revenue grew 6%; price/mix contributed 2%, while concentrate sales contributed 4%. Comparable EPS was $0.97, up 11% year over year; comparable operating margin was 35.6%, versus 34.7% a year earlier. The company said it gained value share in the overall nonalcoholic ready-to-drink beverage category during the quarter.
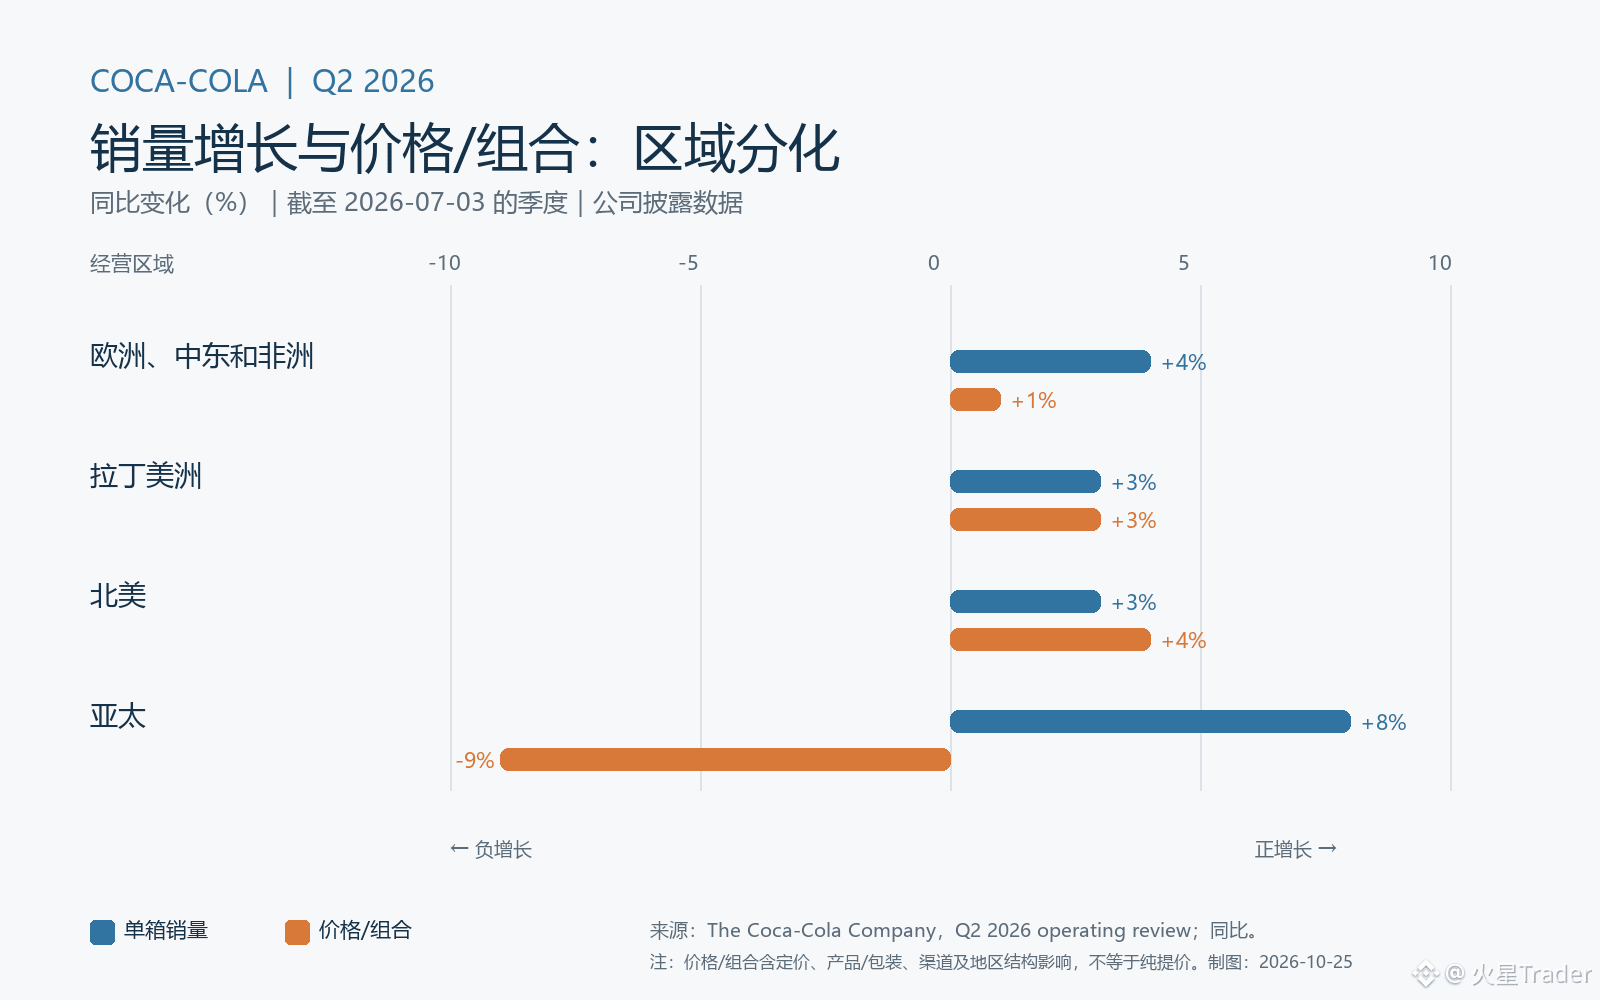
Regional data showed a clear contrast: Asia Pacific unit case volume grew 8%, but price/mix fell 9%. The company explained this was mainly due to unfavorable mix and affordability actions, and it lost value share in India; North America volume rose 3% and price/mix increased 4%, while Latin America also posted 3% growth in both. This shows that growth is not only about how many cases are sold, but also what products, what markets, and what price points they are sold at. In Asia, a more affordable mix was used to drive volume; in the short term this can help preserve consumer reach, but it may also dilute revenue per case. This is an interpretation of the regional data, not a profit forecast given by the company.
My view is that Q2 shows the brand, distribution, and new products still have the ability to drive volume, but the room for “price-led growth” is uneven. The company said innovation contributed to volume growth and that comparable margin expansion was helped by organic growth, lower expenses, and currency tailwinds; at the same time, higher input costs and increased marketing spending remained offsetting factors. So the quarter’s margin improvement should not be simply extrapolated into continued expansion.
The October 27 Q3 update will be the next checkpoint: whether global volume keeps growing, whether Asia’s price/mix negative narrows, and whether the company revises its full-year outlook again. If volume remains strong but pricing deteriorates, the market will need to decide whether this is just a temporary affordability strategy or a weakening growth structure; before the results are released, Q3 figures remain unknown.
Source: quarterly period ending 2026-07-03, announced 2026-07-28; verified 2026-10-25. Price/mix is not the same as pure price increases.
https://www.coca-colacompany.com/media-center/coca-cola-reports-second-quarter-2026-results
https://investors.coca-colacompany.com/news-events/press-releases/detail/1173/the-coca-cola-company-announces-timing-of-third-quarter-2026-earnings-release
144
·
--
Apple earnings review: $2.02 EPS, first break out that $0.11
Before looking at Apple's next earnings report, I prefer to strip out the comparison base from the prior quarter first. Profit growth is a real reported result, but if it includes the help of specific items, simply copying the growth rate can easily mix improvements from different sources.
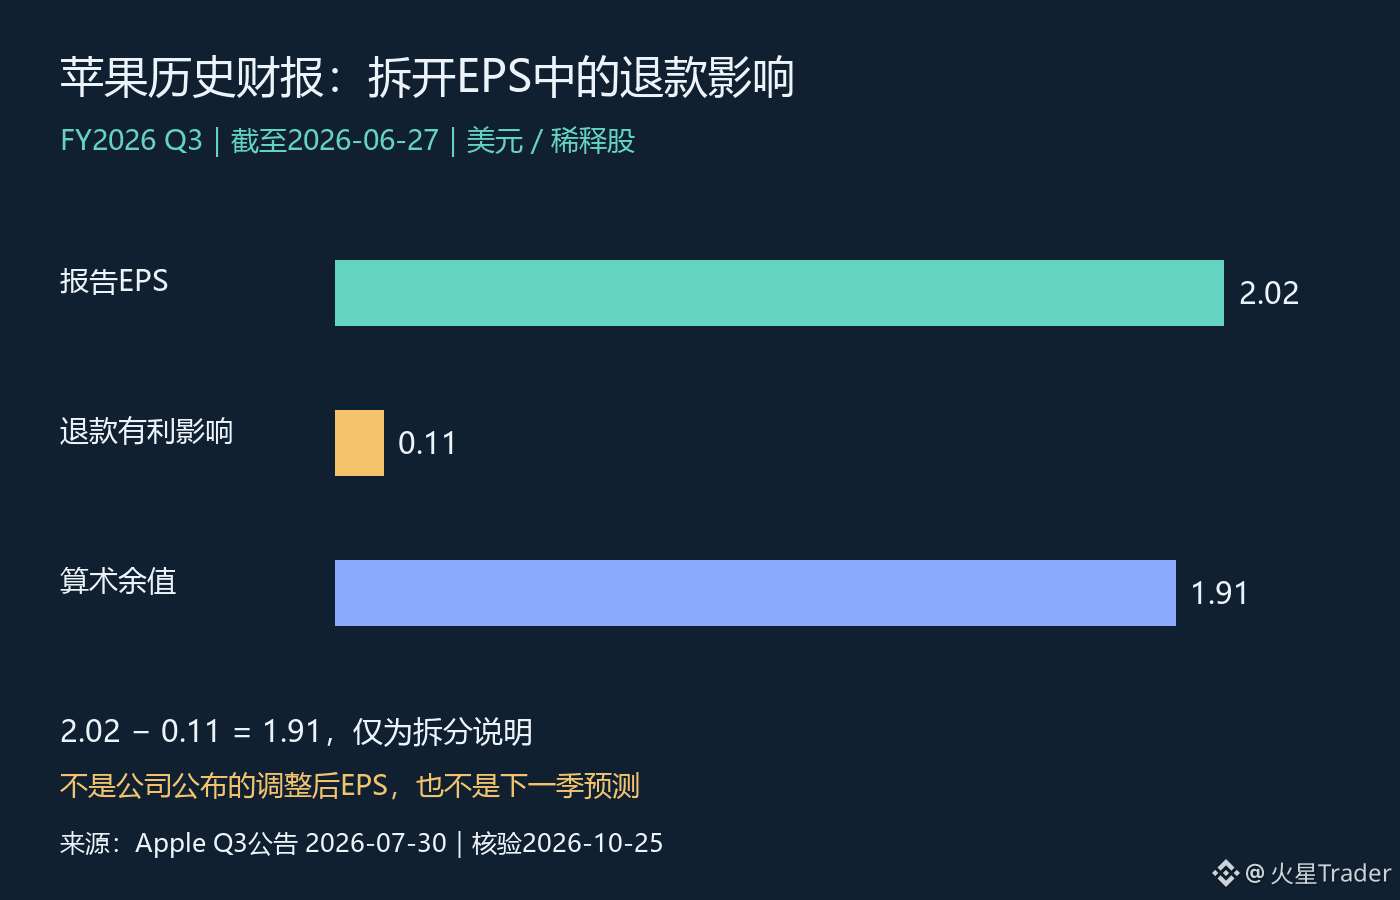
This review is of the third quarter of fiscal 2026, released on July 30 and ended June 27, not the newly announced results. Apple disclosed diluted EPS of $2.02 at the time, up 29% year over year, including a favorable impact of $0.11 per share from tariff refunds. The company's gross margin was 50.1%, also including about a 2 percentage point favorable impact from tariff refunds.
Using a simple subtraction on the disclosed figures, $2.02 minus $0.11 equals $1.91. This $1.91 is only an arithmetic figure to help understand the impact of that item; it is not another full adjusted earnings metric officially disclosed by the company, and it cannot be used directly to calculate year-over-year growth either: last year's basis, changes in share count, and other items have not been adjusted together.
This is also the step most often skipped in a review. Seeing EPS growth of 29% should not be attributed entirely to product sales or operating efficiency; seeing the refund contribution should not, in turn, negate the quarter's overall operating growth. In the same announcement, Apple disclosed revenue of $109.4 billion, up 16% year over year. Revenue and EPS each convey different information, and they should be explained by separating operating changes, cost effects, and per-share basis rather than using one figure to replace the entire judgment.
Gross margin is the same. An impact of about 2 percentage points refers to margin percentage points, not multiplying 50.1% by 2. Confusing the units may seem like a small calculation issue, but it can end up leading to a completely different assessment of profitability. Even if you roughly remove this impact, you still cannot conclude that the remaining gross margin is a level that can be maintained every quarter in the future.
For upcoming earnings reports, I will focus on whether similar favorable items continue to appear, how the product and services mix changes, and how management explains cost pressures. If new profit performance is mainly supported by operating factors rather than improvements driven by specific items, the judgment on sustainability should differ. As for whether refunds can be repeated and how large they may be in the future, this historical announcement does not provide an answer that can be directly extrapolated.
My conclusion is that good earnings analysis is not just about confirming growth in the numbers, but also about explaining where that growth came from. First keep the reported figure, then separately identify recognizable items, and finally wait for subsequent operating data to test sustainability. This article is a historical earnings review and does not include the current stock price, valuation conclusions, or unpublished earnings forecasts.
Source: Apple's Q3 FY2026 announcement, released 2026-07-30, covering results through 2026-06-27; verified on 2026-10-25. The chart is drawn using disclosed values; $1.91 is an arithmetic breakdown, not the official adjusted EPS.
Source: https://images.apple.com/newsroom/2026/07/apple-reports-third-quarter-results/
85
·
--
Microsoft’s earnings report next week: Increased AI investment does not directly prove demand is materializing
When I look at Microsoft’s AI story, I’m more interested in confirming how investment turns into customer spending than in focusing solely on the scale of that investment. Spending on infrastructure can show that the company is preparing supply; customers’ willingness to keep using and paying for it is the validation on the other side. There is a time lag between the two, as well as execution risk.
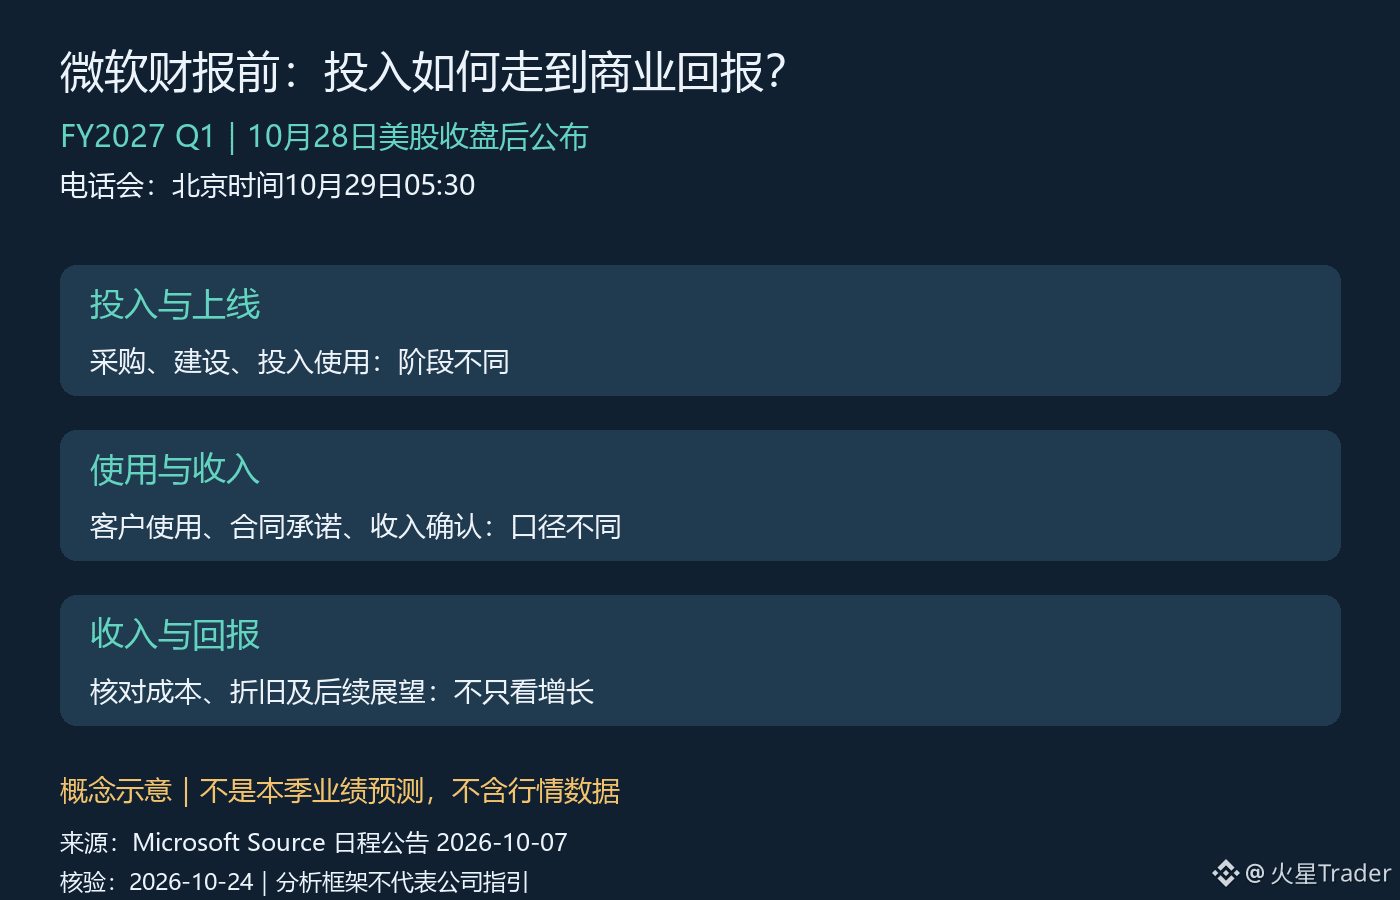
Microsoft announced on October 7 that it will report its first-quarter fiscal 2027 results after the market closes on Wednesday, October 28, U.S. local time. The conference call is scheduled for 14:30 Pacific Time. With daylight saving time in effect, that is 05:30 on October 29 Beijing time. What we can confirm now is the schedule; we cannot fill in growth rates, capital expenditures, or management guidance for an earnings report that has not yet been released.
This time, I’ll narrow the focus to the “investment–usage–returns” chain. First is the supply side: Are the new investments still in the procurement or construction phase, or have they already been put into service? If capacity is not yet online, current spending and current-period revenue cannot be mechanically matched. Increased investment alone proves neither insufficient demand nor successful commercialization; it needs to be assessed alongside the company’s disclosures on deployment timelines.
Next is the demand side. We need to verify actual revenue and management’s explanations of customer usage, rather than treating all contracts, orders, or future commitments as current revenue. If the company discloses relevant metrics, we should first examine their definitions, reporting periods, and basis of comparison before discussing changes. A business commitment spanning multiple years and a service already delivered in a single quarter cannot be measured on the same scale.
Only then comes the question of returns. Even if usage grows, the profits shareholders retain may not increase at the same pace if the costs of providing the service rise alongside it. Infrastructure depreciation, operating costs, and utilization need to be considered together with revenue. This is an analytical framework, not a claim that Microsoft has seen a particular change in costs or utilization this quarter.
In particular, avoid two conclusions drawn too quickly: seeing investment rise and deciding that AI demand has already expanded without limit; or seeing substantial cash spending and deciding that long-term returns are bound to fail. Investment and returns often span multiple periods. The real question is whether subsequent data can gradually narrow this time lag—not whether one quarter’s figures can deliver a verdict on the entire cycle.
The same applies to valuing MSFT. There is still a gap between operating growth and whether the stock is attractive: the market’s existing expectations and the price investors pay. This article has not verified the current valuation or consensus expectations, so I won’t call the stock “undervalued” or say it is “certain to beat expectations.” After the results are released, first check the evidence that demand is materializing, then examine explanations of costs and investment, and finally assess whether the forward outlook is internally consistent. Only when these pieces fit together can AI investment be more meaningfully evaluated as a source of commercial returns.
Sources: Microsoft’s official earnings announcement (2026-10-07), verified on 2026-10-24. Other than the schedule, the article presents analysis that remains to be verified; it contains no unreleased results or real-time market data. The accompanying image is illustrative.
Source: https://news.microsoft.com/source/2026/10/07/microsoft-announces-quarterly-earnings-release-date-69/
39
·
--
Nasdaq’s Earnings: Index Business Is Strong, but Don’t Treat ARR as Quarterly Revenue
You can’t analyze Nasdaq, Inc. (NDAQ) simply by applying the logic of Nasdaq index movements. It is a publicly traded company that operates financial infrastructure and related services; the index itself is a separate thing. As I review these earnings over the weekend, I’m most interested in whether growth across different businesses can reinforce one another.
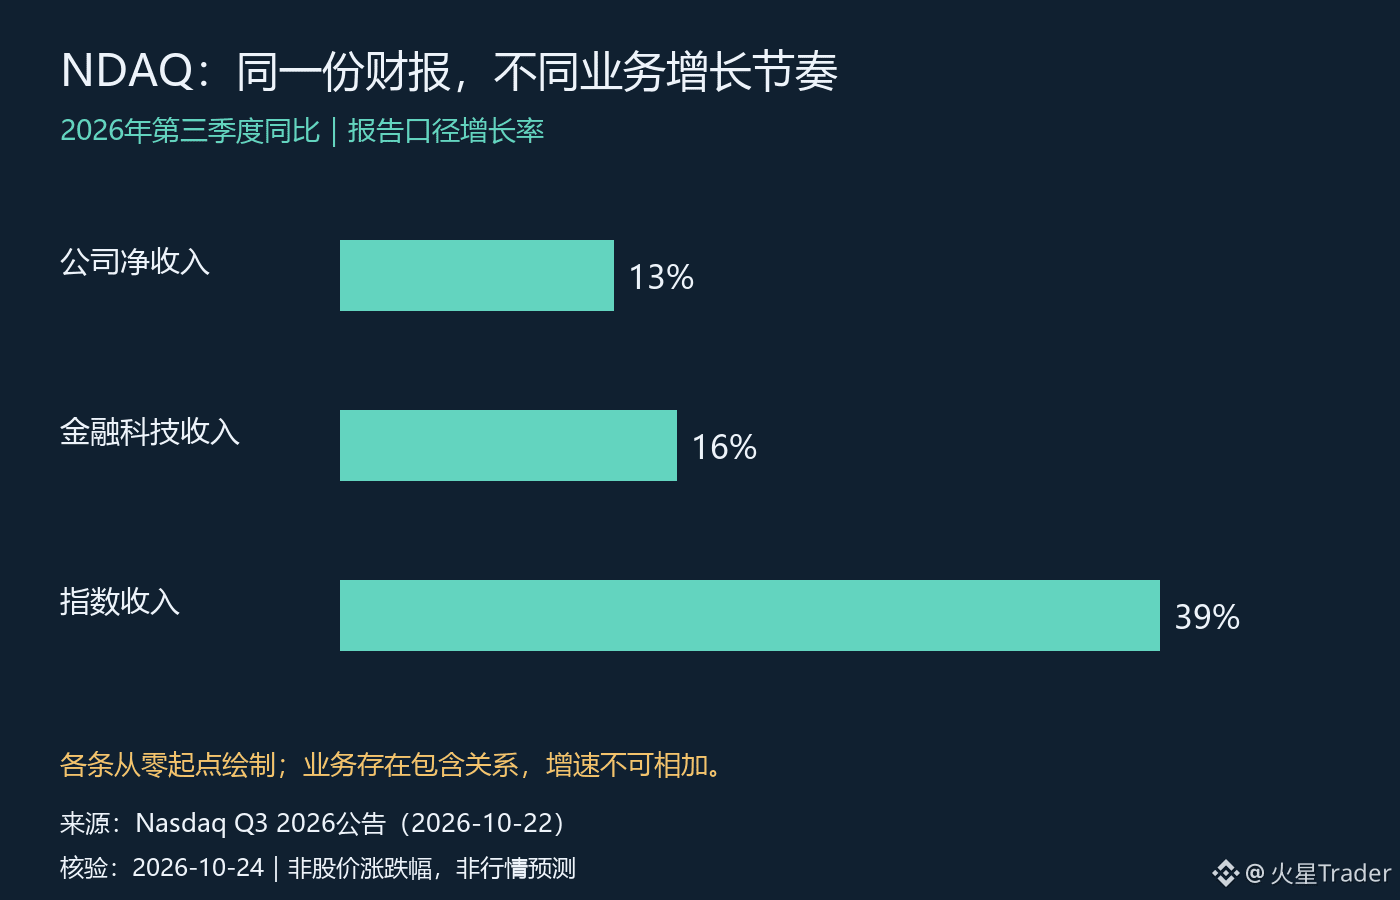
In the third-quarter results announced on October 22, the company reported net revenue of about $1.5 billion, up 13% year over year; financial technology revenue of $529 million, up 16%; and index business revenue of $286 million, up 39%. The growth rates across businesses differed markedly in the same quarter, so a single overall growth rate doesn’t tell the whole story.
The 39% growth in the index business is particularly striking, but a high growth rate doesn’t mean it was the sole source of growth. Rapid growth from a smaller base contributes differently to overall revenue than steady growth from a larger business. Analysis should consider both percentages and the amounts they represent; focusing only on the highest figure can easily lead to overestimating one business’s impact on the company as a whole.
Another figure that can be easy to confuse is ARR of $3.4 billion—the annualized recurring revenue metric—which the company said grew 12% year over year, or 14% on an organic basis. It is measured over a different time period from net revenue recognized in the current quarter. And you can’t simply add $3.4 billion to $1.5 billion to create a larger “revenue” figure. I treat ARR as an additional clue to the scale of the recurring business, then look to subsequent actual revenue and cash performance to test that picture, rather than treating an annualized figure as money already received.
Organic growth and reported growth should also be considered separately. The difference between the two measures is a reminder that overall change may not come entirely from the expansion of existing businesses. To assess the quality of growth, we still need to review the company’s explanation of its adjustments; the higher figure shouldn’t automatically be treated as the more accurate one.
My takeaway is that these results provide concrete evidence of divergent growth across the businesses: the index business has notable momentum, and financial technology is growing too. But “revenue growth” still has to pass several tests before it translates into “improved shareholder returns”—costs, investment, and valuation. If maintaining growth requires a corresponding increase in expenses as revenue expands, profit realization may follow a different timeline. The case is more convincing if expansion in recurring businesses also generates stable cash flow.
Looking ahead, I’ll be watching three things: whether the index business can sustain its rapid revenue growth; whether financial technology revenue corroborates the recurring revenue metrics; and how much of the new revenue translates into profit and cash. This article does not verify the current share price or consensus expectations, so it does not conclude that NDAQ is cheap or treat it as a proxy for the direction of the Nasdaq index.
Source: Nasdaq, Inc. third-quarter 2026 earnings release, published 2026-10-22 and verified 2026-10-24. All chart figures show reported growth rates relative to the third quarter of 2025. The businesses overlap, so their figures should not be added together; the analysis is conditional.
https://ir.nasdaq.com/news-releases/news-release-details/nasdaq-reports-third-quarter-2026-results-strong-execution
63
·
--
Weekend review: Can post-earnings after-hours moves confirm a trend?
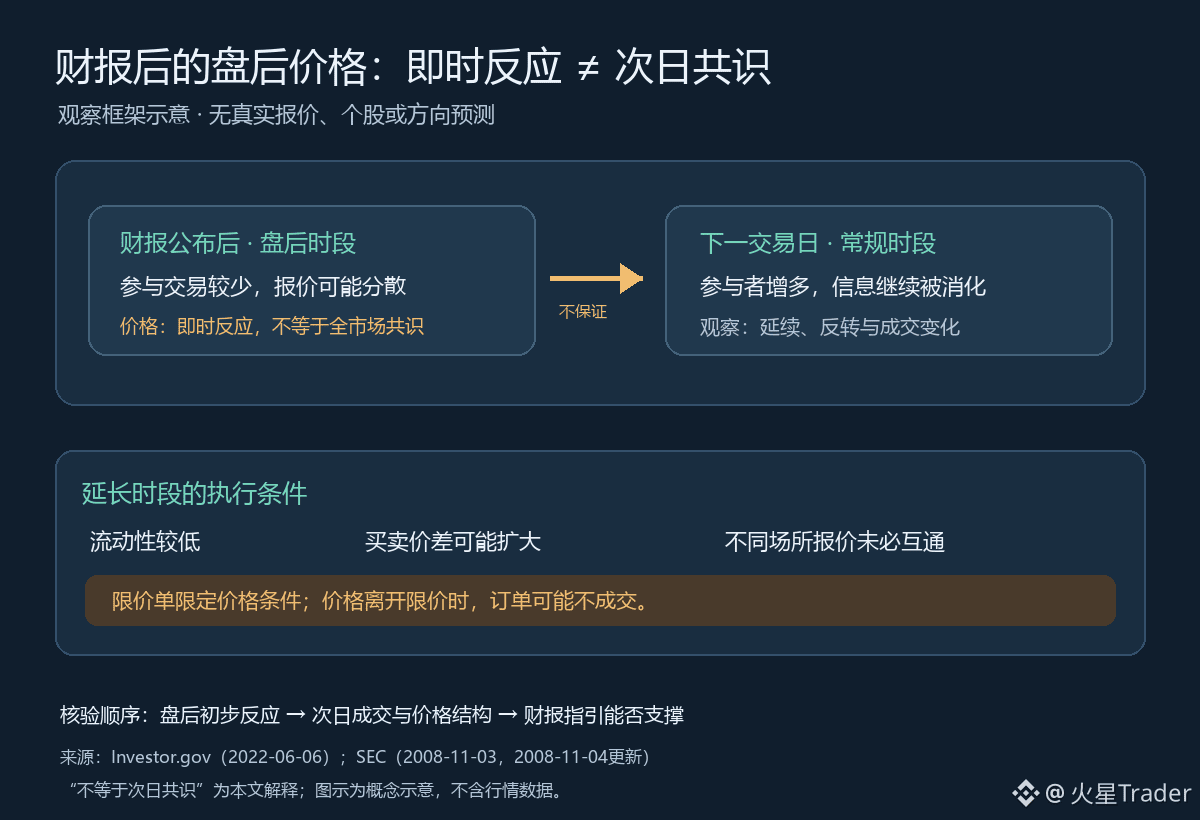
When earnings are released, after-hours prices can move immediately, making it easy to feel that the market has already given us “the answer for the next trading day.” I’d rather view this as an immediate repricing during a particular trading session: it shows how people trading at that moment responded to new information, but it cannot directly represent the market consensus on the next trading day.
The first reason is the trading environment. The U.S. Securities and Exchange Commission’s investor bulletin notes that extended-hours trading typically attracts less interest, and insufficient liquidity can make trades harder to execute and price competition weaker; the gap between bid and ask prices may also widen. Companies that release earnings outside regular trading hours may indeed see significant price moves, but after-hours prices are not necessarily the same as prices during regular trading hours—or as prices at the next business day’s open. Different trading systems may not be connected, either, so quotes shown on screen may not represent executable prices across all venues.
Second, earnings cannot be explained by a single number. Revenue, profits, guidance, cash flow, and prior market expectations can all point to different signals. An after-hours rise may mean that one result came in above expectations, or that expectations had already been low. Likewise, an after-hours drop alone cannot tell us that the long-term business outlook has reversed. This is a distinction between “price reaction” and “fundamental assessment,” not a conclusion about the performance of any specific company.
So after-hours moves are better viewed as preliminary signals that need verification, rather than as a vote on the next day’s consensus. On the next trading day, we still need to see whether prices hold once more participants enter the market, whether trading volume expands, whether bid-ask spreads narrow, and how the market digests the full earnings report and management’s guidance. If the direction reverses after the open, that after-hours jump cannot be treated as trend confirmation. If the move continues, it still needs support from operating data; conclusions should not be drawn from a single price move alone.
Orders also have limitations. Investor.gov notes that many brokerages accept only limit orders during extended hours. A limit order can set the execution price, but if the market price moves away from the limit, the order may not execute. It controls the price condition; it does not guarantee execution, much less what happens afterward. Actual rules, eligible securities, and order durations also depend on each brokerage’s arrangements.
I’d break post-earnings analysis into two steps: first, record the initial after-hours response to the new information; then wait for broader participation and subsequent guidance on the next trading day to verify it. After-hours prices contain information, but they are no substitute for tomorrow’s consensus. The accompanying image is conceptual and does not show real stocks, quotes, or forecasts.
Sources: Investor.gov, “Extended-Hours Trading: Investor Bulletin” (2022-06-06); U.S. Securities and Exchange Commission, “After-Hours Trading: Understanding the Risks” (page dated 2008-11-03, updated 2008-11-04); both rechecked on 2026-10-24. The statement that “an initial reaction cannot represent the next day’s consensus” is an interpretation of material on trading sessions, liquidity, and price uncertainty, not a direct quote from a regulatory agency. No specific company or current market conditions are discussed.
Sources:
https://www.investor.gov/introduction-investing/general-resources/news-alerts/alerts-bulletins/investor-bulletins-42
https://www.sec.gov/about/reports-publications/investorpubsafterhourshtm
85
·
--
Advanced processes account for 79% of TSMC’s revenue. Is that enough to lift valuations across the entire semiconductor sector?
TSMC is very strong in advanced processes, but I think it’s too big a leap to translate that directly into “all semiconductor companies deserve higher valuations.” Looking at U.S.-listed TSM, it’s important to separate the results the company has already delivered from how much the market is willing to pay for its future prospects.
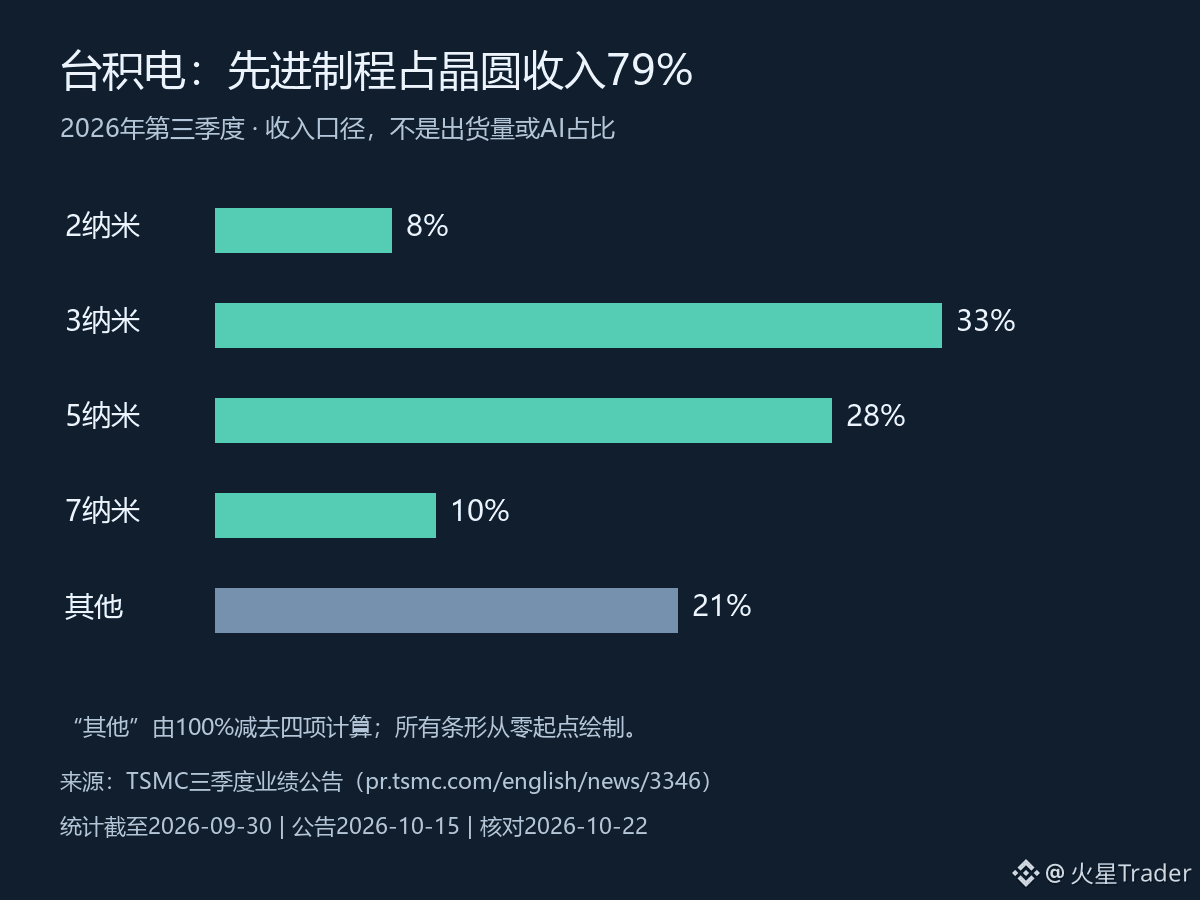
In the third-quarter results released on October 15, there was a set of figures worth unpacking rather than focusing on profit alone: 2nm, 3nm, 5nm, and 7nm contributed 8%, 33%, 28%, and 10% of wafer revenue, respectively. 7nm and more advanced processes together accounted for 79%. This is the revenue mix for the quarter ended September 30, not a real-time update on orders.
What does 79% tell us? At the very least, advanced processes have become the core of this business and can no longer be treated merely as a story about the distant future. But it does not mean that “79% of revenue comes from AI.” Process node is a measure of manufacturing technology; AI is a measure of end use. The two are not directly interchangeable.
The most common mistake here is to take one company’s strength in a particular part of the value chain and extrapolate it all the way along the chain. For design companies, the question is how much profit they retain after their products are sold. For equipment companies, it’s when customers’ capital spending turns into orders. For memory companies, supply, demand, and pricing also matter. They may all belong to the semiconductor sector, but the timing of profit realization can vary.
My view is that this revenue mix helps explain TSMC’s competitive position, but on its own it does not prove that earnings estimates across the entire sector are being revised upward. Even for TSM itself, a higher share of advanced processes does not automatically mean a more optimistic outlook: the share is a numerator divided by a denominator, so the absolute revenue scale, manufacturing costs, and returns on new capacity still need to be assessed together.
If the market has already priced in high growth expectations, strong results do not automatically mean the stock has just as much upside left. I have not verified the current share price against consensus expectations, so I won’t describe these results as having “already beaten expectations,” nor will I use them to judge whether the stock is cheap or expensive today.
The more useful next step is to see whether advanced-process revenue contributions hold up in subsequent reports, while checking gross margins and capacity investment. Then we can look at order trends and earnings guidance from related design, equipment, and memory companies to see whether each provides confirmation. Only as this evidence comes together will there be a basis for a sector-wide conclusion.
Sources: TSMC’s third-quarter 2026 earnings release, published on 2026-10-15, covering the period through 2026-09-30; rechecked on 2026-10-23. The accompanying chart was created using data from the release; “Other 21%” is calculated as 100% minus the four listed figures. The discussion of the value chain and valuations above is analysis, not company guidance.
https://pr.tsmc.com/english/news/3346
Chinese-language release for cross-checking: https://pr.tsmc.com/chinese/news/3346
1
34
·
--
The Fed meets next week: should growth stocks wait for answers or focus on expectations first?
The Fed meeting next week does not mean the market already knows the interest-rate outcome. For growth stocks, what really needs to be separated are two factors: changes in discount rates and expectations for corporate earnings. Translating “rate cuts” directly into “stocks must rise” skips a crucial condition.
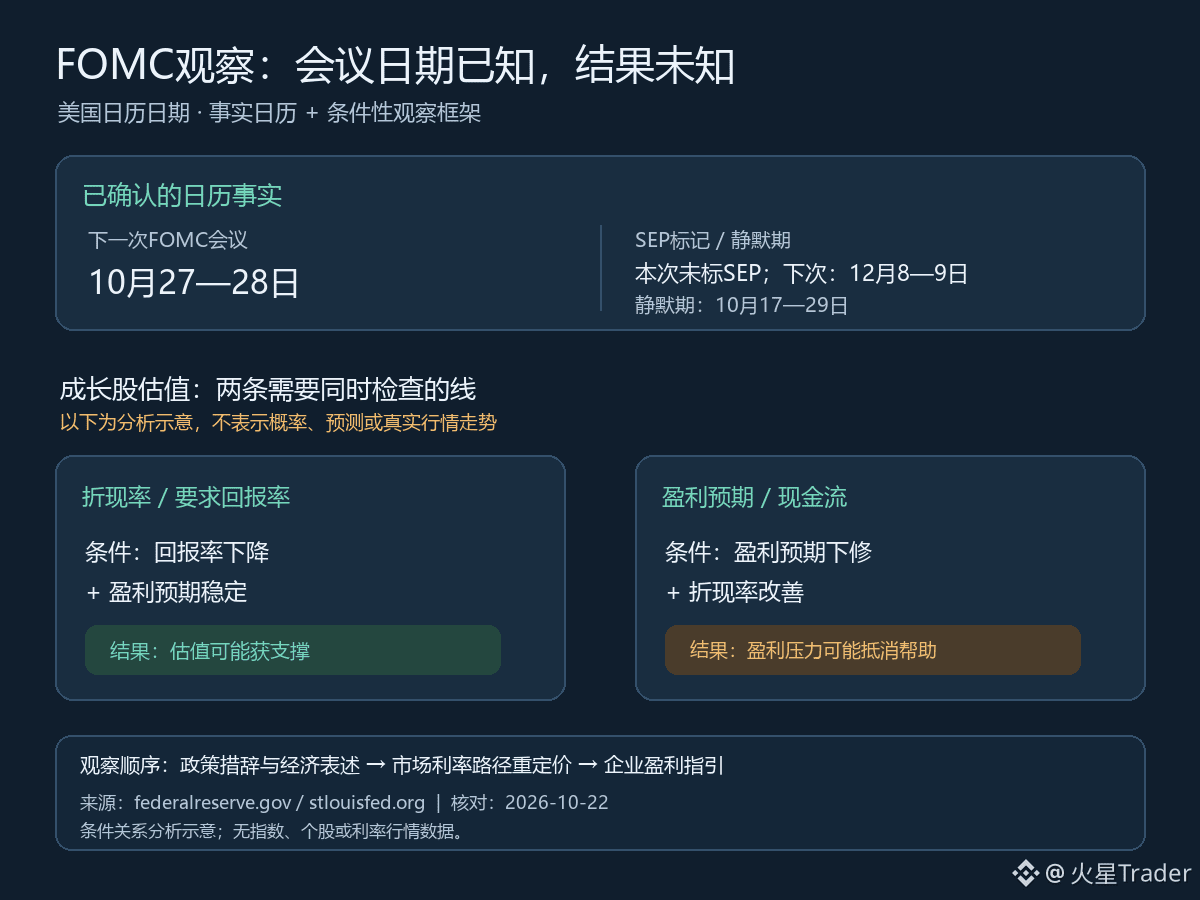
What the calendar confirms is that the Federal Open Market Committee (FOMC)’s next meeting is scheduled for October 27–28 on the U.S. calendar. The Fed’s published schedule does not mark this meeting as one that includes a Summary of Economic Projections (SEP); the next meeting marked for an SEP is December 8–9. Another verifiable time boundary is that the blackout period for Fed officials’ communications runs from October 17 through October 29. These are meeting and communications calendar details only; they do not include an interest-rate decision or conclusions about market pricing.
Growth-stock valuations are more sensitive to distant future cash flows. If the return investors require declines while expectations for companies’ future earnings remain stable, valuations may be supported. But if changes in interest rates coincide with downward revisions to earnings expectations, pressure on the cash-flow side may offset the support from lower discount rates. Conversely, even if interest rates do not move in the direction investors expect, individual stocks may still perform differently if earnings expectations strengthen. This is conditional analysis, not a prediction of the meeting’s outcome or stock-price direction.
It is also important to note that the policy rate and the discount rate used to value stocks are not the same thing. Long-term Treasury yields, risk premiums, and investors’ views on the durability of growth can all change the return investors require. Even if a policy move matches expectations, if stock prices had already priced in more easing, the actual reaction could be the opposite of what the apparent good news would suggest. This discusses the mechanics of expectation gaps and does not use any unverified current probability of rate cuts.
So, on the day of the meeting, I’ll watch the policy language, statements about the economy and inflation, and the market’s repricing of the rate path afterward as separate factors, then compare them with earnings guidance from large growth companies. A single immediate move in an index cannot prove that discount-rate dynamics are already driving the market; the word “rate cuts” alone cannot replace earnings confirmation either.
Next, I’ll first follow communications around the October 27–28 meeting, then see whether company earnings reports and guidance can sustain earnings expectations. Growth-stock valuation reactions will be easier to explain only when the direction of change in both the rate path and cash-flow expectations becomes clearer. The two paths in the illustration are a framework for observation, not a probability estimate or market forecast.
Sources: Federal Reserve FOMC meeting calendar; Federal Reserve Bank of St. Louis calendar of blackout periods for Fed officials’ communications. Both rechecked on 2026-10-23. Meeting dates are listed according to the U.S. calendar to avoid time-zone conversion ambiguity. The valuation and market-reaction discussion is conditional analysis and does not include interest-rate forecasts, current market conditions, or probability assessments.
Sources:
https://www.federalreserve.gov/monetarypolicy/fomccalendars.htm
https://www.stlouisfed.org/about-us/resources/blackout-periods
71
·
--
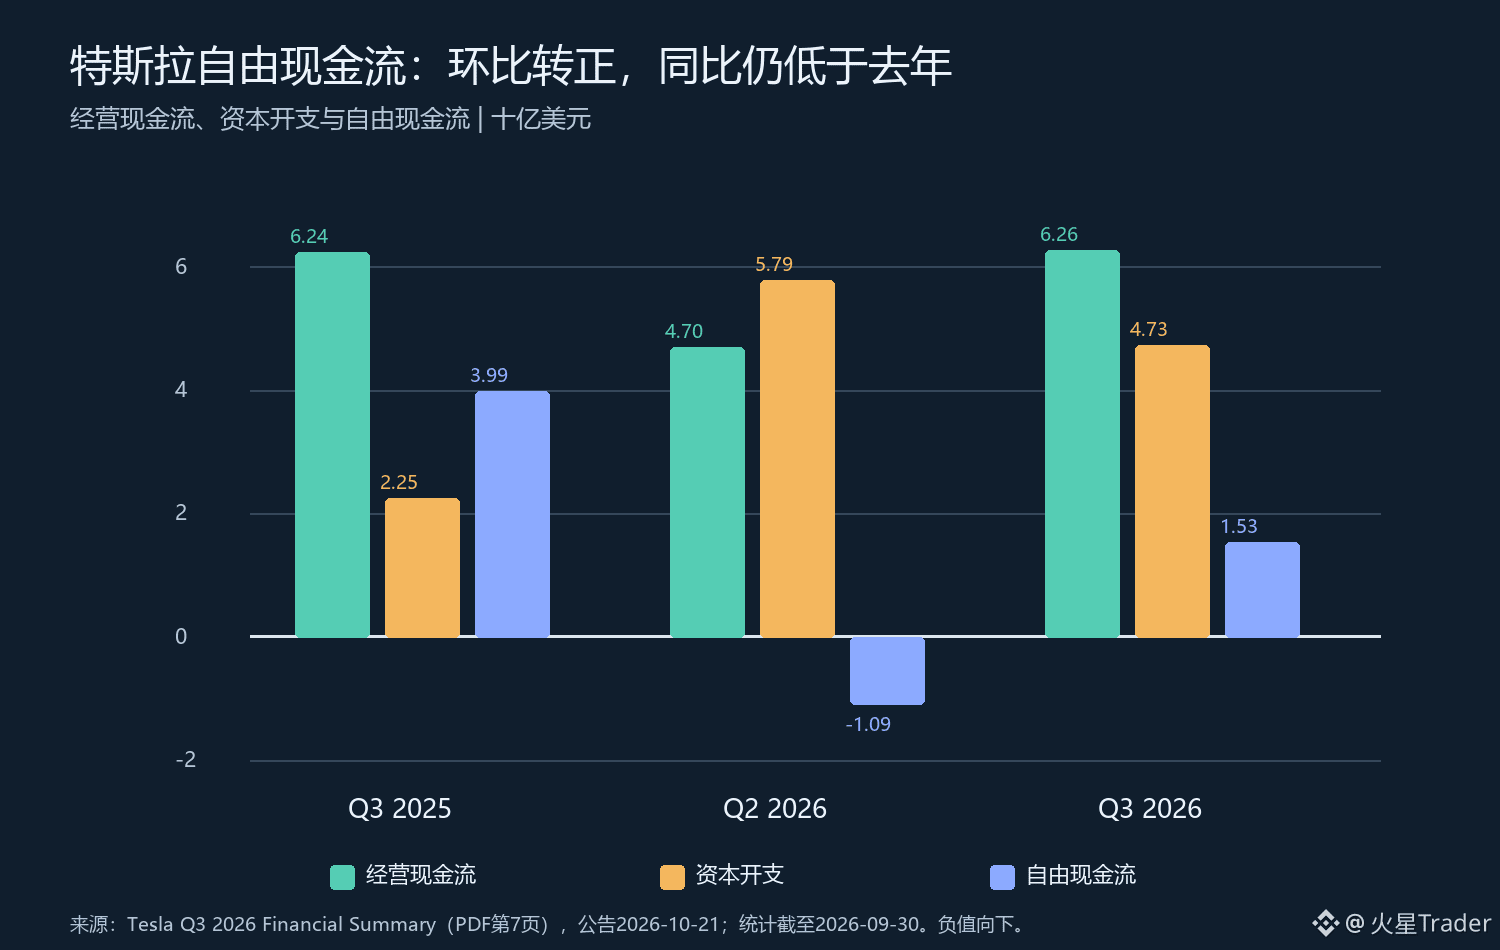
Tesla’s Q3 free cash flow turns positive: a rebound quarter over quarter doesn’t mean year-over-year improvement
Tesla’s free cash flow turned positive again in the third quarter. Viewed quarter over quarter, that certainly looks like a rebound; but put it alongside the same quarter last year, and the conclusion is less reassuring. The improvement in cash flow this quarter cannot simply be taken to mean that the operating trend has strengthened.
First, let’s look at the three figures on the same basis. In the third quarter of 2025, operating cash flow was $6.238 billion, capital expenditures were $2.248 billion, and free cash flow was $3.990 billion. In the second quarter of 2026, the figures were $4.697 billion, $5.789 billion, and negative $1.092 billion, respectively. By the third quarter of 2026, operating cash flow had recovered to $6.263 billion, capital expenditures had fallen to $4.732 billion, and free cash flow was positive at $1.531 billion. Here, free cash flow is calculated as operating cash flow minus capital expenditures.
So the quarter-over-quarter change is clear: operating cash flow increased by $1.566 billion, capital expenditures fell by $1.057 billion, and free cash flow improved by $2.623 billion, crossing above zero. Year over year, however, operating cash flow was only $25 million higher than in the same quarter last year, capital expenditures were $2.484 billion higher, and free cash flow was $2.459 billion lower, a decline of about 61.6%. The return to positive territory is real, but free cash flow is still some way from last year’s level.
These two comparisons answer different questions. The quarter-over-quarter figures show that cash flow recovered this quarter after heavier cash outlays in the previous quarter; the year-over-year figures show that cash retained is still below its level a year ago. Lower capital expenditures may reflect changes in project timing, but these three aggregated figures alone cannot prove that investment efficiency has improved or that cash flow quality is better. Factors such as working capital and the timing of payments and collections can all affect operating cash flow, so the full cash flow statement needs to be examined as well.
My view is that these figures support the conclusion that “quarterly cash flow pressures have eased,” but they are not enough to support the claim that “cash-generating ability has recovered.” In particular, capital expenditures remain significantly above last year’s level. Going forward, we need to watch both whether operating cash flow can be sustained and whether the capacity, deliveries, or profits expected from new investment materialize. If investment remains high while operating cash flow stays around its current level, free cash flow may remain under pressure. If operations continue to improve and generate enough cash to cover investment, the return to positive territory will carry more weight.
Next, I’ll wait for subsequent quarterly reports and focus on the consistency of operating cash flow, the pace of capital expenditures, and changes in working capital items. A single quarter of positive free cash flow is a turning-point signal worth noting, not confirmation of a trend; a narrowing year-over-year gap would be more convincing evidence.
Source material: Tesla’s third-quarter 2026 results, published on 2026-10-21, covering the period through 2026-09-30, Financial Summary; amounts are in millions of U.S. dollars, while charts display billions. Free cash flow is operating cash flow minus capital expenditures. Year-over-year and quarter-over-quarter differences and percentages are calculated from the figures in the release; comments on timing and future conditions are analysis, not company guidance.
Source: https://ir.tesla.com/_flysystem/s3/sec/000162828026066738/tsla-20261021-gen.pdf
Verification date: 2026-10-23.
66
·
--
Texas Instruments’ profit surges, but midpoint of Q4 revenue guidance is nearly flat sequentially
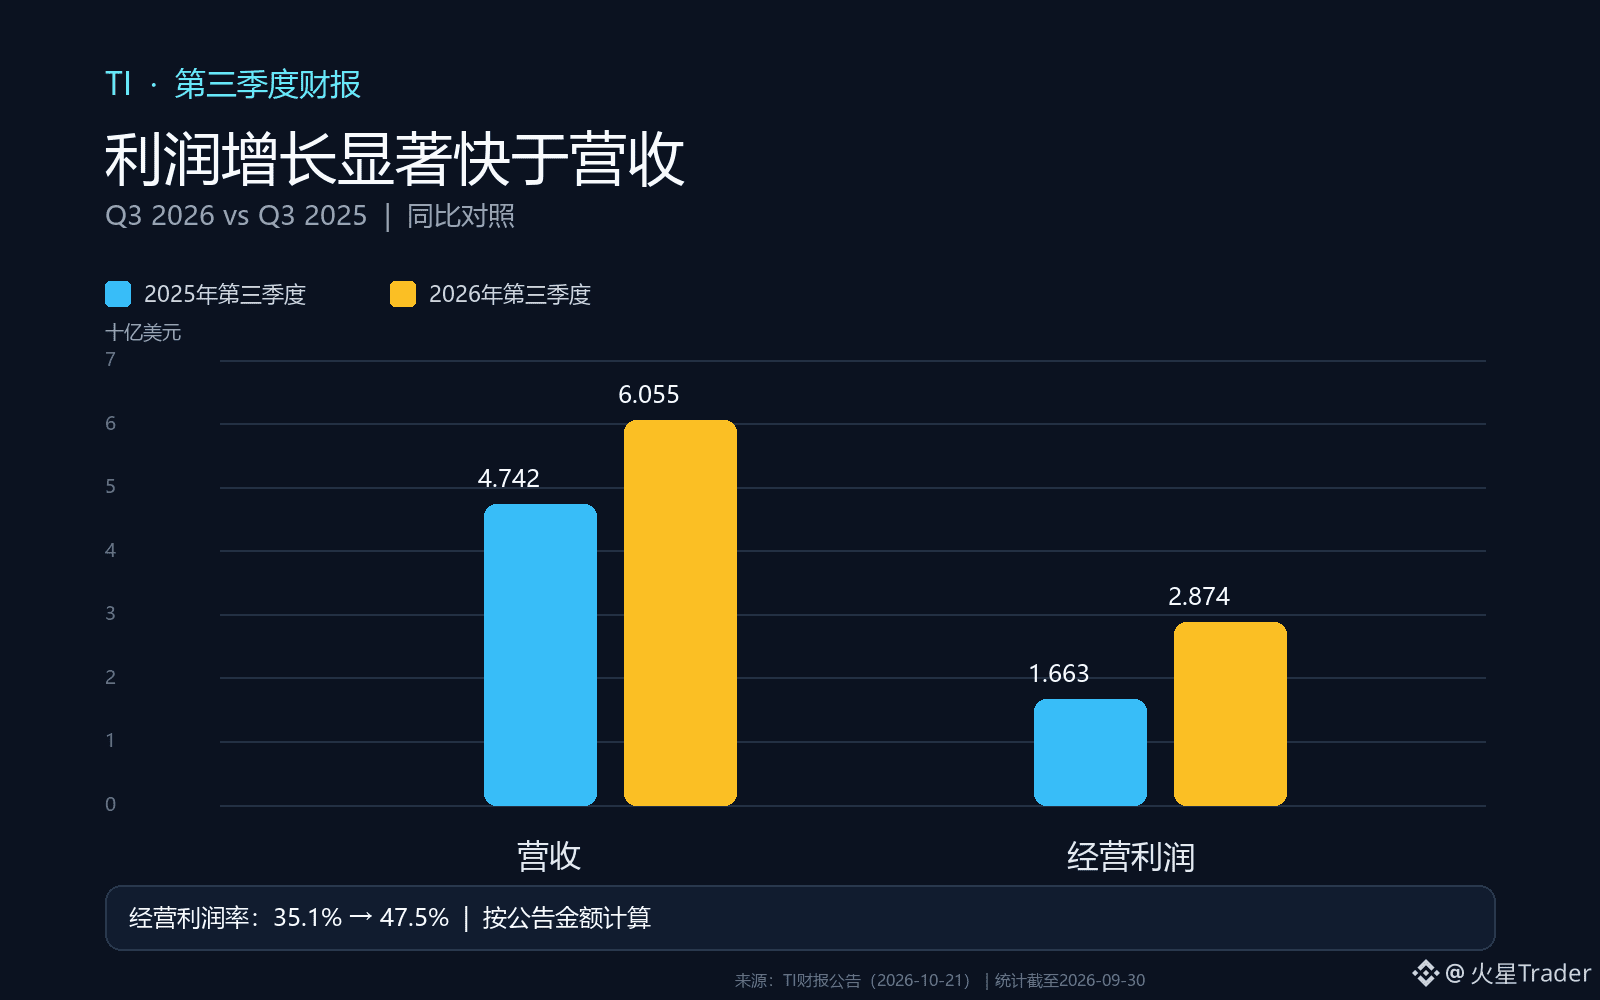
TI’s third-quarter profit recovery was striking, but I’d rather look at year-over-year growth and next-quarter momentum separately. Revenue grew 28% year over year, while operating profit rose 73%. This shows that earnings recovery is outpacing revenue growth significantly, but it doesn’t directly imply that revenue will accelerate sequentially in the fourth quarter.
For Q3, ended September 30, TI reported revenue of $6.055 billion, compared with $4.742 billion in the same period last year. Operating profit was $2.874 billion, up from $1.663 billion. Calculated as operating profit divided by revenue, the operating margin rose from about 35.1% to 47.5%, an increase of approximately 12.4 percentage points. The most notable takeaway from the chart isn’t simply that both bars are taller, but that profit grew much faster than revenue: as revenue expanded, costs and expenses became less burdensome relative to sales, magnifying the increase in profit.
However, this margin change cannot be attributed entirely to operating leverage in the quarter. The year-ago quarter included $85 million in restructuring charges, while this quarter had none; this quarter also included $7 million in acquisition charges. These amounts are small relative to the change in operating profit, but they’re a reminder that the comparison isn’t on a perfectly like-for-like basis. The more measured conclusion is that profit performance improved significantly. To assess whether this is sustainable, we’ll need to keep watching revenue mix, manufacturing costs, and spending in subsequent quarters rather than simply extrapolating 73% year-over-year growth.
There is also support on the demand side, although the evidence so far comes from the company’s description of the quarter. TI said that industrial, automotive, and data center businesses continued to see broad-based growth. That’s more resilient than growth driven by a single end market, but the announcement doesn’t specify the contribution from each market in this statement, so I wouldn’t characterize it as a synchronized recovery across every product line. We’ll need to see whether orders in these end markets and the company’s segment data continue to confirm the trend.
Q4 revenue guidance is $5.8 billion to $6.3 billion, with a midpoint of $6.05 billion—almost flat compared with Q3 revenue of $6.055 billion. The range itself is wide, meaning the company is providing a conditional range, not a commitment to the midpoint. At a minimum, it doesn’t offer clear evidence that revenue will continue to rise next quarter. On the other hand, Q4 revenue could also come in near the top of the range. The year-over-year comparison, seasonality, and timing of end-market demand will all affect the actual result, so we can’t conclude that growth has stalled based on the midpoint alone.
For now, I read this earnings report as showing that the profit recovery has materialized, while sequential acceleration remains to be confirmed. The key things to watch next are where actual Q4 revenue lands within the guidance range and whether the operating margin can sustain its current level. If revenue is broadly flat while margins continue to improve, we’ll still need to determine whether the improvement comes from product mix, cost efficiencies, or the timing of expenses. If revenue weakens and margins fall, the year-over-year profit growth this quarter is more likely to reflect a combination of cyclical recovery and a favorable comparison base.
Sources: Texas Instruments’ third-quarter 2026 earnings announcement, published 2026-10-21, for the period ended 2026-09-30; checked on 2026-10-23. Operating margin is calculated as operating profit divided by revenue and rounded to one decimal place. The Q4 guidance midpoint is the arithmetic average of the range endpoints. The accompanying chart was created using data from the announcement.
Source: https://investor.ti.com/news-releases/news-release-details/ti-reports-third-quarter-2026-financial-results-and-shareholder
124
·
--
Does a stock split make the share price lower—and the company cheaper to value?
After a stock split, the price per share falls and the number of shares increases, but that doesn’t mean the company suddenly becomes cheaper. Treating “how much one share costs” as a measure of “how expensive the whole company is” is one of the easiest mistakes to make when trying to understand stock splits.
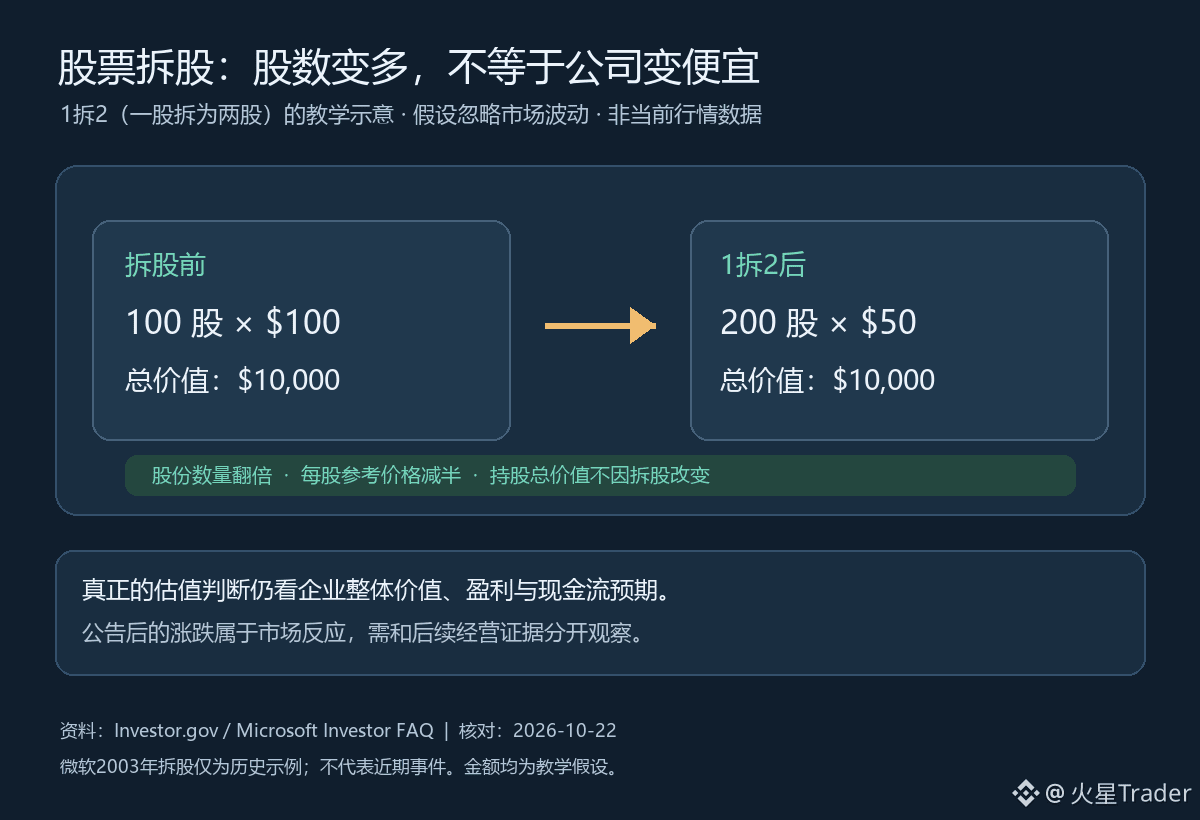
Here’s a purely hypothetical example: Suppose an investor owns 100 shares of a company at $100 per share, for a total holding value of $10,000. In a 2-for-1 split (one share becomes two), the number of shares becomes 200 and the reference price per share becomes $50, while the total value remains $10,000 and the investor’s ownership percentage stays the same. This ignores market fluctuations and illustrates only the mechanical effect of a split; it does not magically increase the company’s revenue, profit, or cash flow. Investor.gov also uses the example of 100 shares multiplied by $100 becoming 200 shares multiplied by $50 to explain that a split does not, by itself, change the value of a holding.
A split may make the price of a single share more accessible to a wider range of investors and change how per-share metrics are presented. But “one share looks cheaper to buy” and “the company is valued lower” are two different things. To assess valuation, you still need to look at the company’s overall market capitalization, earnings and cash-flow expectations, and how much investors are willing to pay for those expectations. Metrics such as earnings per share are also adjusted for the share count after a split, so make sure you’re comparing figures on a consistent basis.
A historical example listed in Microsoft’s investor FAQ is its 2003 split: 100 shares at $50 per share became 200 shares at $25 per share, with the total value remaining $5,000 until the market price changed. This example is only meant to explain how a stock split works. It does not mean Microsoft has split its stock recently, nor can it be used to infer the current price or valuation of any stock.
On the day a split is announced, the share price may rise, fall, or remain largely unchanged. That reflects the market’s reaction to the news, not a change in the company’s value caused by the arithmetic of the split itself. If the price subsequently strengthens, it’s still important to distinguish whether that reflects sentiment or liquidity expectations, or whether earnings guidance and operating results have actually improved. If business expectations haven’t changed, a change in the number of shares alone is unlikely to provide a new cash-flow-based rationale.
So when considering a stock split, first adjust the share count and price per share proportionally, then look at the company’s overall value and evidence of its earnings. When I come across news of a split in the future, I’ll continue to watch whether the market’s reaction after the announcement is confirmed by subsequent results and guidance, rather than focusing only on the adjusted per-share figures. All amounts shown in the image are illustrative examples, not current market prices.
Sources: Investor.gov, “Stock Split”; Microsoft Investor Relations FAQ, historical example of the 2003 stock split. Both checked on 2026-10-22. The example of 100 shares × $100 is hypothetical; the Microsoft example is historical and does not refer to a current event.
https://www.investor.gov/introduction-investing/investing-basics/glossary/stock-split
https://www.microsoft.com/en-us/investor/FAQ
132
·
--
【Intraday Update】BNB breaks above 750 USDT, up 2.22% in 24 hours
· Good news is out—don’t rush in. Check whether the market had already priced it in.
· Wait for the price to pull back to the range it was in before the news came out. If it holds, then the news has had an effect.
· $BNB
【Intraday Update】BNB breaks above 750 USDT, up 2.22% in 24 hours
· Good news is out—don’t rush in. Check whether the market had already priced it in.
· Wait for the price to pull back to the range it was in before the news came out. If it holds, then the news has had an effect.
· $BNB
· Good news is out—don’t rush in. Check whether the market had already priced it in.
· Wait for the price to pull back to the range it was in before the news came out. If it holds, then the news has had an effect.
· $BNB
18
·
--
Consistency matters more than being smart.
In trading, consistently doing small things right is more useful than occasionally getting one big thing right.
After saying that, I glanced at $ETH , trading at 2511.33 (24h +3.24%). Have you ever set trading rules for yourselves?
Consistency matters more than being smart.
In trading, consistently doing small things right is more useful than occasionally getting one big thing right.
After saying that, I glanced at $ETH , trading at 2511.33 (24h +3.24%). Have you ever set trading rules for yourselves?
In trading, consistently doing small things right is more useful than occasionally getting one big thing right.
After saying that, I glanced at $ETH , trading at 2511.33 (24h +3.24%). Have you ever set trading rules for yourselves?
222
·
--
Bitcoin ETFs saw net outflows of 403 BTC yesterday, while Ethereum ETFs saw net outflows of 12,700 ETH.
How should we interpret institutional activity? Institutional outflows can weigh on sentiment in the short term. The key is whether these are isolated moves or sustained outflows.
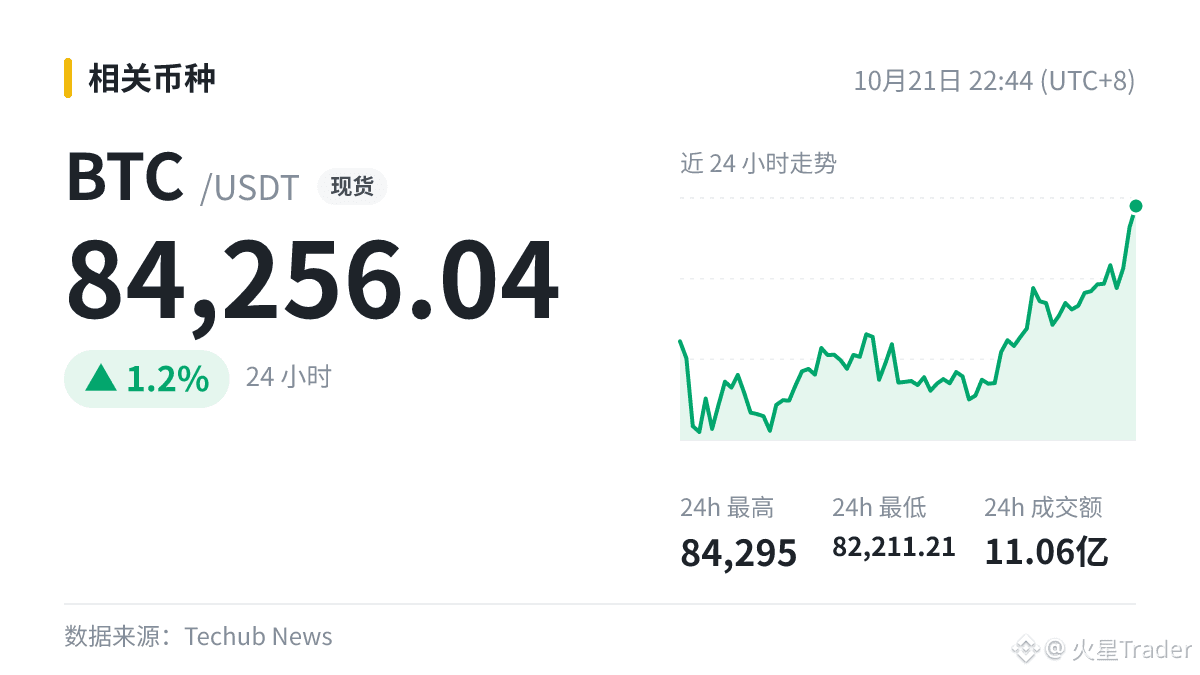
$BTC The current price is 84256.04. Are you leaning bullish or bearish from here?
#BTC
How should we interpret institutional activity? Institutional outflows can weigh on sentiment in the short term. The key is whether these are isolated moves or sustained outflows.
$BTC The current price is 84256.04. Are you leaning bullish or bearish from here?
#BTC
42
·
--
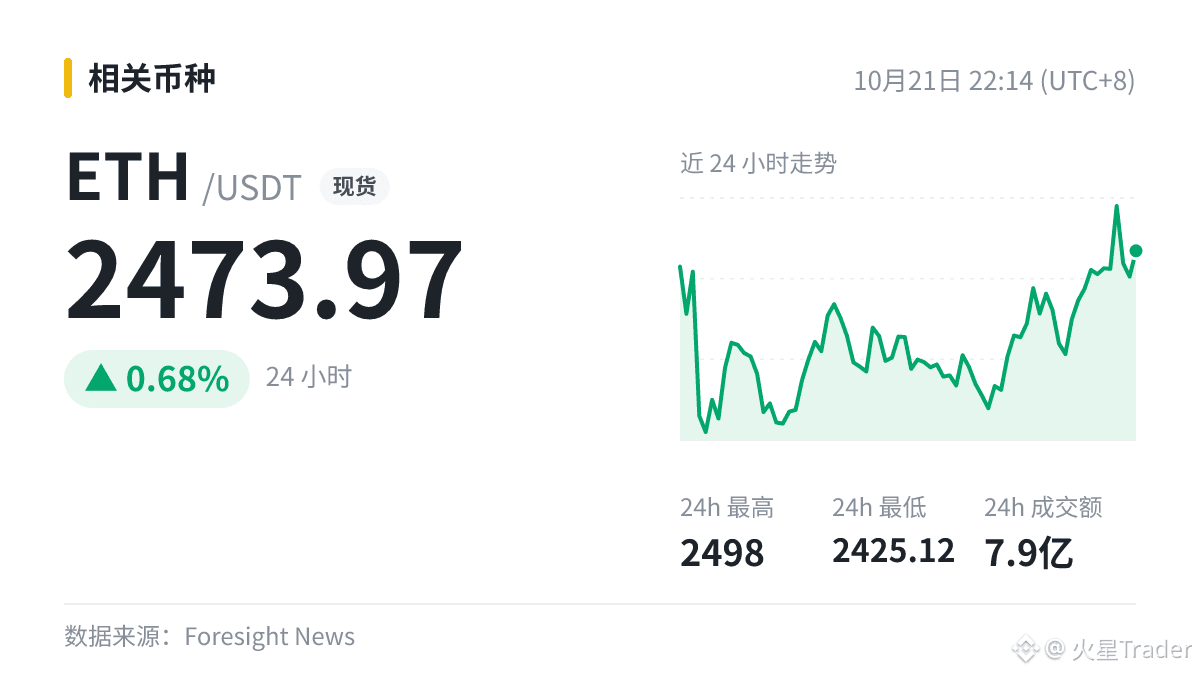
Safe Labs' trading security network, Safenet, has ended its beta phase and launched its production version.
I discussed this with friends, and opinions were quite divided. I actually think it’s better to wait and see. It’s worth cheering everyone on, but how far it can go will depend on trading volume going forward.
$ETH 2473.97
#ETH
I discussed this with friends, and opinions were quite divided. I actually think it’s better to wait and see. It’s worth cheering everyone on, but how far it can go will depend on trading volume going forward.
$ETH 2473.97
#ETH
20
·
--
This topic is being discussed in the square: #Solana今日将激活Alpenglow升级
A valid breakout needs volume to follow; breakouts on shrinking volume often return to the range.
$SOL 24h +2.35%
This topic is being discussed in the square: #Solana今日将激活Alpenglow升级
A valid breakout needs volume to follow; breakouts on shrinking volume often return to the range.
$SOL 24h +2.35%
A valid breakout needs volume to follow; breakouts on shrinking volume often return to the range.
$SOL 24h +2.35%
97
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
FOMCWatch
8.9M views
26,644 Discussing
🚨 FOMC WATCH JUST GOT SERIOUS! 📊
Three Fed officials backed a rate hike at the July meeting while rates stayed at 3.50%–3.75%.
That divide could create major volatility for risk assets like $BTC, $ETH and $BNB when new economic data arrives.
#fomcwatch
CryptoMahibaloch
·0 Likes
·44 views
EthereumDropsBelow$2300
2,232 views
89 Discussing
BitcoinSlipsBelow$80KAgain
6,223 views
58 Discussing