Bitcoin falls below $56,000, down over 5% intraday: From on-chain narratives to macro liquidity dynamics
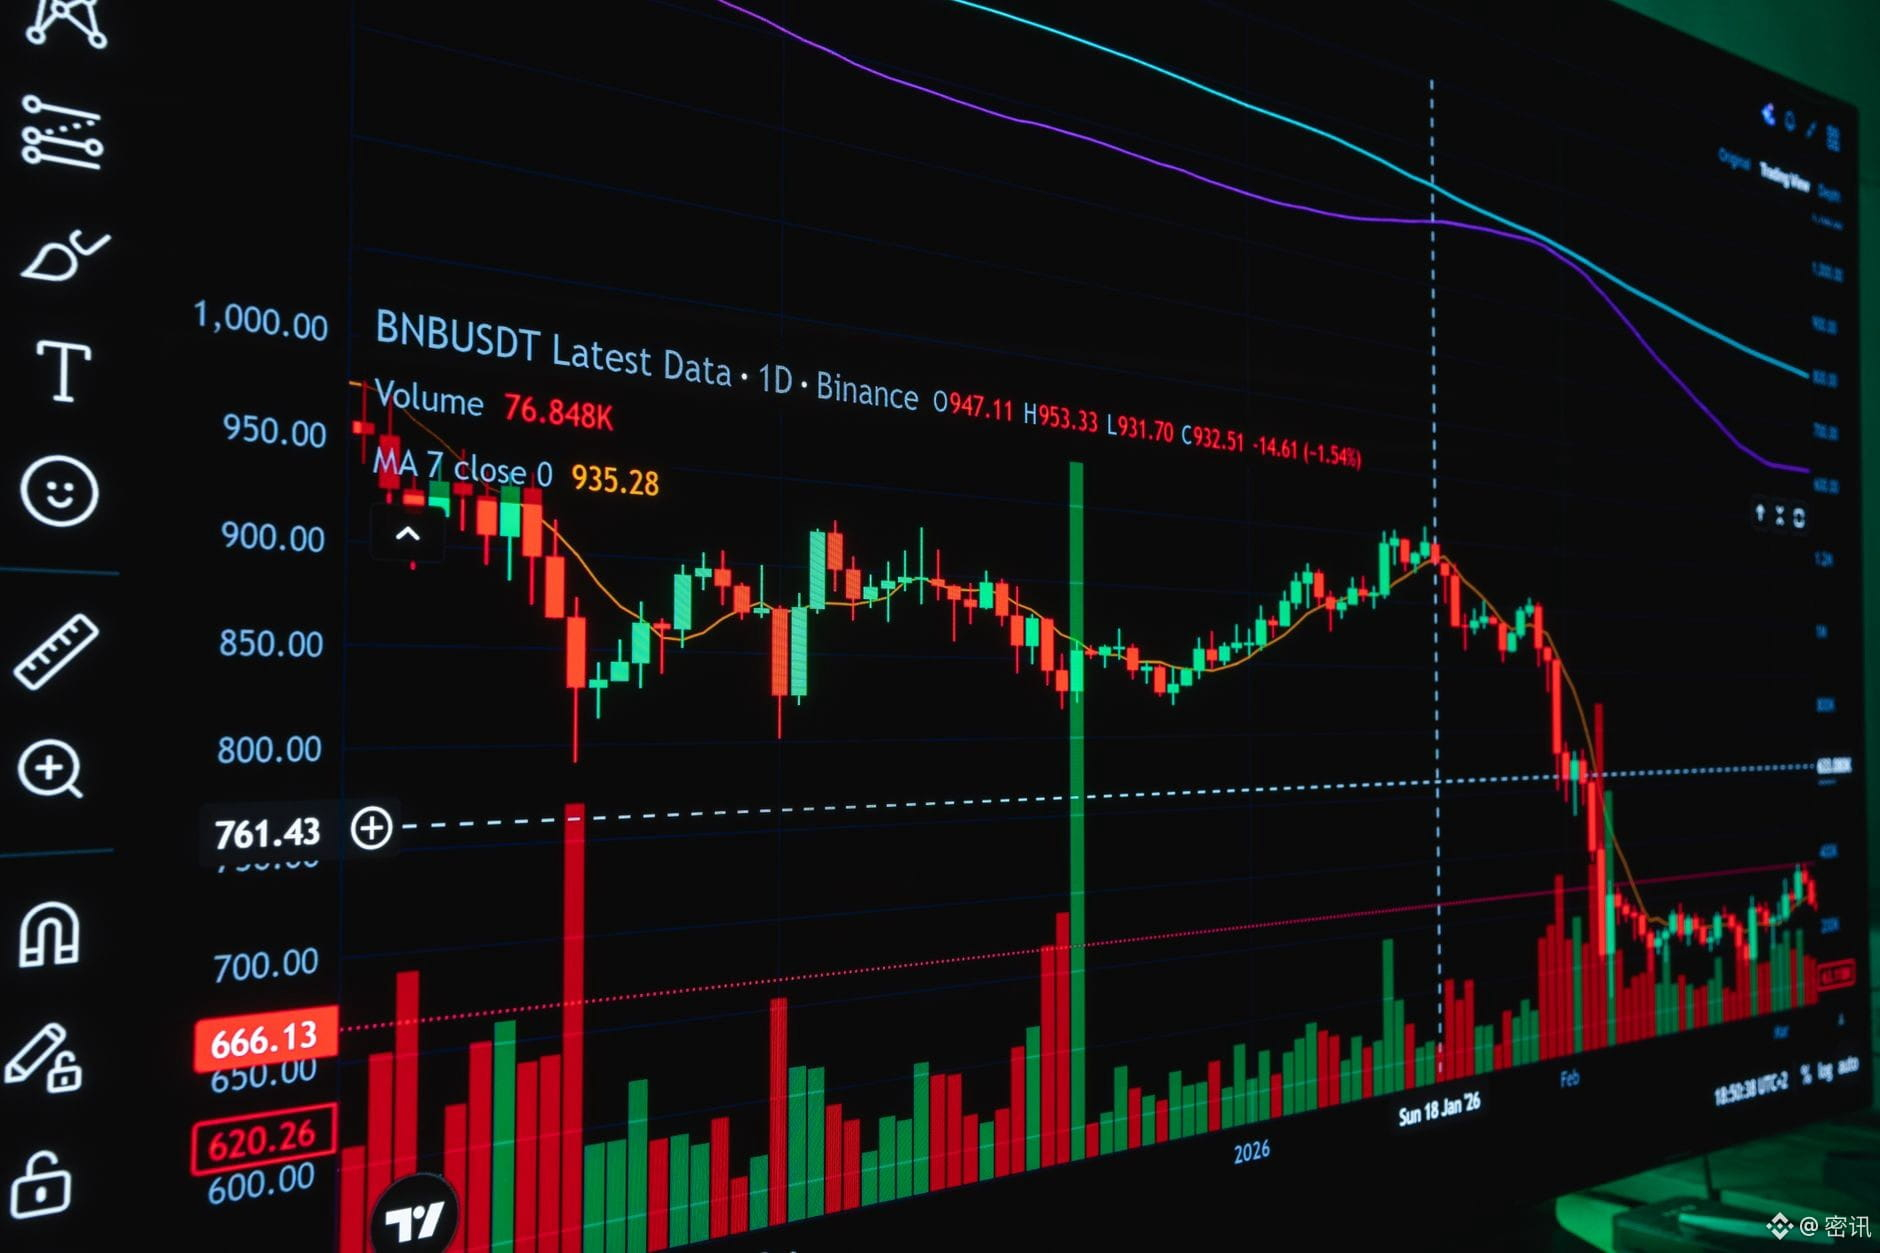
Global risk asset markets are undergoing a sharp deleveraging process. As a core high-beta asset, Bitcoin has seen a significant shift in the forces driving its price fluctuations. In the past, crypto market pricing relied more on on-chain ecosystem narratives, technological upgrades, or marginal changes in regulatory expectations. Today, Bitcoin’s performance is deeply embedded in the framework of macro liquidity expectations, making it a direct reflection of macro capital flows. As the U.S. dollar index remains elevated and volatile amid repeated shifts in the Federal Reserve’s policy path, and geopolitical noise fuels misplaced risk aversion, the already relatively fragile liquidity in crypto markets is being rapidly drained. Bitcoin’s fall below the $56,000 mark is not an isolated technical breakdown, but an inevitable result of the repricing of “risk premiums” in the global macro narrative. With no clear influx of new capital and macro uncertainty continuing to intensify, the market’s sensitivity to any negative signal has been magnified dramatically, causing price discovery to take the form of a nonlinear plunge. This trend indicates that control of the market currently lies firmly in the hands of macro hedge funds and trend-following algorithms. Retail sentiment and fundamental value have become almost irrelevant to short-term pricing, and the market has entered a “risk-off” phase dominated by macroeconomic variables.
Looking at market action and capital flows, Bitcoin quickly broke through the key support level of $56,000 intraday, falling more than 5%. This decline is particularly unusual given the recent absence of any major protocol upgrades or positive regulatory catalysts. Meanwhile, negative narratives about China’s economy in international discourse—such as warnings of a “deflationary trap” or claims of “China Shock 2.0”—are primarily aimed at the traditional economy. However, the pessimistic expectations they reflect form an important backdrop to the global contraction in risk appetite, indirectly affecting asset valuations in related economies. More importantly, spot Bitcoin ETFs, the main channel for institutional capital to enter crypto markets, have shown significant procyclicality in their flows during periods of concentrated macro headwinds like this. When the macro outlook is uncertain, institutions tend to lock in profits or reduce risk exposure by redeeming ETF shares, rather than adding to positions against the trend. The Federal Reserve’s policy path is having an amplified impact on Bitcoin pricing at this point. As market expectations for the timing and scale of rate cuts fluctuate repeatedly, persistently high real interest rates have significantly increased the cost of holding Bitcoin, a non-yielding asset, further dampening buying interest. This collective shift in institutional behavior has intensified selling pressure, accelerating the decline in the absence of sufficient buying support.
This breakdown and subsequent decline reveal the fragile link between crypto markets and macroeconomic fundamentals, forcing market participants to recalibrate their definition of “risk assets.” Bitcoin is no longer viewed solely as “digital gold” or an inflation hedge. Under the combined pressure of recession expectations and tightening liquidity, its high volatility makes it one of the first risk assets institutions cut from their hedging portfolios. The breach of the $56,000 mark means that many leveraged longs opened in this range face forced liquidation, and this chain reaction has intensified downward price momentum. Across the sector, Ethereum and other large-cap altcoins typically have higher betas and often fall more sharply than Bitcoin. This reflects the withdrawal of capital from high-risk, high-volatility assets and its return to cash or traditional safe havens as risk appetite contracts rapidly. This movement of capital is not based on a reassessment of blockchain technology, but is driven purely by macro liquidity. It is worth noting that although some argue crypto markets are independent, this episode shows that in a market environment dominated by global macro narratives, price rallies unsupported by endogenous growth drivers are unlikely to withstand macro headwinds. In this process, Bitcoin has been reclassified as a high-volatility macro derivative rather than an independent monetary network, and its valuation anchor is shifting from on-chain activity to the macro interest rate curve.
The market’s key areas of focus going forward should include several core dimensions. First, daily net inflows and outflows from spot Bitcoin ETFs are the most direct indicator of institutional sentiment. If ETFs continue to see net redemptions, particularly at a rate significantly above average daily trading volume, that would indicate institutions are still pursuing defensive strategies and that a short-term rebound lacks fundamental support. Second, closely monitor public statements by Federal Reserve officials and the release of macroeconomic data. Any ambiguous signal about the interest rate path could prompt excessive market interpretation and, in turn, affect expectations for real interest rates. Also watch large on-chain transfers and net flows to exchanges to determine whether panic selling or capitulation by large holders is underway. If on-chain data shows long-term holders transferring large amounts of Bitcoin to exchanges, that could signal further downside risk. At the same time, keep an eye on monetary policy developments at major central banks around the world, especially the relationship between the U.S. dollar index and the 10-year Treasury yield, since Bitcoin prices are significantly negatively correlated with real interest rates. Finally, although the China-related economic narratives mentioned above mainly concern the traditional macroeconomic sphere, be alert to concerns about global supply chains and expectations of escalating trade friction that they may trigger. These factors could indirectly affect crypto markets by influencing the overall valuation baseline for global risk assets. In the current environment, any attempt to buy the dip based on technical oversold signals requires extreme caution. The turning point in macro liquidity has yet to arrive, and the market remains in the early stages of risk unwinding. Investors should stay alert to macroeconomic variables rather than relying solely on optimistic expectations based on on-chain data.
Follow me so you don’t miss the next quick market update.
Global risk asset markets are undergoing a sharp deleveraging process. As a core high-beta asset, Bitcoin has seen a significant shift in the forces driving its price fluctuations. In the past, crypto market pricing relied more on on-chain ecosystem narratives, technological upgrades, or marginal changes in regulatory expectations. Today, Bitcoin’s performance is deeply embedded in the framework of macro liquidity expectations, making it a direct reflection of macro capital flows. As the U.S. dollar index remains elevated and volatile amid repeated shifts in the Federal Reserve’s policy path, and geopolitical noise fuels misplaced risk aversion, the already relatively fragile liquidity in crypto markets is being rapidly drained. Bitcoin’s fall below the $56,000 mark is not an isolated technical breakdown, but an inevitable result of the repricing of “risk premiums” in the global macro narrative. With no clear influx of new capital and macro uncertainty continuing to intensify, the market’s sensitivity to any negative signal has been magnified dramatically, causing price discovery to take the form of a nonlinear plunge. This trend indicates that control of the market currently lies firmly in the hands of macro hedge funds and trend-following algorithms. Retail sentiment and fundamental value have become almost irrelevant to short-term pricing, and the market has entered a “risk-off” phase dominated by macroeconomic variables.
Looking at market action and capital flows, Bitcoin quickly broke through the key support level of $56,000 intraday, falling more than 5%. This decline is particularly unusual given the recent absence of any major protocol upgrades or positive regulatory catalysts. Meanwhile, negative narratives about China’s economy in international discourse—such as warnings of a “deflationary trap” or claims of “China Shock 2.0”—are primarily aimed at the traditional economy. However, the pessimistic expectations they reflect form an important backdrop to the global contraction in risk appetite, indirectly affecting asset valuations in related economies. More importantly, spot Bitcoin ETFs, the main channel for institutional capital to enter crypto markets, have shown significant procyclicality in their flows during periods of concentrated macro headwinds like this. When the macro outlook is uncertain, institutions tend to lock in profits or reduce risk exposure by redeeming ETF shares, rather than adding to positions against the trend. The Federal Reserve’s policy path is having an amplified impact on Bitcoin pricing at this point. As market expectations for the timing and scale of rate cuts fluctuate repeatedly, persistently high real interest rates have significantly increased the cost of holding Bitcoin, a non-yielding asset, further dampening buying interest. This collective shift in institutional behavior has intensified selling pressure, accelerating the decline in the absence of sufficient buying support.
This breakdown and subsequent decline reveal the fragile link between crypto markets and macroeconomic fundamentals, forcing market participants to recalibrate their definition of “risk assets.” Bitcoin is no longer viewed solely as “digital gold” or an inflation hedge. Under the combined pressure of recession expectations and tightening liquidity, its high volatility makes it one of the first risk assets institutions cut from their hedging portfolios. The breach of the $56,000 mark means that many leveraged longs opened in this range face forced liquidation, and this chain reaction has intensified downward price momentum. Across the sector, Ethereum and other large-cap altcoins typically have higher betas and often fall more sharply than Bitcoin. This reflects the withdrawal of capital from high-risk, high-volatility assets and its return to cash or traditional safe havens as risk appetite contracts rapidly. This movement of capital is not based on a reassessment of blockchain technology, but is driven purely by macro liquidity. It is worth noting that although some argue crypto markets are independent, this episode shows that in a market environment dominated by global macro narratives, price rallies unsupported by endogenous growth drivers are unlikely to withstand macro headwinds. In this process, Bitcoin has been reclassified as a high-volatility macro derivative rather than an independent monetary network, and its valuation anchor is shifting from on-chain activity to the macro interest rate curve.
The market’s key areas of focus going forward should include several core dimensions. First, daily net inflows and outflows from spot Bitcoin ETFs are the most direct indicator of institutional sentiment. If ETFs continue to see net redemptions, particularly at a rate significantly above average daily trading volume, that would indicate institutions are still pursuing defensive strategies and that a short-term rebound lacks fundamental support. Second, closely monitor public statements by Federal Reserve officials and the release of macroeconomic data. Any ambiguous signal about the interest rate path could prompt excessive market interpretation and, in turn, affect expectations for real interest rates. Also watch large on-chain transfers and net flows to exchanges to determine whether panic selling or capitulation by large holders is underway. If on-chain data shows long-term holders transferring large amounts of Bitcoin to exchanges, that could signal further downside risk. At the same time, keep an eye on monetary policy developments at major central banks around the world, especially the relationship between the U.S. dollar index and the 10-year Treasury yield, since Bitcoin prices are significantly negatively correlated with real interest rates. Finally, although the China-related economic narratives mentioned above mainly concern the traditional macroeconomic sphere, be alert to concerns about global supply chains and expectations of escalating trade friction that they may trigger. These factors could indirectly affect crypto markets by influencing the overall valuation baseline for global risk assets. In the current environment, any attempt to buy the dip based on technical oversold signals requires extreme caution. The turning point in macro liquidity has yet to arrive, and the market remains in the early stages of risk unwinding. Investors should stay alert to macroeconomic variables rather than relying solely on optimistic expectations based on on-chain data.
Follow me so you don’t miss the next quick market update.