How Can Staggered Entries Control the Cost of Testing a Trade? From a Probe Position to Confirmation and Adding to the Position
Staggered entry does not mean arbitrarily splitting your funds into three portions, nor does it mean buying more as the price keeps falling.
The correct sequence is:
① First identify the point at which the trading thesis is invalidated
② Set the maximum risk per trade at 1R
③ Use a small position to test the trade
④ Increase the position after the setup is confirmed
⑤ Add the rest of the position if the market continues to move in your favor
Core formulas:
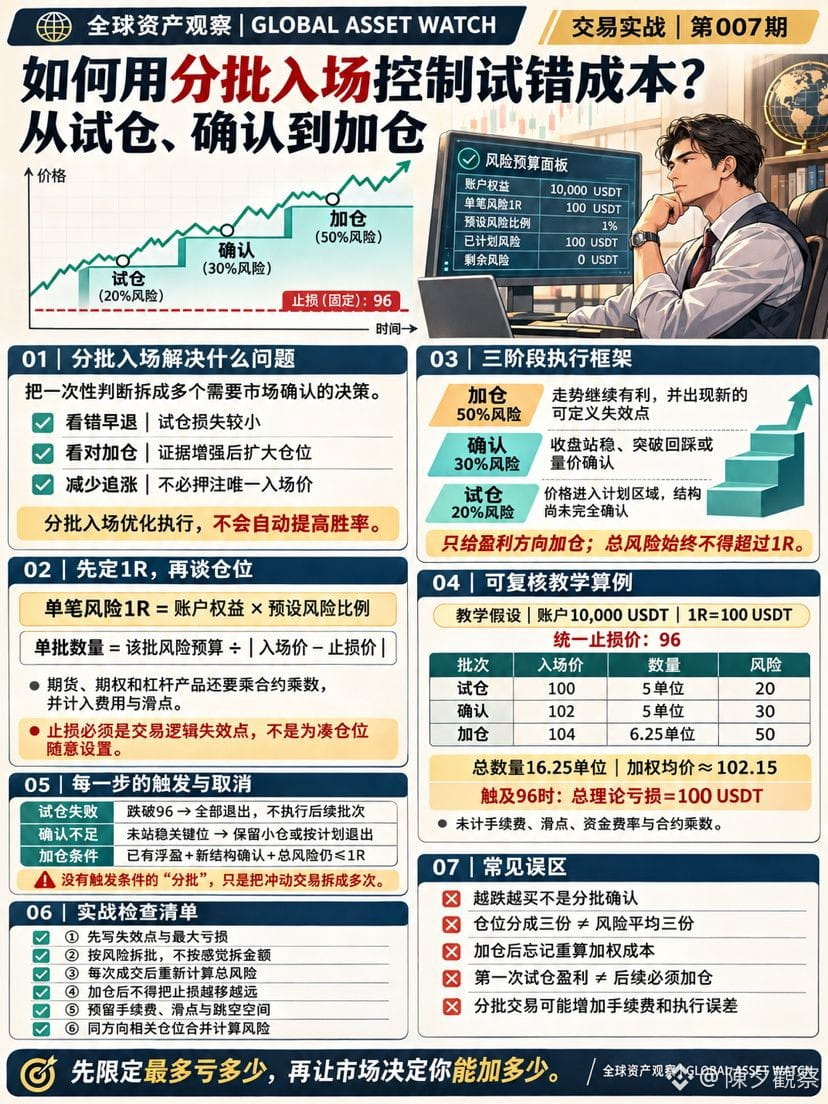
Risk per trade (1R) = account equity × preset risk percentage
Quantity per batch = risk budget for that batch ÷ |entry price − stop-loss price|
Illustrative example in the diagram: With an account of 10,000 USDT, the maximum risk per trade is 1%, or 100 USDT. With a common stop at 96, enter 5, 5, and 6.25 units at 100, 102, and 104, respectively. Once all orders are filled, the total position is 16.25 units, with a weighted average entry price of approximately 102.15. If the price reaches 96, the theoretical loss is still 100 USDT—not including fees, slippage, funding rates, or contract multipliers.
The CME position-sizing framework likewise emphasizes that you should first determine the logical stop-loss and the amount of account risk you are willing to take, then work backward to calculate the tradable quantity.
Keep in mind:
Add to a position only when it is moving in your favor
Recalculate total risk after each fill
Never move your stop-loss farther away after adding to a position
Combine and calculate the risk of positions in the same direction that are highly correlated
Staggered trading does not guarantee profits and may increase fees and execution errors.
First set a limit on how much you can lose; then let the market determine how much you can add.
#比特币跌破6万美元,短期能否企稳反弹?
Coming next:
Sunday | Trading Systems and Reviews | Episode 007
“What Is the Expectancy of a Trading Strategy? Why Can Even High Win-Rate Strategies Lose Money Over the Long Run?”
Staggered entry does not mean arbitrarily splitting your funds into three portions, nor does it mean buying more as the price keeps falling.
The correct sequence is:
① First identify the point at which the trading thesis is invalidated
② Set the maximum risk per trade at 1R
③ Use a small position to test the trade
④ Increase the position after the setup is confirmed
⑤ Add the rest of the position if the market continues to move in your favor
Core formulas:
Risk per trade (1R) = account equity × preset risk percentage
Quantity per batch = risk budget for that batch ÷ |entry price − stop-loss price|
Illustrative example in the diagram: With an account of 10,000 USDT, the maximum risk per trade is 1%, or 100 USDT. With a common stop at 96, enter 5, 5, and 6.25 units at 100, 102, and 104, respectively. Once all orders are filled, the total position is 16.25 units, with a weighted average entry price of approximately 102.15. If the price reaches 96, the theoretical loss is still 100 USDT—not including fees, slippage, funding rates, or contract multipliers.
The CME position-sizing framework likewise emphasizes that you should first determine the logical stop-loss and the amount of account risk you are willing to take, then work backward to calculate the tradable quantity.
Keep in mind:
Add to a position only when it is moving in your favor
Recalculate total risk after each fill
Never move your stop-loss farther away after adding to a position
Combine and calculate the risk of positions in the same direction that are highly correlated
Staggered trading does not guarantee profits and may increase fees and execution errors.
First set a limit on how much you can lose; then let the market determine how much you can add.
#比特币跌破6万美元,短期能否企稳反弹?
Coming next:
Sunday | Trading Systems and Reviews | Episode 007
“What Is the Expectancy of a Trading Strategy? Why Can Even High Win-Rate Strategies Lose Money Over the Long Run?”