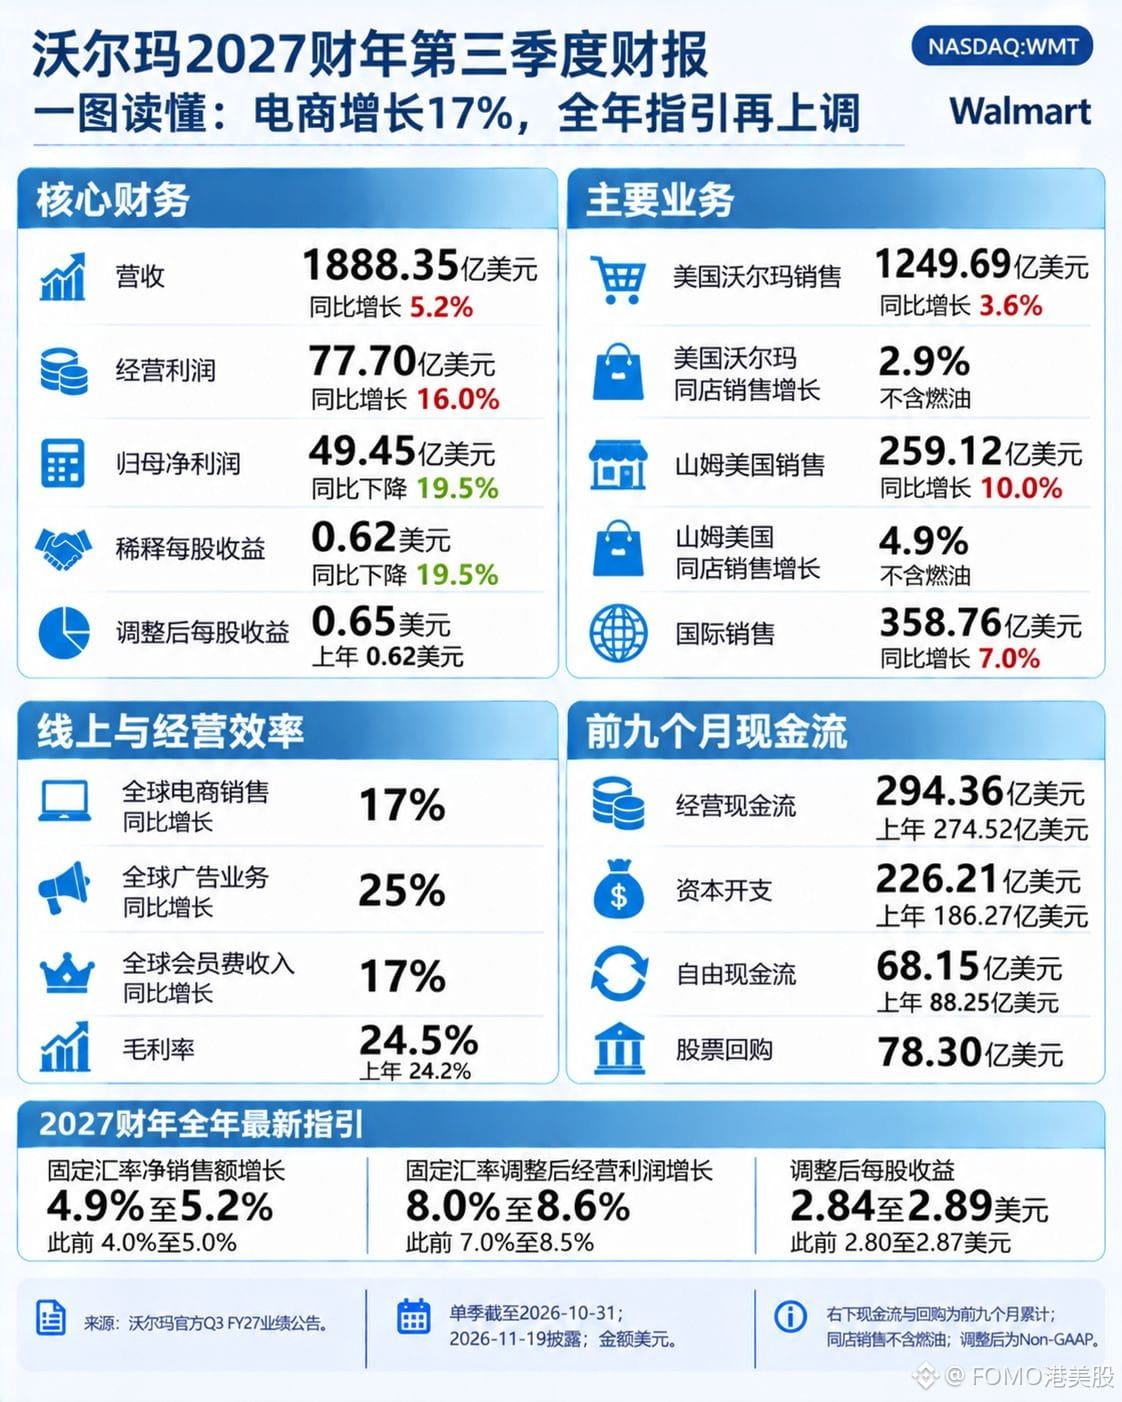
Walmart $WMT reported third-quarter revenue of $188.835 billion, up 5.2%, operating profit up 16%, e-commerce up 17%, and full-year guidance raised again. The stock fell 1.04% after earnings and closed 6.5% below its 52-week high.
Growth came from online and advertising. Global e-commerce grew 17%, advertising 25%, membership fees 17%, Sam's Club U.S. sales 10%, and U.S. same-store sales 2.9%, supported by 1.4 percentage-point gains each from transaction count and average ticket.
Net profit was dragged down by investments.
Net income attributable to shareholders fell 19.5% to $4.945 billion, as other gains and losses swung from a $2.081 billion gain last year to a $341 million loss. Excluding adjustments, earnings per share were $0.65, higher than last year's $0.62.
What the market is hesitant about is capital expenditure. On the earnings day, the stock closed at $126.04, down 1.04%, only 6.5% below its 52-week high, with the share price still near elevated levels. Over the first nine months, spending rose from $18.627 billion to $22.621 billion, while free cash flow fell from $8.825 billion to $6.815 billion. That concern may be overstated.
Revenue rose 5.2%, adjusted operating profit at constant exchange rates rose 5.5%, and full-year net sales guidance was lifted to 4.9% to 5.2%. Higher investment delivered 17% e-commerce growth and 25% advertising growth. Whether fourth-quarter e-commerce growth can hold is the key test.
The variable is free cash flow. $6.815 billion is $2 billion less than last year's $8.825 billion, and that will determine how long this valuation can be sustained.
#沃尔玛 #BStocks #股票财报季
Growth came from online and advertising. Global e-commerce grew 17%, advertising 25%, membership fees 17%, Sam's Club U.S. sales 10%, and U.S. same-store sales 2.9%, supported by 1.4 percentage-point gains each from transaction count and average ticket.
Net profit was dragged down by investments.
Net income attributable to shareholders fell 19.5% to $4.945 billion, as other gains and losses swung from a $2.081 billion gain last year to a $341 million loss. Excluding adjustments, earnings per share were $0.65, higher than last year's $0.62.
What the market is hesitant about is capital expenditure. On the earnings day, the stock closed at $126.04, down 1.04%, only 6.5% below its 52-week high, with the share price still near elevated levels. Over the first nine months, spending rose from $18.627 billion to $22.621 billion, while free cash flow fell from $8.825 billion to $6.815 billion. That concern may be overstated.
Revenue rose 5.2%, adjusted operating profit at constant exchange rates rose 5.5%, and full-year net sales guidance was lifted to 4.9% to 5.2%. Higher investment delivered 17% e-commerce growth and 25% advertising growth. Whether fourth-quarter e-commerce growth can hold is the key test.
The variable is free cash flow. $6.815 billion is $2 billion less than last year's $8.825 billion, and that will determine how long this valuation can be sustained.
#沃尔玛 #BStocks #股票财报季