Anthropic at $1.5 trillion—is it worth it? Here’s the verdict upfront: based on its reported figures, it’s pricey; based on the money it actually brings in, it’s wildly overpriced.
It closed its first day at $97.17, up 17% from the IPO price of $83. Based on shares outstanding, its market cap is $1.28 trillion; on a fully diluted basis, it’s about $1.8 trillion—the $1.5 trillion figure is based on the IPO price. After hours, it fell nearly 5% to $92.60.
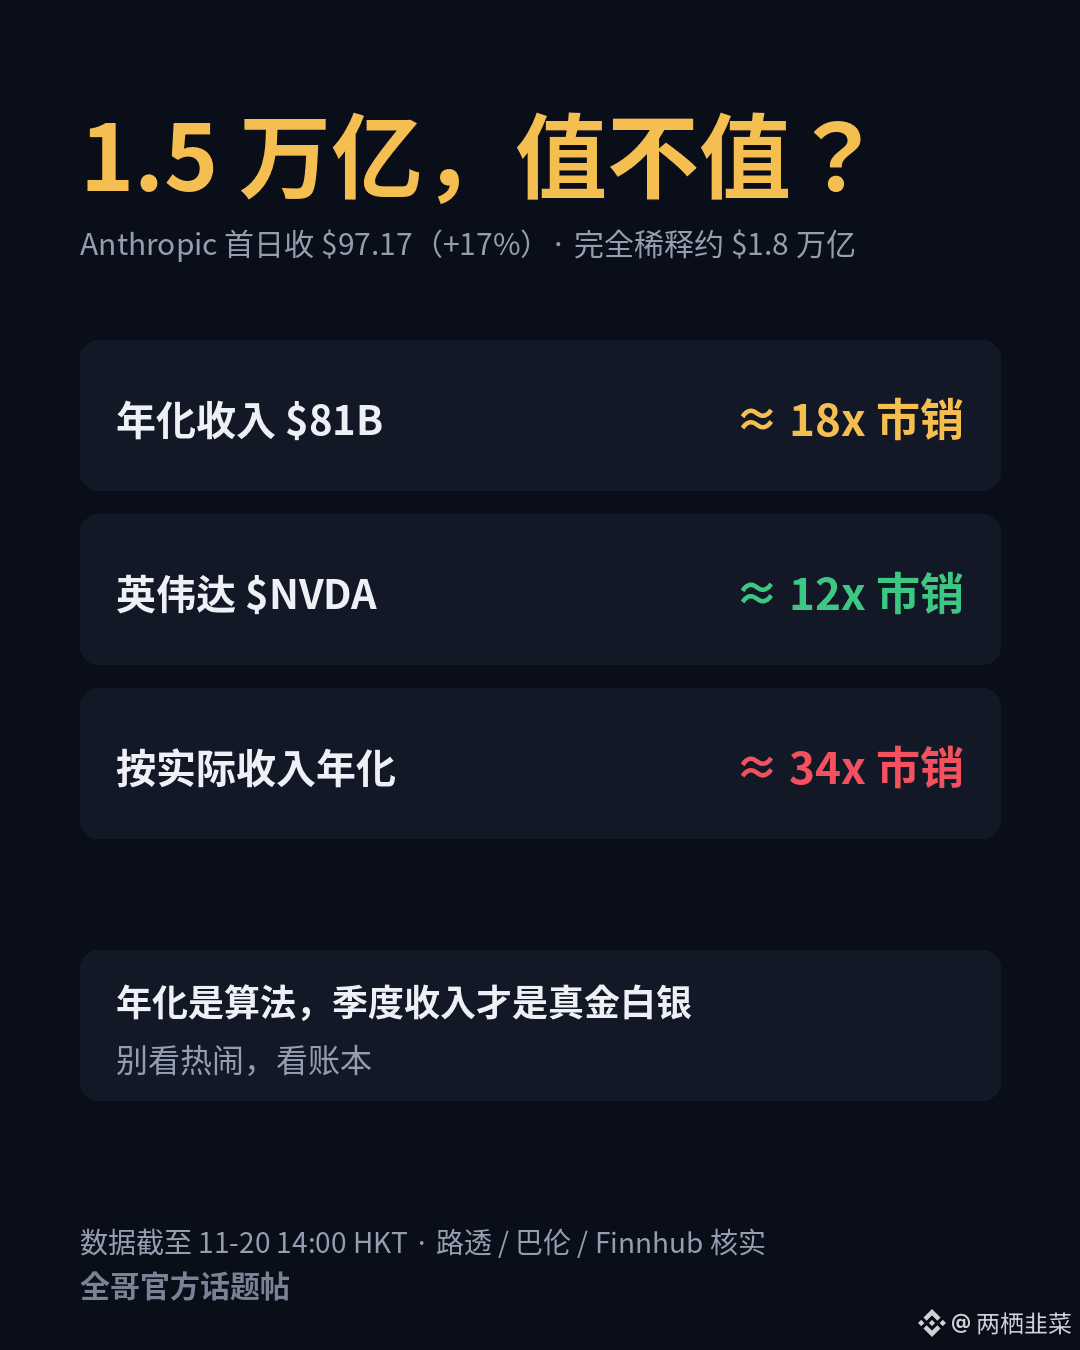
Let’s start with revenue. Reuters says its annualized revenue in October was $81 billion, while actual revenue for the first nine months was $33.2 billion. Based on the $81 billion annualized figure, $1.5 trillion works out to about 18 times sales. What about Nvidia? Around 12 times—and it’s a company with a 75% gross margin. A money-losing lab is trading at a higher price-to-sales ratio than the most profitable chip company.
But there’s a catch: “annualized” revenue isn’t money actually in the bank. Reuters dug into this back in March: the annualized figure comes from multiplying the most recent 28 days of revenue by 13, while actual revenue for all of 2023–2025 combined barely topped $5 billion. Annualize revenue based on actual figures, and the price-to-sales ratio shoots up to around 34 times.
Put simply, whether it’s expensive doesn’t depend on today’s candlestick; it depends on whether that $81 billion in annualized revenue next year turns into real cash. If it doesn’t, this is the peak; if it does, 18 times really isn’t that expensive.
Don’t get distracted by the hype. Look at the books.
#IsAnthropic’s$1.5TMarketCapJustified?
$ANT $NVDA
It closed its first day at $97.17, up 17% from the IPO price of $83. Based on shares outstanding, its market cap is $1.28 trillion; on a fully diluted basis, it’s about $1.8 trillion—the $1.5 trillion figure is based on the IPO price. After hours, it fell nearly 5% to $92.60.
Let’s start with revenue. Reuters says its annualized revenue in October was $81 billion, while actual revenue for the first nine months was $33.2 billion. Based on the $81 billion annualized figure, $1.5 trillion works out to about 18 times sales. What about Nvidia? Around 12 times—and it’s a company with a 75% gross margin. A money-losing lab is trading at a higher price-to-sales ratio than the most profitable chip company.
But there’s a catch: “annualized” revenue isn’t money actually in the bank. Reuters dug into this back in March: the annualized figure comes from multiplying the most recent 28 days of revenue by 13, while actual revenue for all of 2023–2025 combined barely topped $5 billion. Annualize revenue based on actual figures, and the price-to-sales ratio shoots up to around 34 times.
Put simply, whether it’s expensive doesn’t depend on today’s candlestick; it depends on whether that $81 billion in annualized revenue next year turns into real cash. If it doesn’t, this is the peak; if it does, 18 times really isn’t that expensive.
Don’t get distracted by the hype. Look at the books.
#IsAnthropic’s$1.5TMarketCapJustified?
$ANT $NVDA