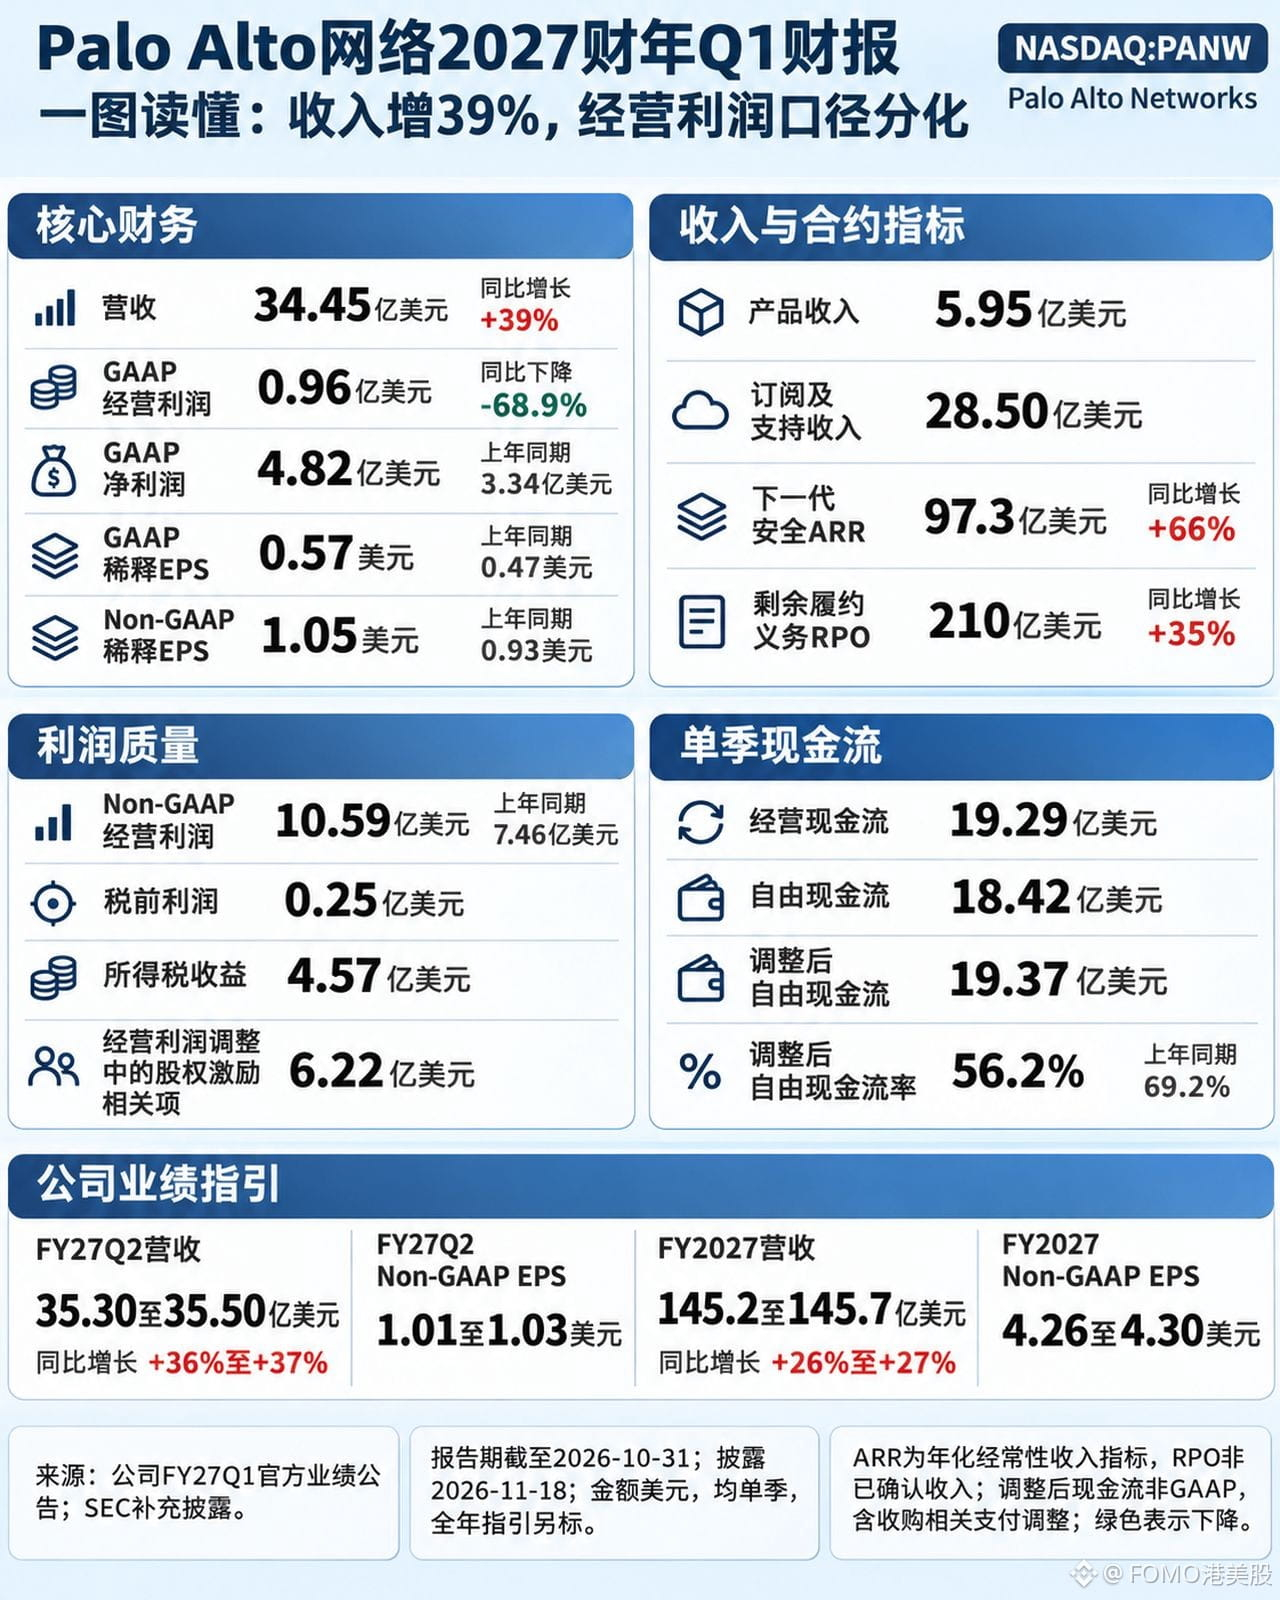
Palo Alto Networks $PANW FY27Q1 revenue was $3.445 billion, up 39%, and ARR rose 66%. The stock gained 9.90% on the 18th, then rose another 9.13% after hours.
Subscription and support revenue was $2.850 billion, and product revenue was $595 million. RPO was $21 billion, up 35%. ARR, RPO, and current-period revenue are three different things and should not be added together.
Profitability was mixed. GAAP operating income was $96 million, compared with $309 million a year earlier, while Non-GAAP operating income was $1.059 billion. GAAP net income of $482 million looks like an increase, but pretax income was only $25 million, propped up by a $457 million income tax benefit. Adjustments also included $622 million in stock-based compensation.
The market is buying subscription growth, not that $457 million tax benefit.
It is valuing recurring revenue: ARR of $9.73 billion, up 66%. The stock remains 20% below its 52-week high of $432.33, and the 9.13% after-hours gain is a bet on full-year revenue of $14.5 billion and growth of 26% to 27%. The direction is right—subscriptions are accelerating—but GAAP operating income fell nearly 70%, and the adjusted free cash flow margin dropped from 69.2% to 56.2%. Full-year guidance is only 38%. If Q2 revenue of $3.53 billion to $3.55 billion falls short of expectations, the rally will have a reason to give back its gains.
The key variable is converting growth into profit. GAAP operating income needs to catch up with the adjusted figure of $1.059 billion; stock-based compensation cannot keep being wiped away through adjustments.
#BStocks #美股财报 #股票财报季
Subscription and support revenue was $2.850 billion, and product revenue was $595 million. RPO was $21 billion, up 35%. ARR, RPO, and current-period revenue are three different things and should not be added together.
Profitability was mixed. GAAP operating income was $96 million, compared with $309 million a year earlier, while Non-GAAP operating income was $1.059 billion. GAAP net income of $482 million looks like an increase, but pretax income was only $25 million, propped up by a $457 million income tax benefit. Adjustments also included $622 million in stock-based compensation.
The market is buying subscription growth, not that $457 million tax benefit.
It is valuing recurring revenue: ARR of $9.73 billion, up 66%. The stock remains 20% below its 52-week high of $432.33, and the 9.13% after-hours gain is a bet on full-year revenue of $14.5 billion and growth of 26% to 27%. The direction is right—subscriptions are accelerating—but GAAP operating income fell nearly 70%, and the adjusted free cash flow margin dropped from 69.2% to 56.2%. Full-year guidance is only 38%. If Q2 revenue of $3.53 billion to $3.55 billion falls short of expectations, the rally will have a reason to give back its gains.
The key variable is converting growth into profit. GAAP operating income needs to catch up with the adjusted figure of $1.059 billion; stock-based compensation cannot keep being wiped away through adjustments.
#BStocks #美股财报 #股票财报季