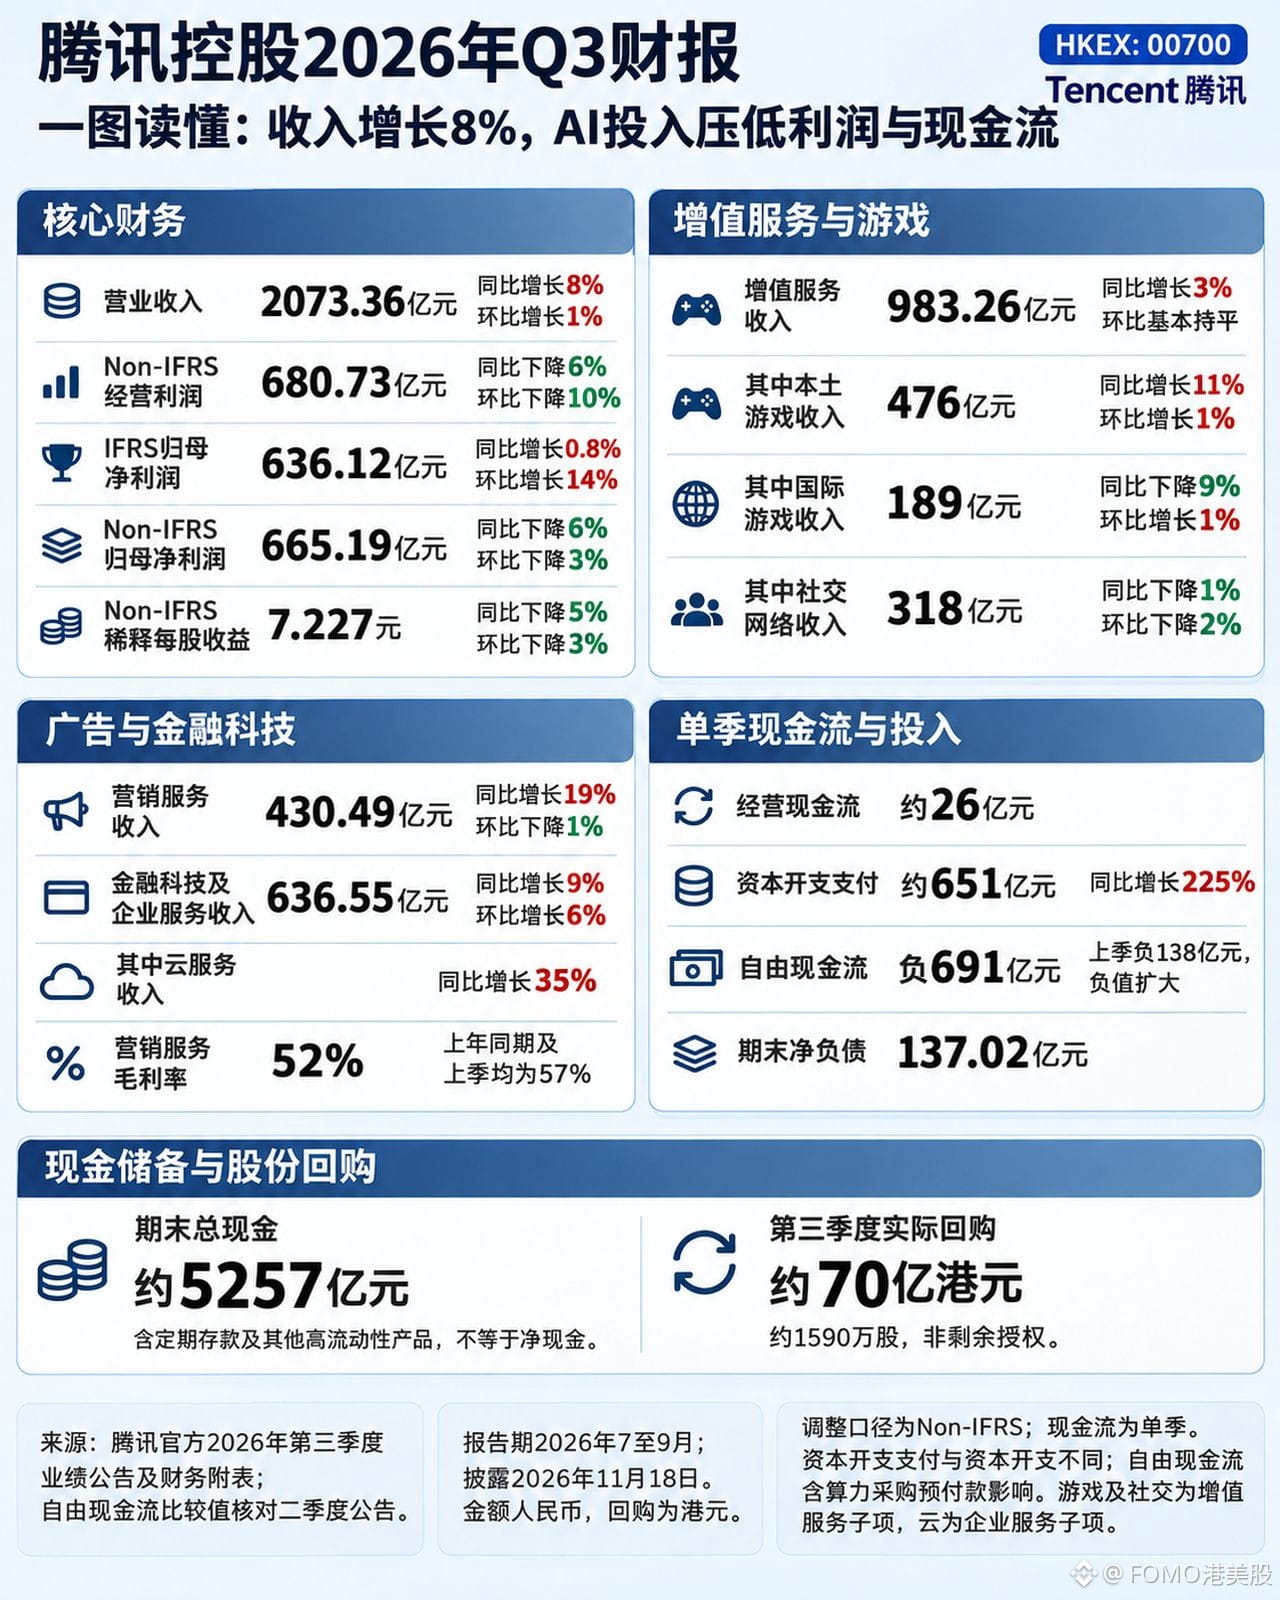
Tencent Holdings $TENCENT Q3 revenue was 207.336 billion yuan, up 8%, but adjusted operating profit fell 6%. The stock closed at HK$372.80 on the 18th, near its 52-week low and down 40% from its high.
Domestic gaming revenue was 47.6 billion yuan, up 11%, supported by Delta Force and Valorant. Advertising revenue was 43.049 billion yuan, up 19%, while cloud revenue grew 35%. But advertising gross margin fell from 57% to 52%, which the company attributed to AI operations and micro-drama costs.
Investment ate into profits. Excluding new AI products, operating profit was 83.3 billion yuan, up 8%; on a group basis, however, it fell 6%. The difference reflects investment in models and inference. Operating cash flow plunged from 52.7 billion yuan last quarter to 2.6 billion yuan, while free cash flow widened from negative 13.8 billion yuan to negative 69.1 billion yuan. The company went from net cash of 58.191 billion yuan to net debt of 13.702 billion yuan.
The market is pricing in costs.
It is looking at returns on capital: quarterly capex of 65.1 billion yuan is 25 times operating cash flow of 2.6 billion yuan. At this rate, the money is all turning into computing power. But while the market got the direction right, it has probably gone too far: profit excluding AI is still up 8%, advertising is up 19%, and cloud is up 35%—all accelerating—yet the 40% pullback has priced growth at zero. If Q4 capex stays above 65 billion yuan and free cash flow cannot hold above negative 60 billion yuan, then the market was right to sell. Only if cash flow narrows and cloud growth holds above 30% can we say the sell-off went too far.
The key variable is paid conversion. Whether increased usage turns into paid demand will determine if advertising and cloud can cover the investment.
#腾讯 #BStocks #股票财报季
Domestic gaming revenue was 47.6 billion yuan, up 11%, supported by Delta Force and Valorant. Advertising revenue was 43.049 billion yuan, up 19%, while cloud revenue grew 35%. But advertising gross margin fell from 57% to 52%, which the company attributed to AI operations and micro-drama costs.
Investment ate into profits. Excluding new AI products, operating profit was 83.3 billion yuan, up 8%; on a group basis, however, it fell 6%. The difference reflects investment in models and inference. Operating cash flow plunged from 52.7 billion yuan last quarter to 2.6 billion yuan, while free cash flow widened from negative 13.8 billion yuan to negative 69.1 billion yuan. The company went from net cash of 58.191 billion yuan to net debt of 13.702 billion yuan.
The market is pricing in costs.
It is looking at returns on capital: quarterly capex of 65.1 billion yuan is 25 times operating cash flow of 2.6 billion yuan. At this rate, the money is all turning into computing power. But while the market got the direction right, it has probably gone too far: profit excluding AI is still up 8%, advertising is up 19%, and cloud is up 35%—all accelerating—yet the 40% pullback has priced growth at zero. If Q4 capex stays above 65 billion yuan and free cash flow cannot hold above negative 60 billion yuan, then the market was right to sell. Only if cash flow narrows and cloud growth holds above 30% can we say the sell-off went too far.
The key variable is paid conversion. Whether increased usage turns into paid demand will determine if advertising and cloud can cover the investment.
#腾讯 #BStocks #股票财报季