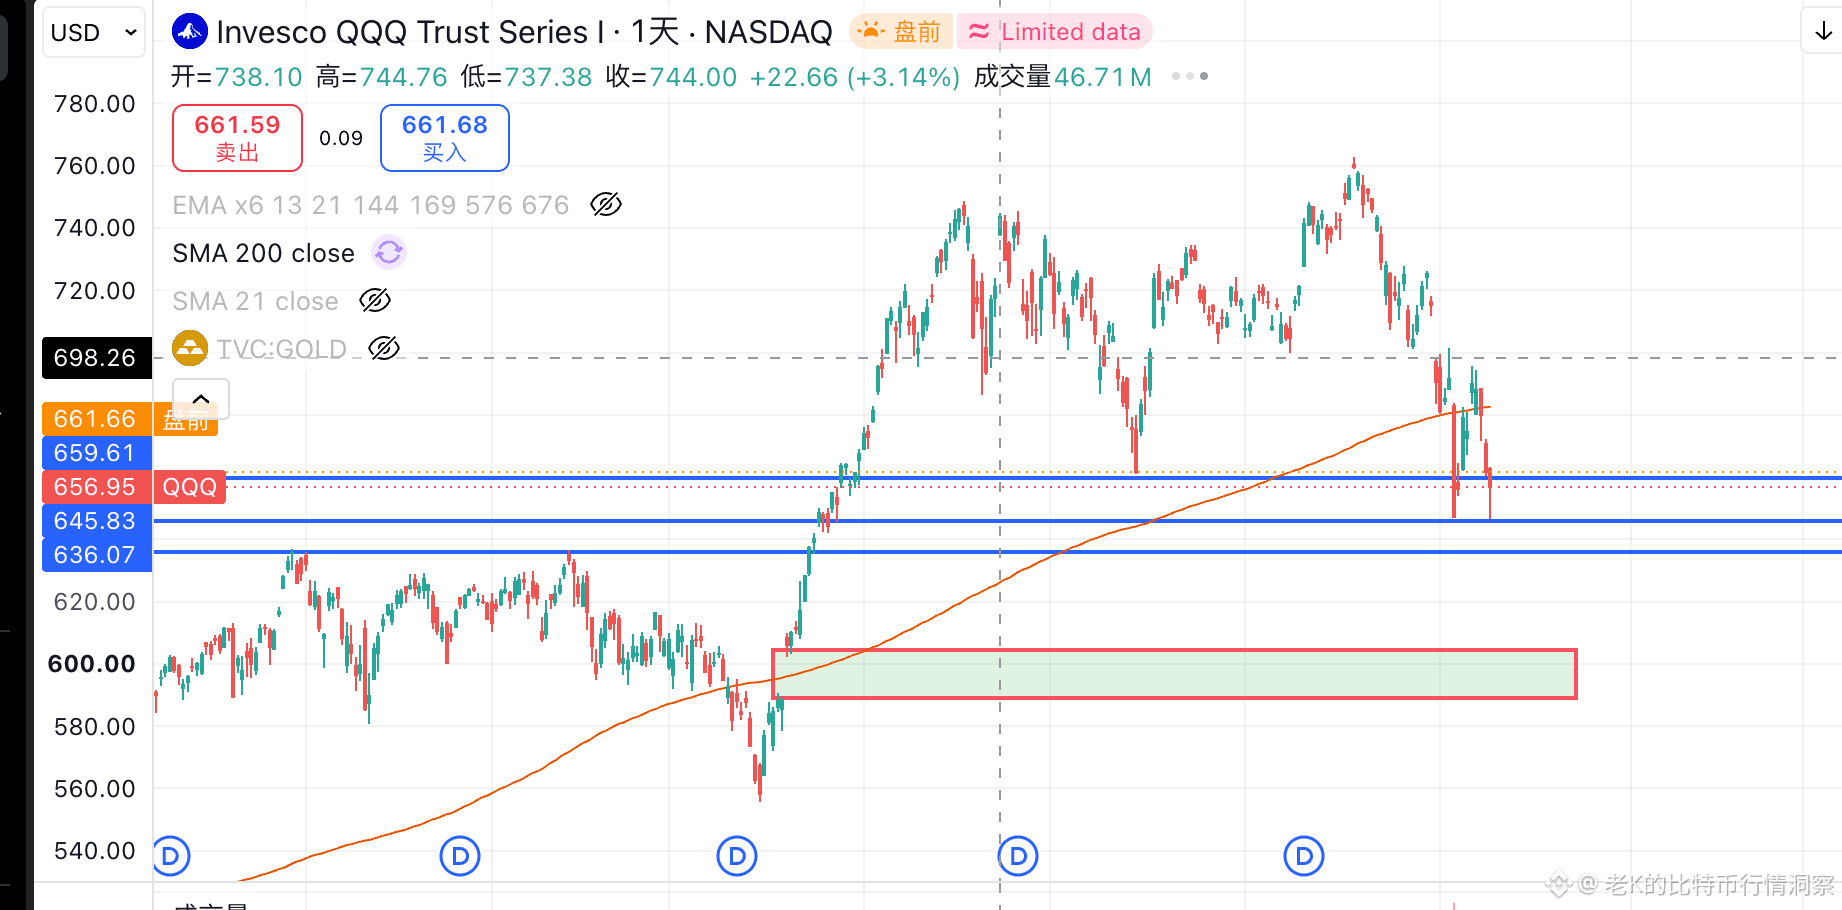
Turning to U.S. stocks, NVIDIA’s third-quarter results are now officially out, giving the market a bit of breathing room overall: quarterly revenue was $115.8 billion, up 103% year over year, and adjusted EPS was $2.68—beating market expectations by 6% and 9%, respectively. But the results were hardly dazzling. The data center business met expectations, but hyperscalers’ share rose to 56%, customer diversification fell short of expectations, and Rubin’s share of revenue did not meet previous guidance. On top of that, free cash flow was far below expectations, and the CFO gave a vague response to guidance for 100% growth. Old K believes this is merely a short-term “relief” rally; valuations remain under pressure in the medium to long term, so it is not yet advisable to enter the market and speculate.
Meanwhile, Federal Reserve officials have recently turned increasingly hawkish, with Musalem even saying that real interest rates could rise by 1% before next spring. Hawkish sentiment has reached a near-term peak. But the market has probably entered the final stretch of the hawkish cycle. There may still be room for a short-term decline, which is essentially building momentum for a subsequent rally. Morgan Stanley’s Wilson also noted that this correction has entered its final phase, with a 12-month S&P 500 target of 8,700. If AI capital expenditure growth next year comes close to Morgan Stanley’s forecast of 60%, there is still room for valuation recovery. In a nutshell, the recent pullback will continue, but it is nearing its end—unlike Bitcoin, which is highly unlikely to return fully to a bear market. $QQQB
Meanwhile, Federal Reserve officials have recently turned increasingly hawkish, with Musalem even saying that real interest rates could rise by 1% before next spring. Hawkish sentiment has reached a near-term peak. But the market has probably entered the final stretch of the hawkish cycle. There may still be room for a short-term decline, which is essentially building momentum for a subsequent rally. Morgan Stanley’s Wilson also noted that this correction has entered its final phase, with a 12-month S&P 500 target of 8,700. If AI capital expenditure growth next year comes close to Morgan Stanley’s forecast of 60%, there is still room for valuation recovery. In a nutshell, the recent pullback will continue, but it is nearing its end—unlike Bitcoin, which is highly unlikely to return fully to a bear market. $QQQB