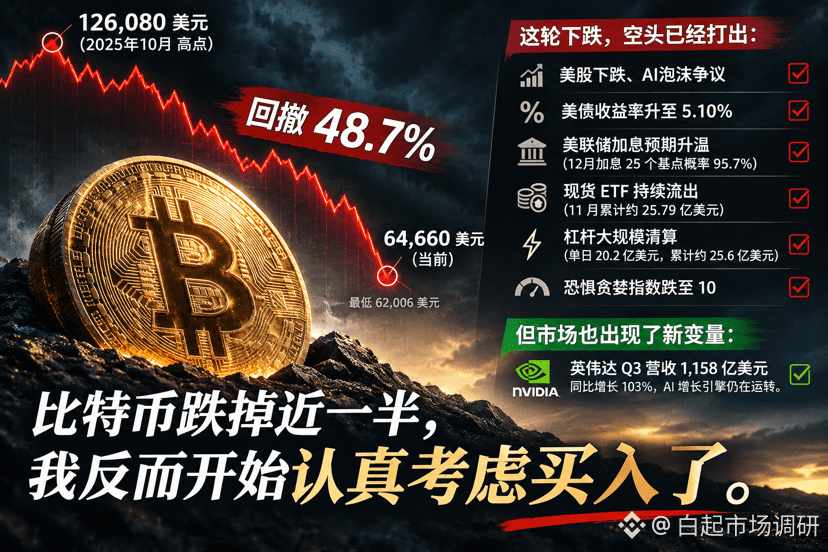
$BTC reported $64,660, down 48.7% from its October 2025 peak of $126,080. The S&P 500 closed at 7,340.53, a five-month low; the Nasdaq at 24,328.38, its fourth consecutive down session; and the Dow at 50,759.42.
#英伟达财报大超预期,Q4营收展望1300亿美元
Bulls are just one rallying cry away:
NVIDIA (NVDA) reported third-quarter revenue of $115.8 billion and adjusted EPS of $2.68, with fourth-quarter guidance of $130 billion. Shares rose as much as 4.8% after hours. The good news is out; the market is missing a consensus. A 25-basis-point Fed rate hike on December 9 is already fully priced in. The moment the uncertainty is resolved will be the signal for capital to regroup.
#AnthropicIPO需求强劲,发行价或超80美元
The bears have nearly exhausted their ammunition:
From November 5 to 15, $2.56 billion in long positions were liquidated, including $2.02 billion in a single day. Bitcoin bottomed at $62,006 over the weekend, with a daily RSI of 22.96, a Fear & Greed Index reading of 10, and funding rates turning negative. Spot ETFs saw cumulative outflows of about $2.1 billion in November. Yesterday, outflows were just $30.4 million, compared with $185.4 million last Friday.
Driving the price below $62,000 again would require fresh bearish catalysts: a 50-basis-point Fed rate hike (currently about a 4% probability), a further surge in the 10-year Treasury yield from 5.10%, or an AI narrative collapse dragging down the Nasdaq. If none of these materialize, selling pressure is just the existing supply—and it will thin out the more prices are pushed down.
#英伟达财报大超预期,Q4营收展望1300亿美元
Bulls are just one rallying cry away:
NVIDIA (NVDA) reported third-quarter revenue of $115.8 billion and adjusted EPS of $2.68, with fourth-quarter guidance of $130 billion. Shares rose as much as 4.8% after hours. The good news is out; the market is missing a consensus. A 25-basis-point Fed rate hike on December 9 is already fully priced in. The moment the uncertainty is resolved will be the signal for capital to regroup.
#AnthropicIPO需求强劲,发行价或超80美元
The bears have nearly exhausted their ammunition:
From November 5 to 15, $2.56 billion in long positions were liquidated, including $2.02 billion in a single day. Bitcoin bottomed at $62,006 over the weekend, with a daily RSI of 22.96, a Fear & Greed Index reading of 10, and funding rates turning negative. Spot ETFs saw cumulative outflows of about $2.1 billion in November. Yesterday, outflows were just $30.4 million, compared with $185.4 million last Friday.
Driving the price below $62,000 again would require fresh bearish catalysts: a 50-basis-point Fed rate hike (currently about a 4% probability), a further surge in the 10-year Treasury yield from 5.10%, or an AI narrative collapse dragging down the Nasdaq. If none of these materialize, selling pressure is just the existing supply—and it will thin out the more prices are pushed down.