Institutional Money Is Increasing Its Exposure To Michael Saylor's Strategy.
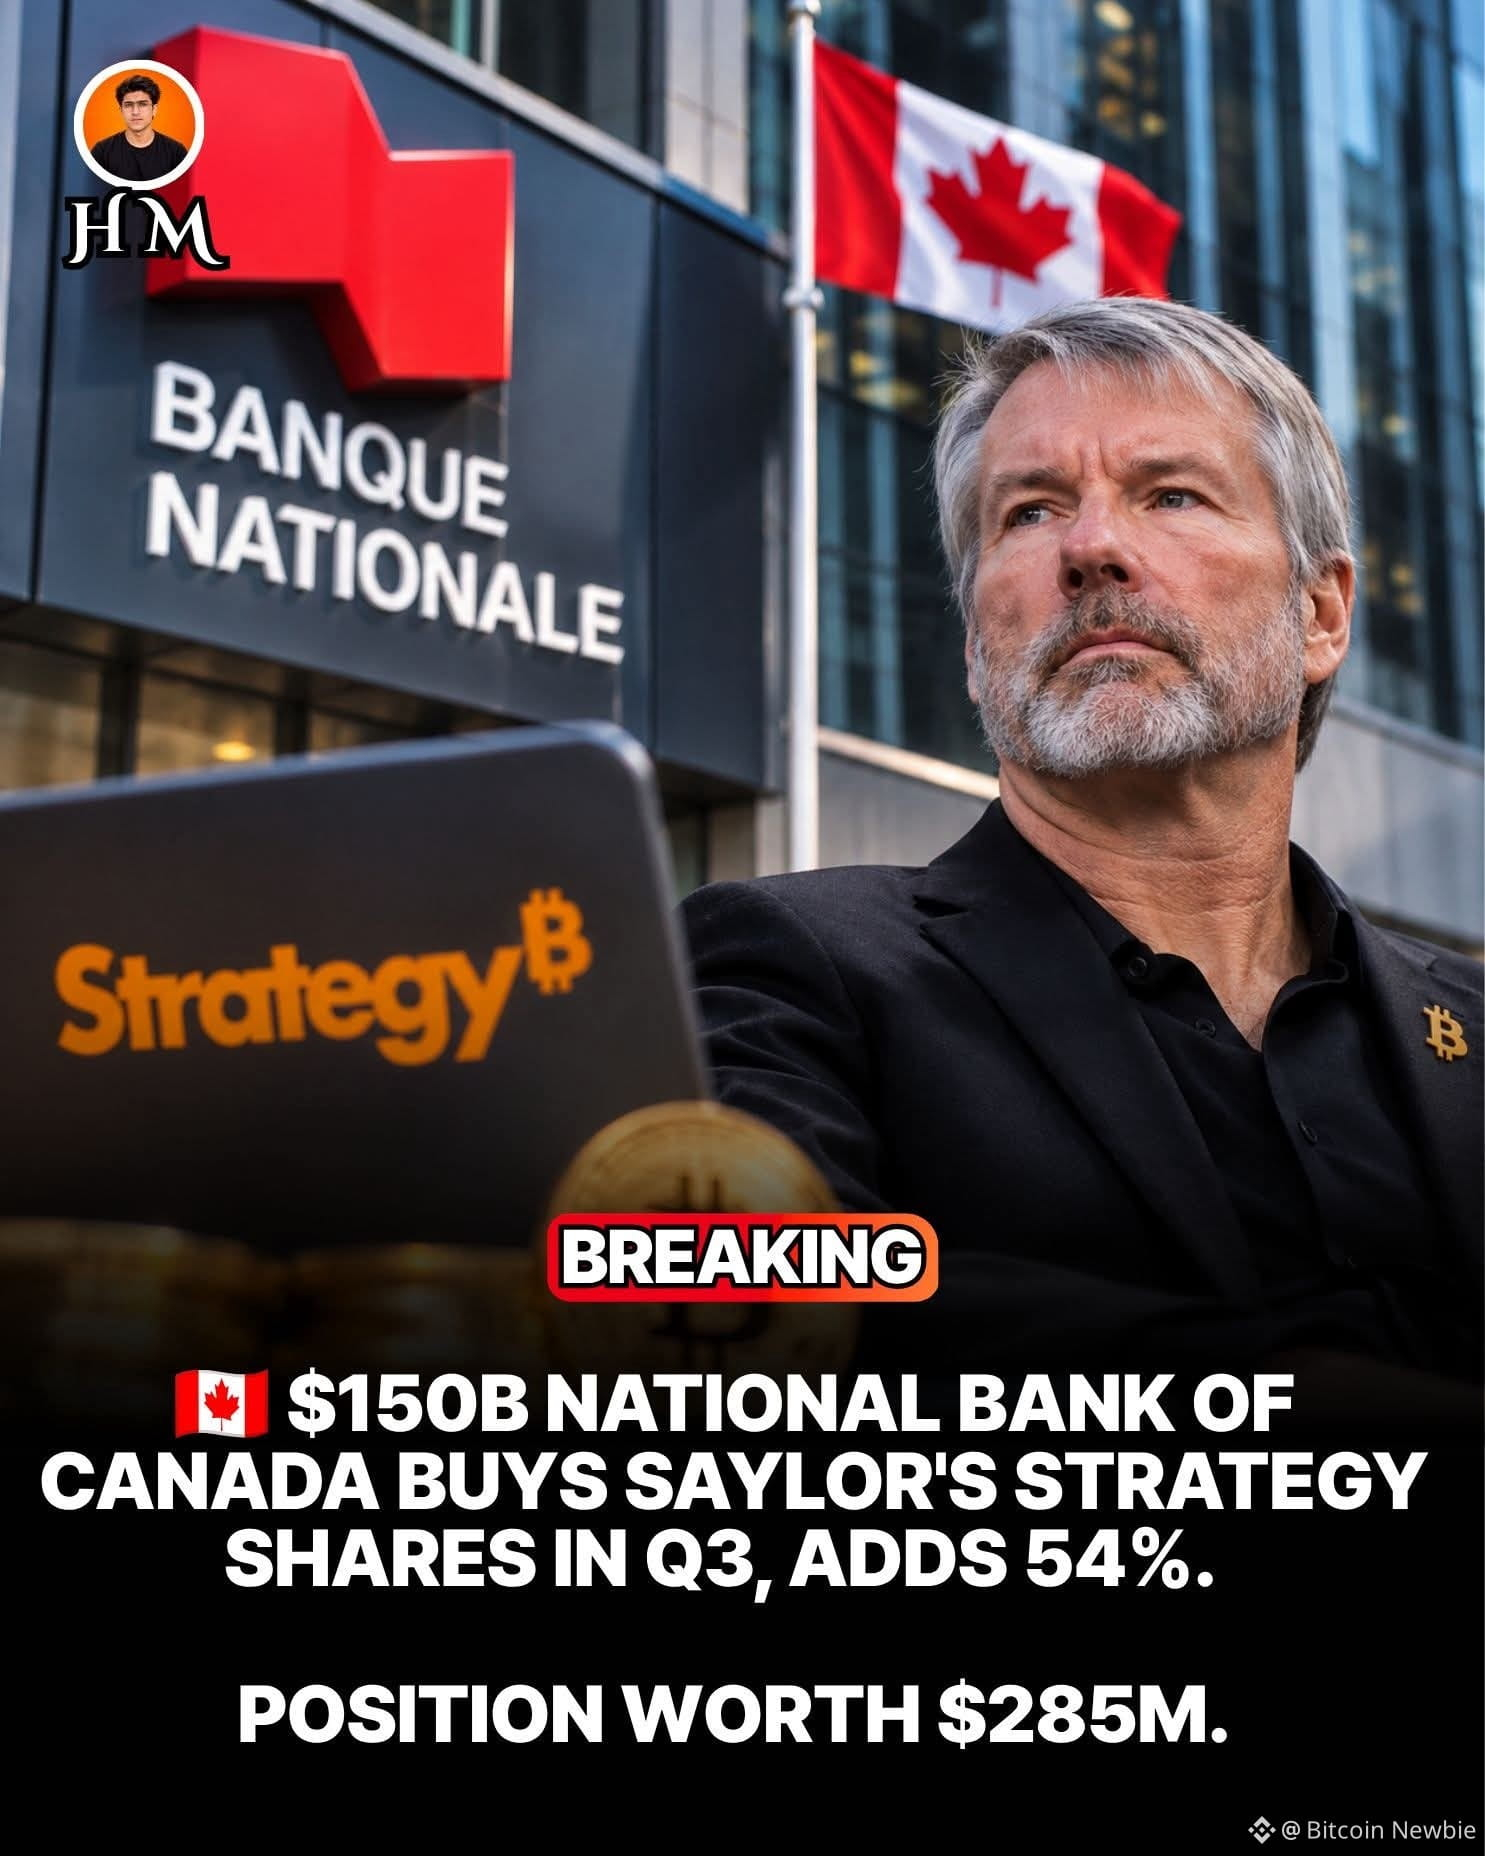
National Bank of Canada's latest SEC filing reveals a notable change in its Strategy (MSTR) position.
By September 30, 2026, the reported holding had reached approximately 1.897 million shares, valued at nearly $287.9 million.
That represents a roughly 52.9% increase in share count compared with the previous quarter.
But there is a financial detail worth understanding.
An increase in the number of shares is different from an increase in the dollar value of a position.
If a fund owns more shares, it has increased its reported exposure to that company, regardless of whether the share price also moved.
Why does this matter?
Strategy is not a traditional operating company anymore.
Its business model increasingly revolves around raising capital, issuing securities and using that capital to accumulate Bitcoin.
Its stock therefore carries exposure to both the company's capital structure and Bitcoin's market performance.
For investors, that creates an additional layer of risk.
If Bitcoin appreciates, Strategy may benefit from its large BTC reserve.
But falling Bitcoin prices, financing costs, debt obligations and dilution can put pressure on MSTR shareholders.
There is another important distinction.
A 13F filing reports institutional holdings at a quarter-end date. It does not reveal the investor's exact motivation, and the reported position may represent managed investment assets rather than the bank's own capital.
So this filing is evidence of increased institutional exposure, not proof that the bank expects Bitcoin to rise.
The interesting question is not just who bought more, but what risks they are taking to own it.
#StrategyBTCPurchase #BitcoinExtendsLosingStreakToSixWeeks #AnthropicIPOTestsInvestorAppetiteForAI #CaliforniaVotersBackProp42BarringNewCryptoTaxes #BuyTheDip
$BTC
$ETH
$XRP
National Bank of Canada's latest SEC filing reveals a notable change in its Strategy (MSTR) position.
By September 30, 2026, the reported holding had reached approximately 1.897 million shares, valued at nearly $287.9 million.
That represents a roughly 52.9% increase in share count compared with the previous quarter.
But there is a financial detail worth understanding.
An increase in the number of shares is different from an increase in the dollar value of a position.
If a fund owns more shares, it has increased its reported exposure to that company, regardless of whether the share price also moved.
Why does this matter?
Strategy is not a traditional operating company anymore.
Its business model increasingly revolves around raising capital, issuing securities and using that capital to accumulate Bitcoin.
Its stock therefore carries exposure to both the company's capital structure and Bitcoin's market performance.
For investors, that creates an additional layer of risk.
If Bitcoin appreciates, Strategy may benefit from its large BTC reserve.
But falling Bitcoin prices, financing costs, debt obligations and dilution can put pressure on MSTR shareholders.
There is another important distinction.
A 13F filing reports institutional holdings at a quarter-end date. It does not reveal the investor's exact motivation, and the reported position may represent managed investment assets rather than the bank's own capital.
So this filing is evidence of increased institutional exposure, not proof that the bank expects Bitcoin to rise.
The interesting question is not just who bought more, but what risks they are taking to own it.
#StrategyBTCPurchase #BitcoinExtendsLosingStreakToSixWeeks #AnthropicIPOTestsInvestorAppetiteForAI #CaliforniaVotersBackProp42BarringNewCryptoTaxes #BuyTheDip
$BTC
$ETH
$XRP