Monday Market Preview: Two major weekend developments—watch these two themes at the open tonight.
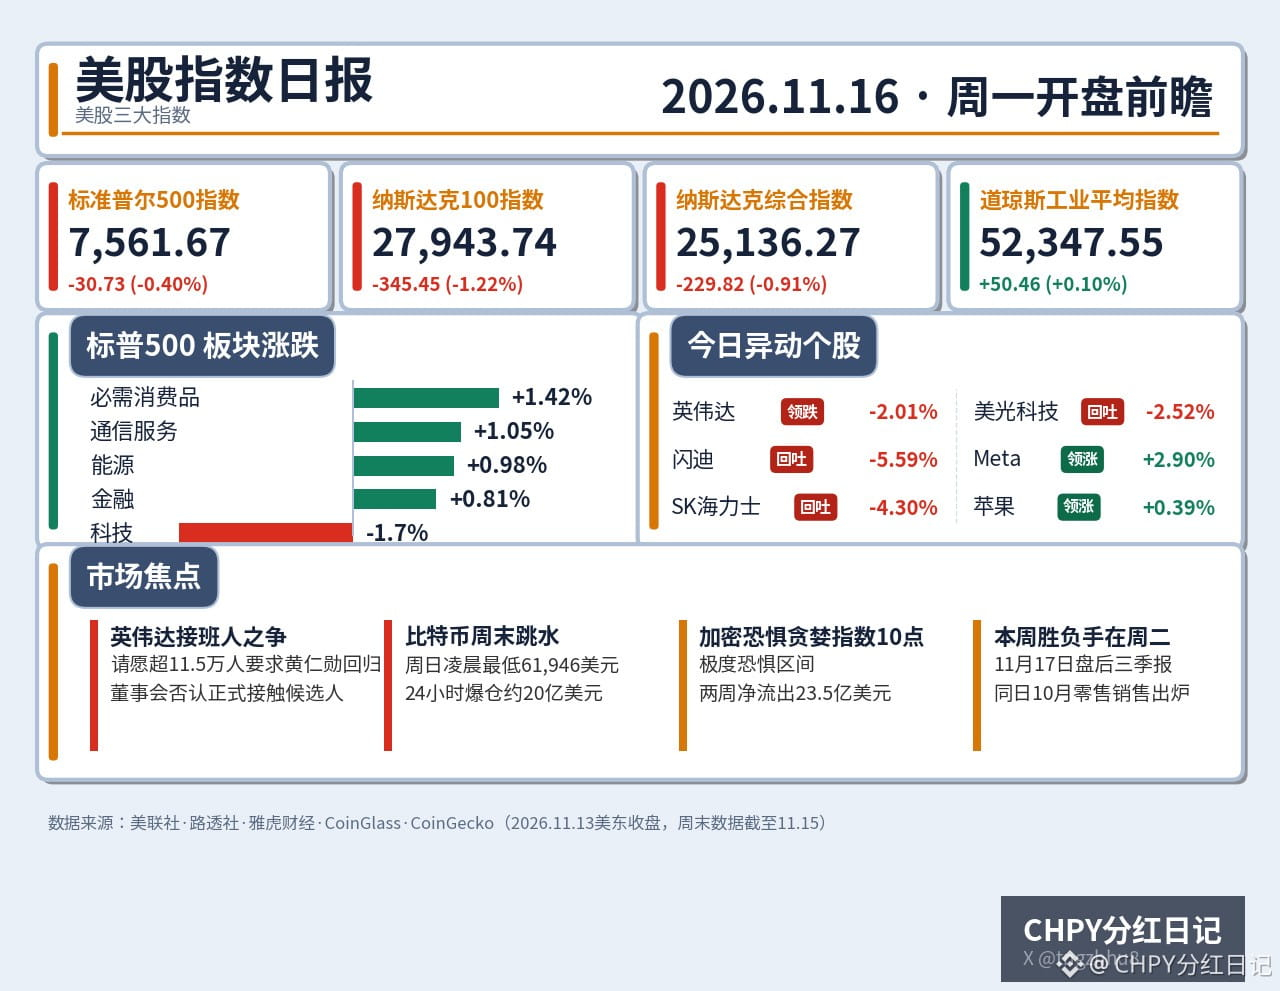
First, anchor on Friday’s close. The S&P 500 closed at 7,561.67, down 0.40%; the Nasdaq 100 closed at 27,943.74, down 1.22%; the Nasdaq Composite closed at 25,136.27, down 0.91%; and the Dow Jones Industrial Average closed at 52,347.55, up 0.10%. Stocks fell all day Friday, but all three indexes still rose for the week: the S&P 500 gained 2.51%, the Nasdaq Composite rose 2.27%, and the Dow Jones Industrial Average added 2.07%—the best week since early August. Technically, the S&P 500 closed below its 20-day and 50-day moving averages. Its 14-day relative strength index stood at 44.9—not yet oversold, but bulls have lost the short-term moving averages. Minutes before the close, the Federal Aviation Administration ordered a nationwide ground stop for U.S. flights, adding to Friday’s turmoil.
The first weekend story: Nvidia’s succession battle is being pulled in two directions. The Financial Times reported that the board had approached Arm CEO Rene Haas as a potential successor to Jensen Huang. The board promptly denied this to CNBC, saying it had not formally approached any candidates and was still selecting an executive search firm; it was too early to discuss specific names. On the other hand, a petition calling for Huang to return surpassed 115,000 signatures over the weekend. The petition site says about 5,965 current employees signed it, and Tesla CEO Elon Musk was among them. Two major investors wrote to the board, urging it to keep open the option of Huang’s return. Prediction markets currently favor internal engineer Ian Buck, at about 33%. Nvidia fell another 2.01% Friday to close at $162.85, down 12.75% for the week. It has now fallen for six consecutive weeks, its longest losing streak since 2012, and its market capitalization has dropped below $4 trillion.
The second weekend story: Bitcoin plunged. It was around $68,839 when U.S. stocks closed Friday, then slid through Saturday to a low of $61,946 early Sunday—down about 10% from Friday’s close—before recovering to around $64,500 by Sunday evening. About $2 billion in crypto positions were liquidated across the market over 24 hours, including $1.68 billion in long positions. The Crypto Fear & Greed Index was just 10 on Sunday, in the extreme fear zone. Spot Bitcoin exchange-traded funds saw net outflows of $2.35 billion over two weeks, and Bitcoin has fallen below its 200-day moving average, around $73,000. ETF flows on Monday will be the first test of how solid this rebound is.
These two stories are really driven by the same impulse: confidence in the AI narrative is wavering, rate-hike expectations are weighing on markets, and risk appetite is draining first from the most fragile areas. October’s Consumer Price Index rose 0.40% month over month, above the expected 0.30%. October’s Producer Price Index rose 6.50% year over year. The CME FedWatch Tool puts the probability of a 25-basis-point rate hike in December at about 87%, and the 10-year Treasury yield has climbed above 5.10%. But one detail from last Friday is worth noting: the indexes fell, yet more than 60% of S&P 500 constituents closed higher. Money is rotating, not retreating.
Four things to watch this week: Monday at noon, remarks from Fed Chair Warsh; Tuesday, October retail sales, with the market expecting a 0.20% month-over-month increase, followed after the close by Nvidia’s third-quarter earnings, with revenue expected to be around $108 billion and options markets implying an 8% to 9% share-price move; Wednesday, minutes from the October Federal Open Market Committee meeting; Thursday, Walmart’s premarket earnings report, with Anthropic expected to go public.
The two cold showers over the weekend won’t erase the foundation of last week’s rebound, but they’ve pushed all the suspense to Tuesday. Can Nvidia’s earnings revive the AI narrative? Will retail sales add fuel to rate-hike expectations? The week’s direction won’t be clear until we have answers to both.
#美股 #Bitcoin
$NVDA $QQQ $SPY
First, anchor on Friday’s close. The S&P 500 closed at 7,561.67, down 0.40%; the Nasdaq 100 closed at 27,943.74, down 1.22%; the Nasdaq Composite closed at 25,136.27, down 0.91%; and the Dow Jones Industrial Average closed at 52,347.55, up 0.10%. Stocks fell all day Friday, but all three indexes still rose for the week: the S&P 500 gained 2.51%, the Nasdaq Composite rose 2.27%, and the Dow Jones Industrial Average added 2.07%—the best week since early August. Technically, the S&P 500 closed below its 20-day and 50-day moving averages. Its 14-day relative strength index stood at 44.9—not yet oversold, but bulls have lost the short-term moving averages. Minutes before the close, the Federal Aviation Administration ordered a nationwide ground stop for U.S. flights, adding to Friday’s turmoil.
The first weekend story: Nvidia’s succession battle is being pulled in two directions. The Financial Times reported that the board had approached Arm CEO Rene Haas as a potential successor to Jensen Huang. The board promptly denied this to CNBC, saying it had not formally approached any candidates and was still selecting an executive search firm; it was too early to discuss specific names. On the other hand, a petition calling for Huang to return surpassed 115,000 signatures over the weekend. The petition site says about 5,965 current employees signed it, and Tesla CEO Elon Musk was among them. Two major investors wrote to the board, urging it to keep open the option of Huang’s return. Prediction markets currently favor internal engineer Ian Buck, at about 33%. Nvidia fell another 2.01% Friday to close at $162.85, down 12.75% for the week. It has now fallen for six consecutive weeks, its longest losing streak since 2012, and its market capitalization has dropped below $4 trillion.
The second weekend story: Bitcoin plunged. It was around $68,839 when U.S. stocks closed Friday, then slid through Saturday to a low of $61,946 early Sunday—down about 10% from Friday’s close—before recovering to around $64,500 by Sunday evening. About $2 billion in crypto positions were liquidated across the market over 24 hours, including $1.68 billion in long positions. The Crypto Fear & Greed Index was just 10 on Sunday, in the extreme fear zone. Spot Bitcoin exchange-traded funds saw net outflows of $2.35 billion over two weeks, and Bitcoin has fallen below its 200-day moving average, around $73,000. ETF flows on Monday will be the first test of how solid this rebound is.
These two stories are really driven by the same impulse: confidence in the AI narrative is wavering, rate-hike expectations are weighing on markets, and risk appetite is draining first from the most fragile areas. October’s Consumer Price Index rose 0.40% month over month, above the expected 0.30%. October’s Producer Price Index rose 6.50% year over year. The CME FedWatch Tool puts the probability of a 25-basis-point rate hike in December at about 87%, and the 10-year Treasury yield has climbed above 5.10%. But one detail from last Friday is worth noting: the indexes fell, yet more than 60% of S&P 500 constituents closed higher. Money is rotating, not retreating.
Four things to watch this week: Monday at noon, remarks from Fed Chair Warsh; Tuesday, October retail sales, with the market expecting a 0.20% month-over-month increase, followed after the close by Nvidia’s third-quarter earnings, with revenue expected to be around $108 billion and options markets implying an 8% to 9% share-price move; Wednesday, minutes from the October Federal Open Market Committee meeting; Thursday, Walmart’s premarket earnings report, with Anthropic expected to go public.
The two cold showers over the weekend won’t erase the foundation of last week’s rebound, but they’ve pushed all the suspense to Tuesday. Can Nvidia’s earnings revive the AI narrative? Will retail sales add fuel to rate-hike expectations? The week’s direction won’t be clear until we have answers to both.
#美股 #Bitcoin
$NVDA $QQQ $SPY