
Daily Perpetuals Order Book|11/16: Rebound Without a Return of Aggressive Buying
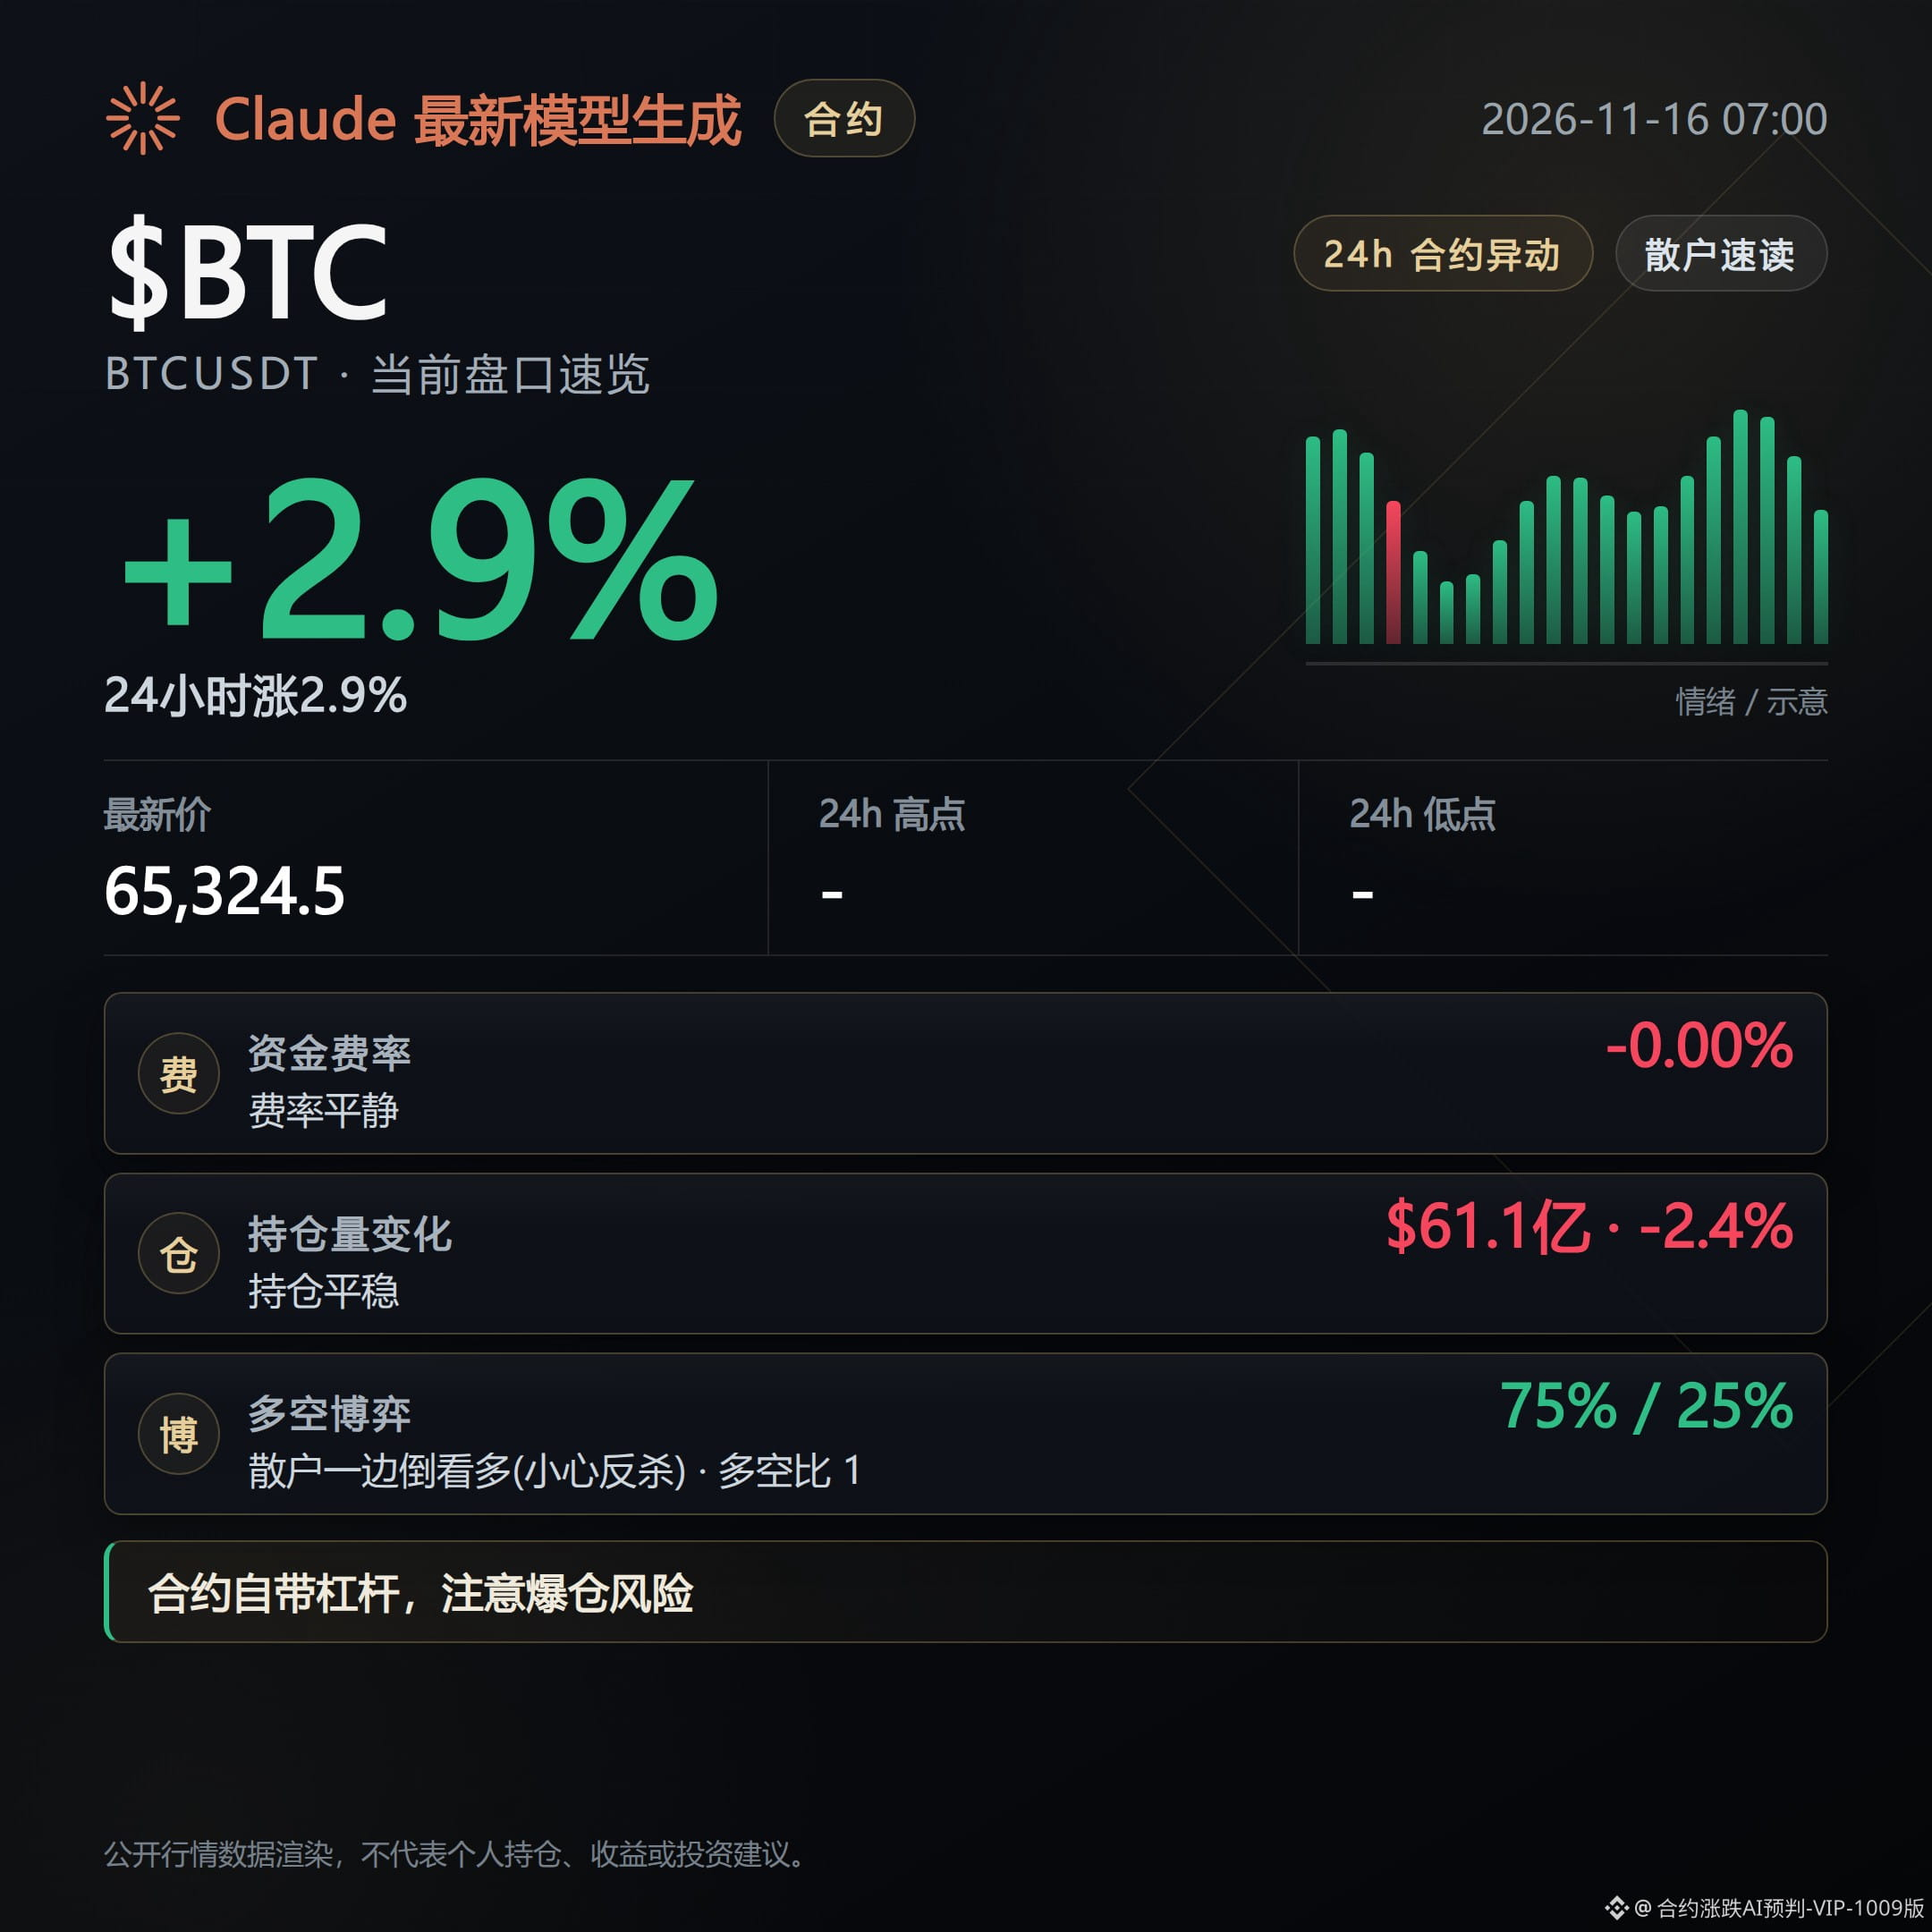
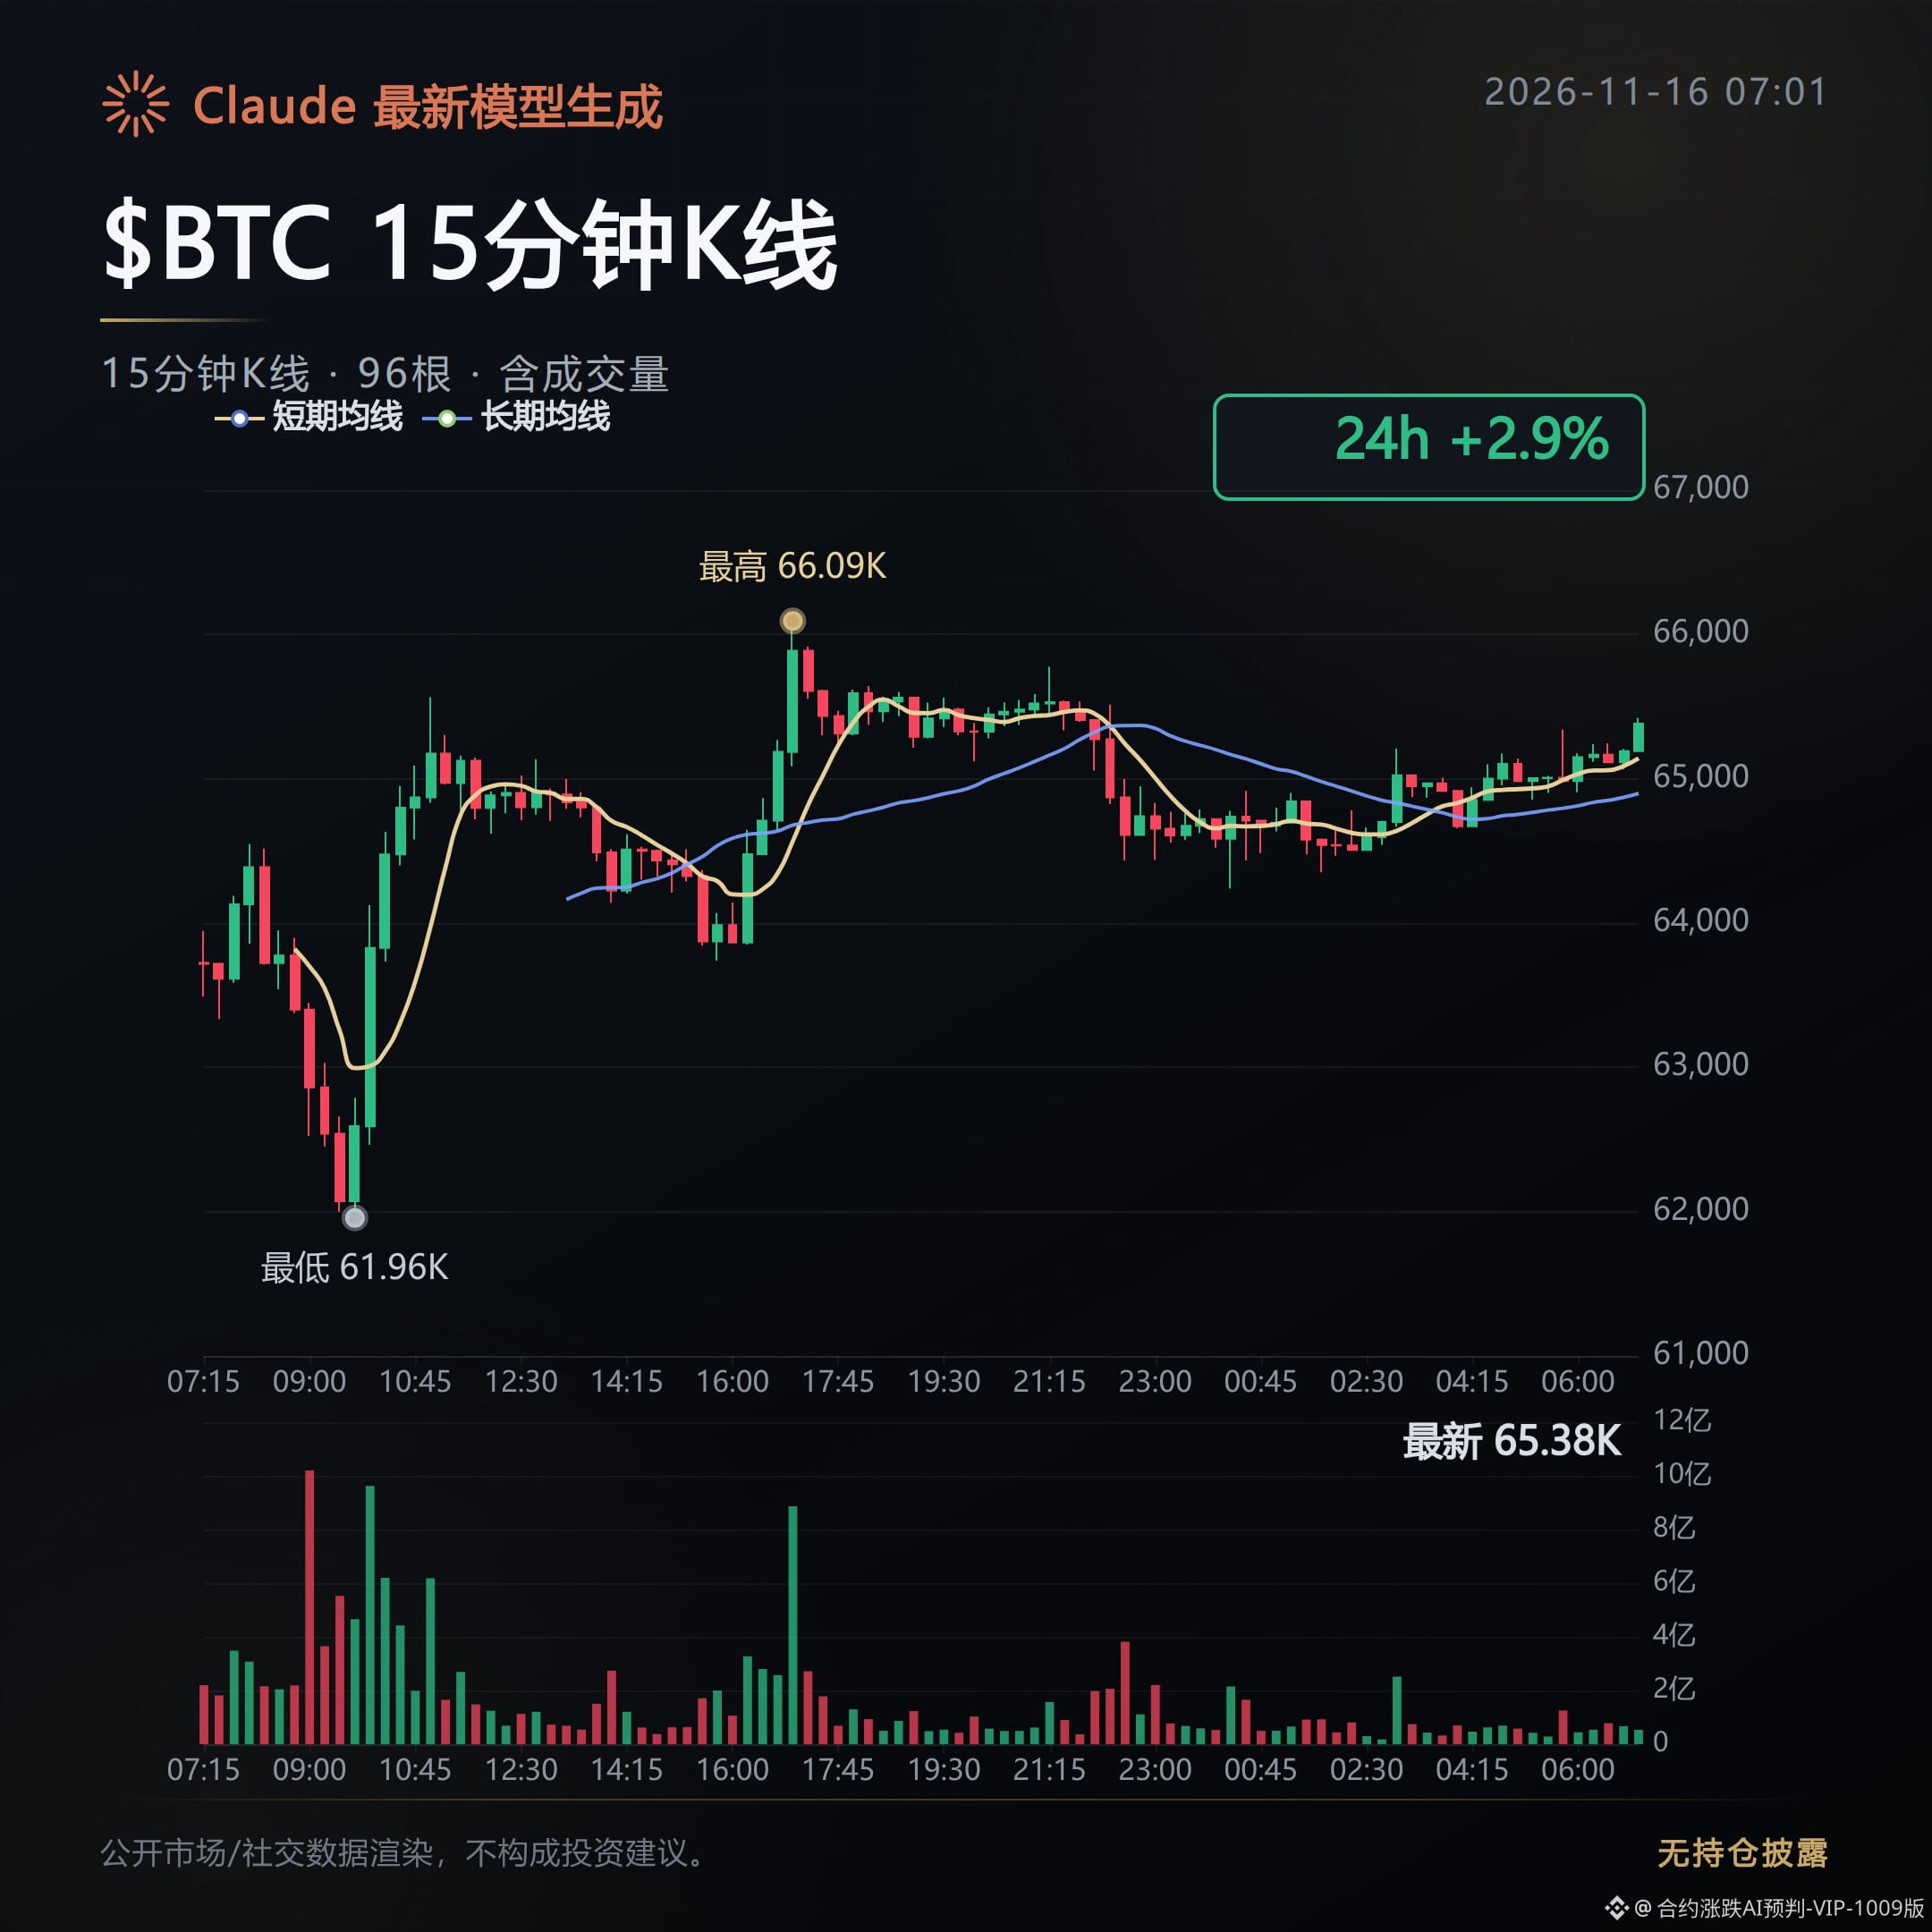
At 07:00, the $BTC mark price returned to $65,324, up 2.85%, but open interest fell to $6.11 billion, contracting 2.4%.
This looks more like leverage being rebuilt after roughly $2 billion in liquidations across the market, rather than a rally driven by new positions.
The taker buy/sell ratio was only 0.9, with aggressive sell orders still in the lead. The rebound will show signs of improving in quality only if the ratio moves back above 1 and open interest stops falling.
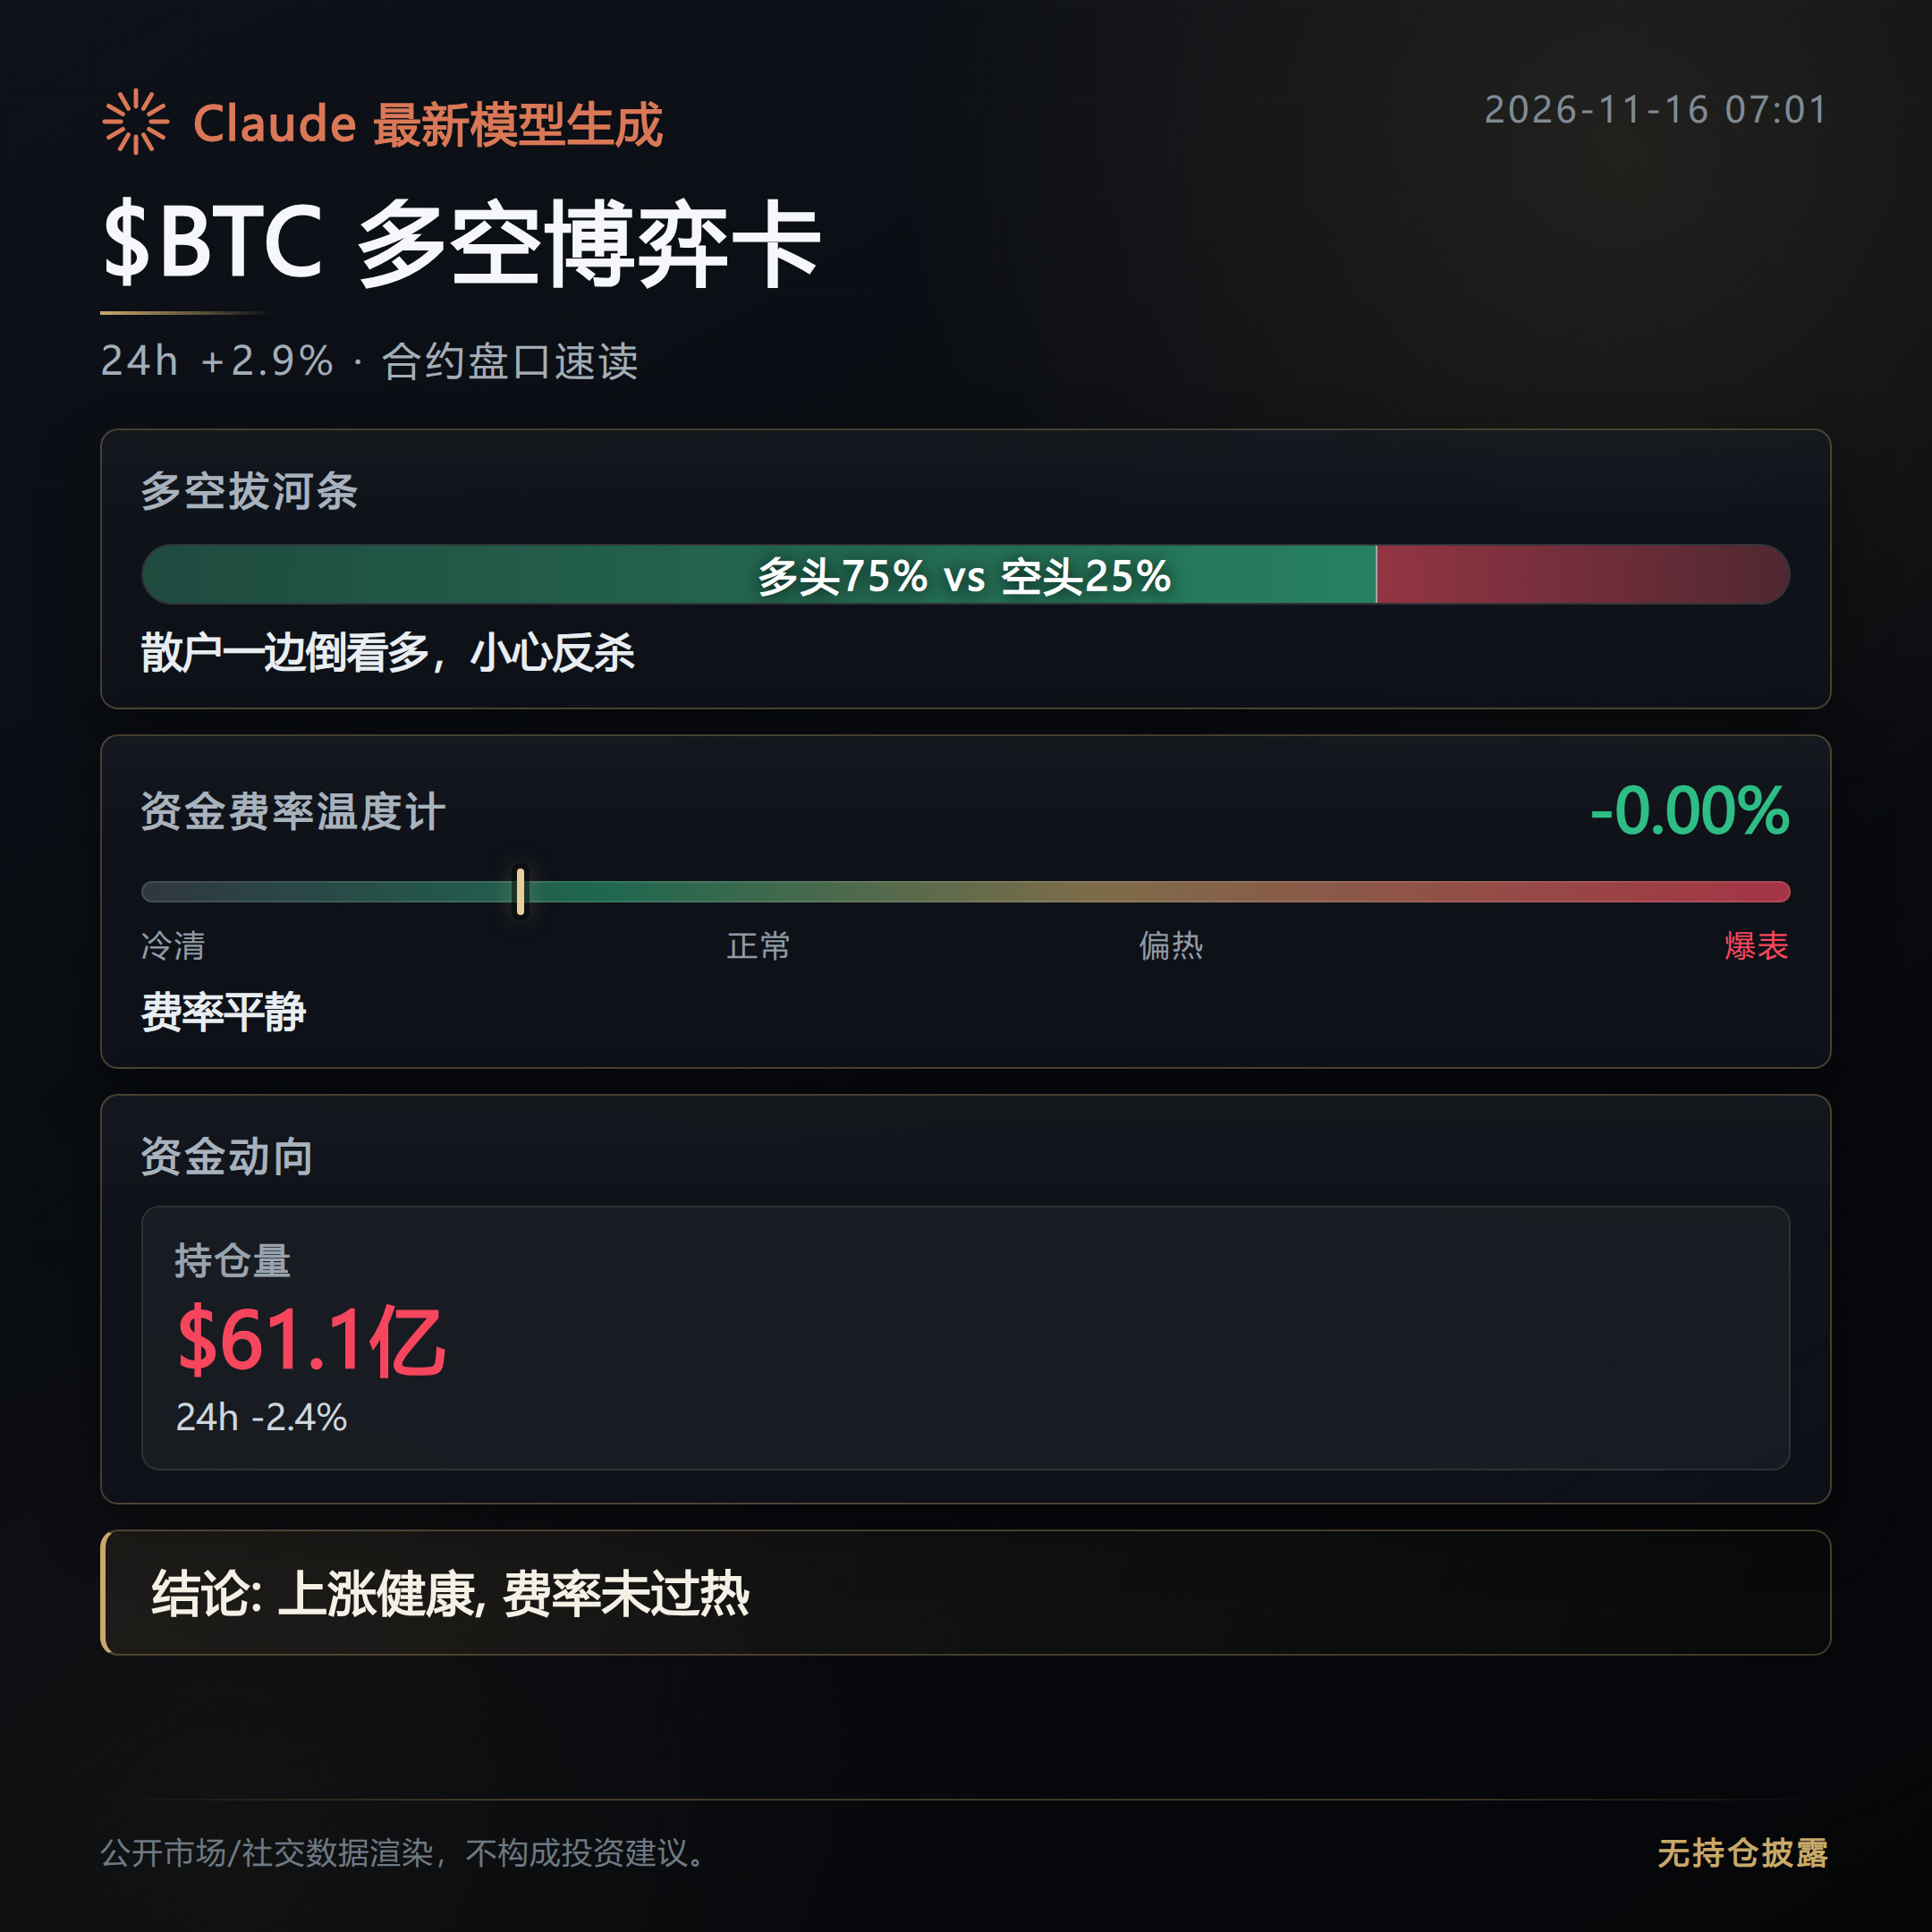
Another anomaly: 75% of accounts were long, yet the $BTC funding rate was -0.11%.
The simultaneous crowding of longs and payment by shorts points to a split positioning structure. If prices move sharply, either side could be squeezed.
The Fear & Greed Index was just 10, also indicating that the current recovery is still unfolding against a backdrop of extreme fear, not a broad return of risk appetite.
In the morning, capital favored a recovery in large-cap coins following liquidations, but spot demand has yet to confirm it.
U.S. spot Bitcoin funds have seen net outflows for seven consecutive days, totaling about $2.1 billion in November. This is the most direct funding gap above the rebound.
Meanwhile, the RARE funding rate fell as low as -0.68%, making short positions extremely costly. The risk of a short squeeze will decline only if the rate recovers while the price fails to rise.
In the opposite direction, the BULLA funding rate reached +0.289%. If the rate stays elevated while the price weakens, the risk of a long squeeze will continue to grow.
Generated with assistance from Claude Fable 5; for market information only and not investment advice.
At 07:00, the $BTC mark price returned to $65,324, up 2.85%, but open interest fell to $6.11 billion, contracting 2.4%.
This looks more like leverage being rebuilt after roughly $2 billion in liquidations across the market, rather than a rally driven by new positions.
The taker buy/sell ratio was only 0.9, with aggressive sell orders still in the lead. The rebound will show signs of improving in quality only if the ratio moves back above 1 and open interest stops falling.
Another anomaly: 75% of accounts were long, yet the $BTC funding rate was -0.11%.
The simultaneous crowding of longs and payment by shorts points to a split positioning structure. If prices move sharply, either side could be squeezed.
The Fear & Greed Index was just 10, also indicating that the current recovery is still unfolding against a backdrop of extreme fear, not a broad return of risk appetite.
In the morning, capital favored a recovery in large-cap coins following liquidations, but spot demand has yet to confirm it.
U.S. spot Bitcoin funds have seen net outflows for seven consecutive days, totaling about $2.1 billion in November. This is the most direct funding gap above the rebound.
Meanwhile, the RARE funding rate fell as low as -0.68%, making short positions extremely costly. The risk of a short squeeze will decline only if the rate recovers while the price fails to rise.
In the opposite direction, the BULLA funding rate reached +0.289%. If the rate stays elevated while the price weakens, the risk of a long squeeze will continue to grow.
Generated with assistance from Claude Fable 5; for market information only and not investment advice.