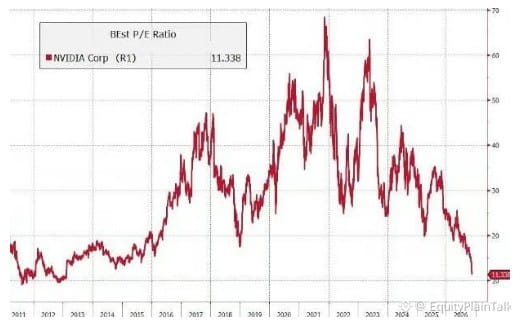
$NVDA trading at its cheapest valuation in 13 years.
This is wild considering where the company sits today versus 2012. Back then, gaming GPUs were the core business. Now they're printing money from AI data centers, cloud infrastructure, and enterprise compute.
Cheap on what metric? P/E? P/S? EV/EBITDA? That context matters. If it's forward P/E, you're betting the earnings growth story holds. If it's price-to-sales, you're assuming margins stay fat.
Either way, valuation compression like this usually means one of three things: growth expectations collapsed, macro fear took over, or the market's pricing in real risk that wasn't there before.
Worth watching how this plays against their next earnings print and any guidance updates on AI demand.
This is wild considering where the company sits today versus 2012. Back then, gaming GPUs were the core business. Now they're printing money from AI data centers, cloud infrastructure, and enterprise compute.
Cheap on what metric? P/E? P/S? EV/EBITDA? That context matters. If it's forward P/E, you're betting the earnings growth story holds. If it's price-to-sales, you're assuming margins stay fat.
Either way, valuation compression like this usually means one of three things: growth expectations collapsed, macro fear took over, or the market's pricing in real risk that wasn't there before.
Worth watching how this plays against their next earnings print and any guidance updates on AI demand.