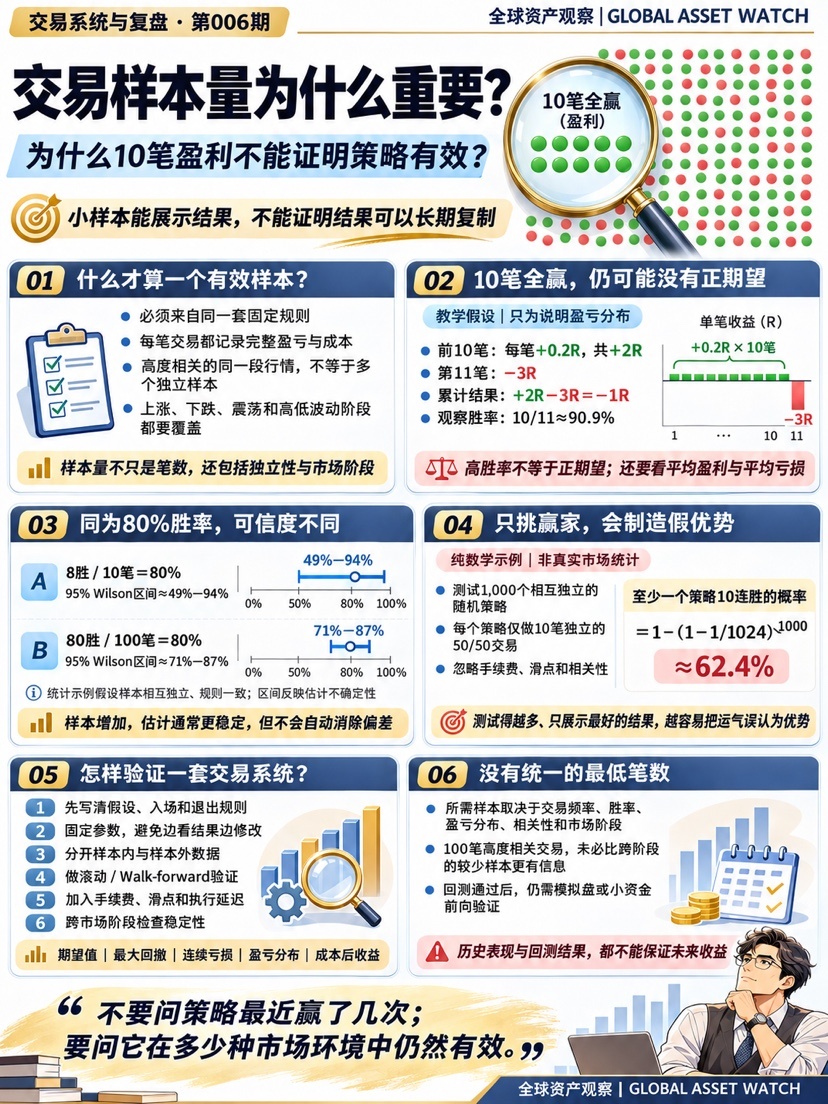
Why does trading sample size matter? Why can’t 10 profitable trades prove that a strategy works?
📊 Are 10 consecutive profitable trades enough to prove that a strategy works?
If the rules are fixed in advance and the trades are relatively independent, 10 consecutive wins are certainly positive evidence; but they still cannot, on their own, prove that the strategy has a sustainable positive expected value.
That’s because a strategy’s effectiveness depends not only on its win rate, but also on average profit, average loss, trading costs, sample independence, and market conditions.
Illustrative example:
First 10 trades: profit of 0.2R per trade, totaling +2R
11th trade: loss of 3R
Final result: +2R − 3R = −1R
The observed win rate is still 10 ÷ 11 ≈ 90.9%
Therefore, a high win rate does not mean positive expectancy, and a small sample may simply not have encountered the market conditions the strategy truly fears.
The same 80% win rate is observed:
8 wins / 10 trades: 95% Wilson interval is approximately 49%–94%
80 wins / 100 trades: 95% Wilson interval is approximately 71%–87%
Assuming the sample is independent and the rules are consistent, among other things, a larger sample usually narrows the range of estimation uncertainty. But increasing the number of trades does not automatically eliminate problems such as selection bias, changing rules, or high correlation.
Another purely mathematical example: if you independently test 1,000 random strategies, each making only 10 independent 50/50 trades, and show only the best-performing strategy, the theoretical probability of seeing at least one strategy with 10 consecutive wins is approximately:
1 − (1 − 1/1024)¹⁰⁰⁰ ≈ 62.4%
This is not a market statistic; it illustrates that the more tests you run and the more you cherry-pick the best results, the easier it is to mistake random luck for a strategic edge. The CFA Institute also warns that multiple testing, sample selection, and overfitting can make historical results appear far more reliable than the true edge warrants.
A more reliable validation process should include:
Fix the hypothesis and entry and exit rules in advance
Separate in-sample and out-of-sample data
Conduct rolling or walk-forward validation
Include fees, slippage, and execution delays
Cover rising, falling, and sideways markets, as well as different volatility regimes
Track expectancy, maximum drawdown, consecutive losses, and the distribution of wins and losses
There is no universal minimum number of trades that applies to every strategy. High- and low-frequency strategies, different win/loss distributions, and different levels of correlation require very different sample sizes. Even after passing a backtest, a strategy should still be validated prospectively through paper trading or with a small amount of capital.
Don’t just ask how many times the strategy has won recently; ask how many different market conditions it has remained effective in.
Coming next | Monday · Macroeconomics and Finance Lesson · Episode 007
(What are real interest rates? Why do they affect gold, the U.S. dollar, and growth stock valuations at the same time?)