A major report just released by the Federal Reserve has labeled Wall Street’s AI computing-power frenzy as the biggest financial risk in the United States.
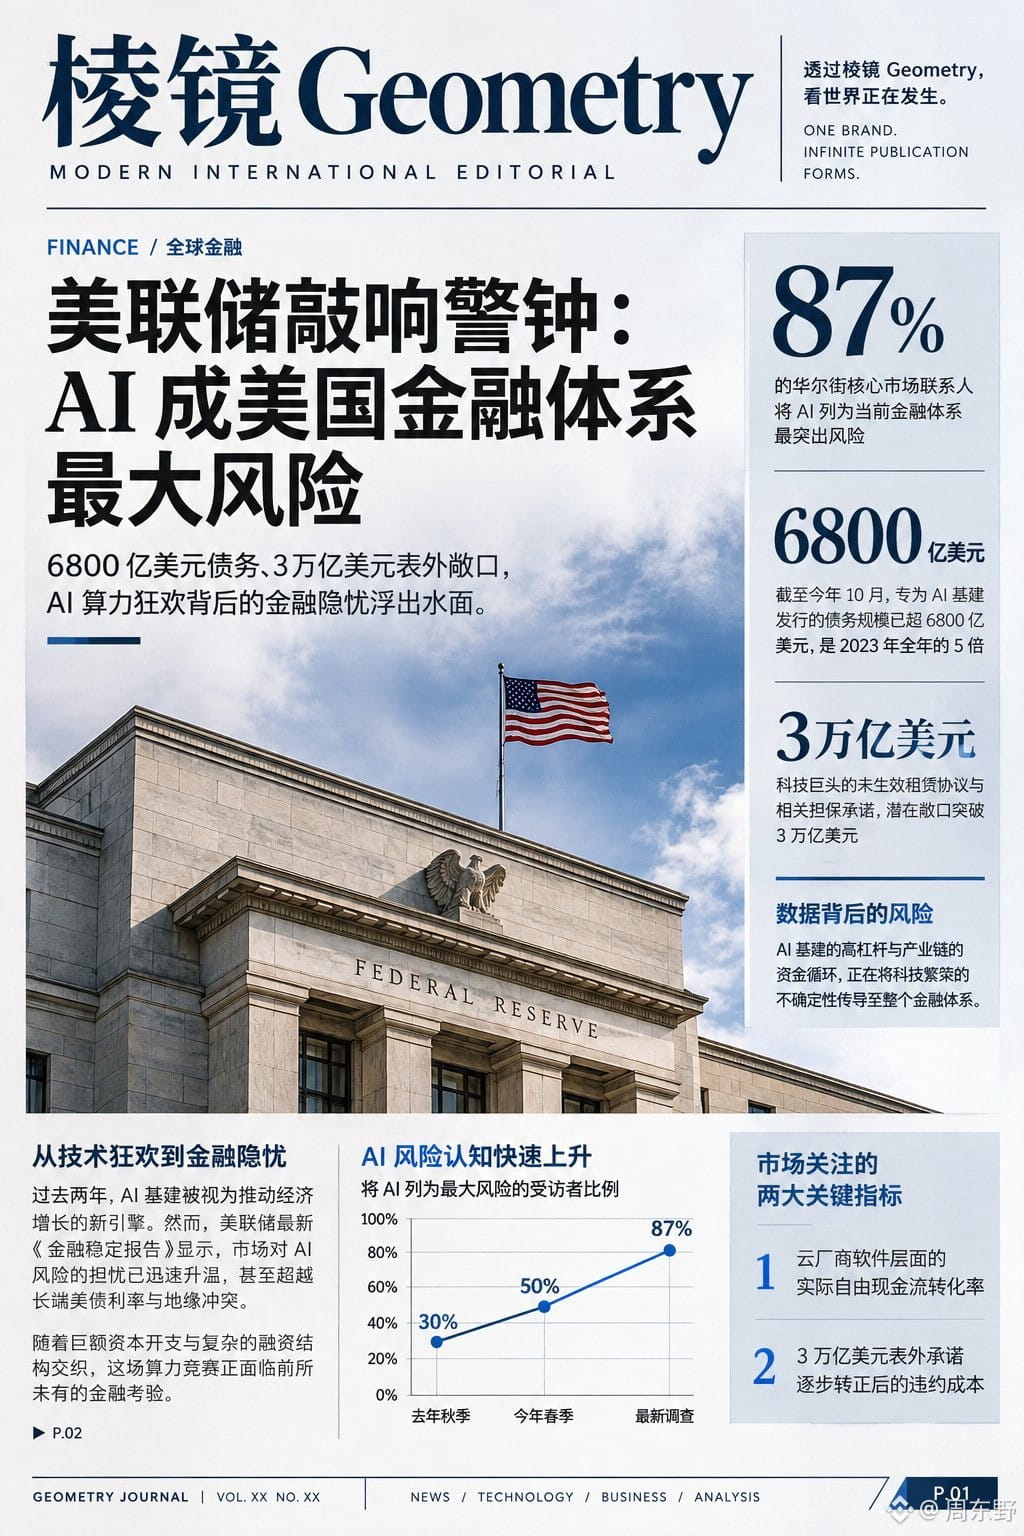
In the Fed’s latest Financial Stability Report, as many as 87% of surveyed market participants named AI as the financial system’s top threat, a sharp jump from 50% in the spring.
The report exposes the high-leverage reality behind tech giants’ seemingly abundant cash flows: as of October, AI infrastructure-related debt issuance had topped $680 billion—five times the full-year 2023 total—and accounted for nearly one-third of nonfinancial investment-grade corporate bonds.
Even more obscure are more than $3 trillion in off-balance-sheet commitments for leases and guarantees that have yet to take effect. If downstream demand for computing power falls short of expectations, these hidden exposures could turn into a genuine debt black hole.
Even more concerning is the circular financing within the industry. Chip giants sell chips to downstream startups and cloud providers while also investing directly in those buyers—and even guaranteeing the value of the chips they purchase.
This closed loop of passing money from one hand to the other makes it extremely difficult for outsiders to tell whether revenue comes from genuine commercial demand or capital simply circulating among key players. Meanwhile, U.S. banks’ exposure to tech giants and data-center financing vehicles is approaching $1 trillion, hedge-fund leverage has reached its highest level since 2013, and hyperscalers’ capital spending as a share of GDP is nearing levels last seen during the telecom bubble of the late 1990s.
The fiber-optic networks built back then ultimately benefited the internet age, but before the business model proved viable, excessive borrowing and leverage triggered a severe valuation correction.
To judge whether the AI narrative can hold up from here, it won’t be enough to look at model benchmarks or chip shipments. We’ll also need to closely monitor the actual conversion of cloud providers’ software revenue into free cash flow, as well as the risk of default once those $3 trillion in off-balance-sheet commitments take effect. When the market is no longer willing to pay just for long-term promises, the most fragile links in the funding chain are often the first to feel the chill.
#FederalReserve
In the Fed’s latest Financial Stability Report, as many as 87% of surveyed market participants named AI as the financial system’s top threat, a sharp jump from 50% in the spring.
The report exposes the high-leverage reality behind tech giants’ seemingly abundant cash flows: as of October, AI infrastructure-related debt issuance had topped $680 billion—five times the full-year 2023 total—and accounted for nearly one-third of nonfinancial investment-grade corporate bonds.
Even more obscure are more than $3 trillion in off-balance-sheet commitments for leases and guarantees that have yet to take effect. If downstream demand for computing power falls short of expectations, these hidden exposures could turn into a genuine debt black hole.
Even more concerning is the circular financing within the industry. Chip giants sell chips to downstream startups and cloud providers while also investing directly in those buyers—and even guaranteeing the value of the chips they purchase.
This closed loop of passing money from one hand to the other makes it extremely difficult for outsiders to tell whether revenue comes from genuine commercial demand or capital simply circulating among key players. Meanwhile, U.S. banks’ exposure to tech giants and data-center financing vehicles is approaching $1 trillion, hedge-fund leverage has reached its highest level since 2013, and hyperscalers’ capital spending as a share of GDP is nearing levels last seen during the telecom bubble of the late 1990s.
The fiber-optic networks built back then ultimately benefited the internet age, but before the business model proved viable, excessive borrowing and leverage triggered a severe valuation correction.
To judge whether the AI narrative can hold up from here, it won’t be enough to look at model benchmarks or chip shipments. We’ll also need to closely monitor the actual conversion of cloud providers’ software revenue into free cash flow, as well as the risk of default once those $3 trillion in off-balance-sheet commitments take effect. When the market is no longer willing to pay just for long-term promises, the most fragile links in the funding chain are often the first to feel the chill.
#FederalReserve