2026.11.13 · Global Macro Market Briefing
Today’s Global Macro Theme: Key Takeaways
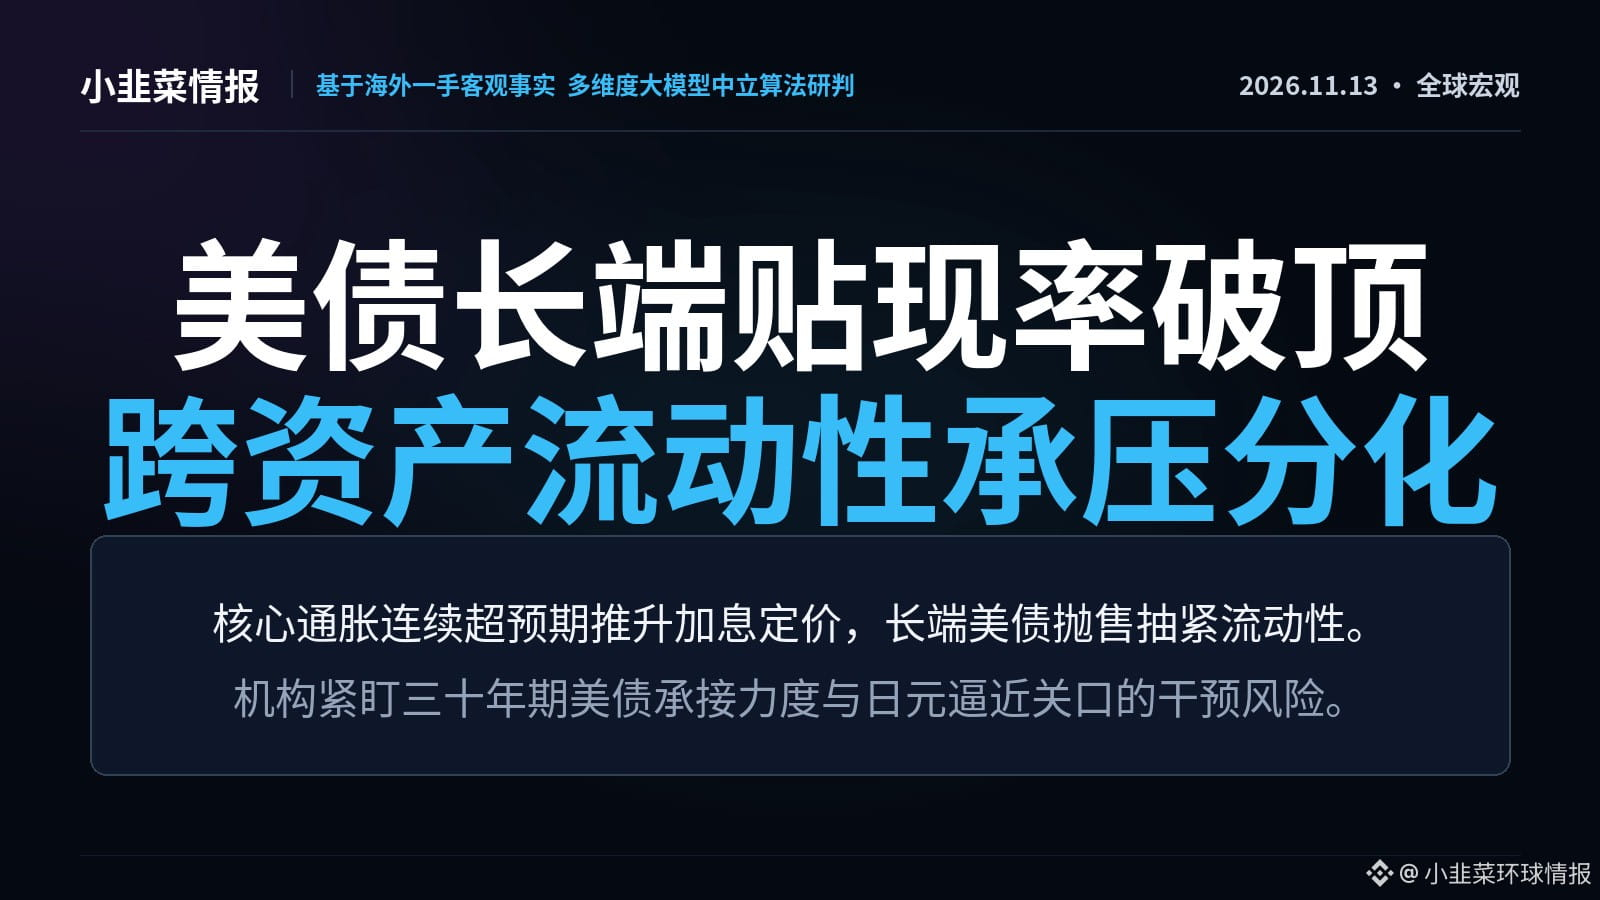
U.S. core inflation has exceeded expectations for consecutive months, prompting markets to raise their expectations for the terminal rate. Markets are now pricing in 87 basis points of rate hikes over the coming year. Long-term Treasury yields have broken above 5.10%, while weak demand at a long-bond auction has driven the dollar to a one-and-a-half-year high, putting discount-rate pressure on gold and equities.
Today’s Main Battleground: A Deeper Look
An inflation rebound and weak Treasury auction sparked a discount-rate storm: U.S. core CPI rose 0.3% month over month in October, exceeding expectations for the third consecutive month and pushing rate-hike pricing to 87 basis points. The Treasury’s $25 billion 30-year bond auction drew a high yield of 5.441%, with a wider tail. The 10-year yield rose above 5.11%, while spot gold plunged $112 in a single day, breaking below $3,875. [A Deeper Look] At its core, this reflects the dual pressure of an expanding fiscal deficit and a reassessment of monetary tightening. With the federal deficit reaching $404 billion in October, buyers are demanding a higher term premium. The resulting surge in pressure on primary dealers has tightened liquidity. A risk-free rate breaking new highs directly weighs on non-yielding assets, accelerating cross-asset flows back into high-yielding U.S. dollars.
Panoramic Quantitative Anomaly Radar
• FX defense line: The U.S. Dollar Index has climbed to a one-and-a-half-year high, while USD/JPY is nearing the 160.00 level. A widening U.S.-Japan interest-rate differential is adding to pressure on the yen, and markets are closely watching for potential official intervention at this level.
• Energy standoff: U.S. crude inventories surged by 4.657 million barrels in the latest week, far exceeding expectations for a 1.109-million-barrel draw. The tug-of-war between inventory builds and shifting geopolitical risk premiums has kept Brent and WTI fluctuating widely around key moving-average ranges.
Market Positioning and Monitoring Map
Core transmission chain: Persistent inflation and a wave of Treasury supply -> long-term real Treasury yields break new highs -> global dollar liquidity tightens, weighing on risk assets and gold valuations. Key indicators to watch over the next 24 to 48 hours: ① whether the 10-year Treasury yield consolidates around 5.10%; ② positioning in USD/JPY around 160.00 and any signals of official intervention.
Disclaimer: This publication is solely a compilation and logical analysis of publicly available global news and objective market data from the past 24 hours. It does not constitute investment advice, an offer to buy or sell, or a basis for taking action. Markets involve risk; please make decisions with caution.
Today’s Global Macro Theme: Key Takeaways
U.S. core inflation has exceeded expectations for consecutive months, prompting markets to raise their expectations for the terminal rate. Markets are now pricing in 87 basis points of rate hikes over the coming year. Long-term Treasury yields have broken above 5.10%, while weak demand at a long-bond auction has driven the dollar to a one-and-a-half-year high, putting discount-rate pressure on gold and equities.
Today’s Main Battleground: A Deeper Look
An inflation rebound and weak Treasury auction sparked a discount-rate storm: U.S. core CPI rose 0.3% month over month in October, exceeding expectations for the third consecutive month and pushing rate-hike pricing to 87 basis points. The Treasury’s $25 billion 30-year bond auction drew a high yield of 5.441%, with a wider tail. The 10-year yield rose above 5.11%, while spot gold plunged $112 in a single day, breaking below $3,875. [A Deeper Look] At its core, this reflects the dual pressure of an expanding fiscal deficit and a reassessment of monetary tightening. With the federal deficit reaching $404 billion in October, buyers are demanding a higher term premium. The resulting surge in pressure on primary dealers has tightened liquidity. A risk-free rate breaking new highs directly weighs on non-yielding assets, accelerating cross-asset flows back into high-yielding U.S. dollars.
Panoramic Quantitative Anomaly Radar
• FX defense line: The U.S. Dollar Index has climbed to a one-and-a-half-year high, while USD/JPY is nearing the 160.00 level. A widening U.S.-Japan interest-rate differential is adding to pressure on the yen, and markets are closely watching for potential official intervention at this level.
• Energy standoff: U.S. crude inventories surged by 4.657 million barrels in the latest week, far exceeding expectations for a 1.109-million-barrel draw. The tug-of-war between inventory builds and shifting geopolitical risk premiums has kept Brent and WTI fluctuating widely around key moving-average ranges.
Market Positioning and Monitoring Map
Core transmission chain: Persistent inflation and a wave of Treasury supply -> long-term real Treasury yields break new highs -> global dollar liquidity tightens, weighing on risk assets and gold valuations. Key indicators to watch over the next 24 to 48 hours: ① whether the 10-year Treasury yield consolidates around 5.10%; ② positioning in USD/JPY around 160.00 and any signals of official intervention.
Disclaimer: This publication is solely a compilation and logical analysis of publicly available global news and objective market data from the past 24 hours. It does not constitute investment advice, an offer to buy or sell, or a basis for taking action. Markets involve risk; please make decisions with caution.