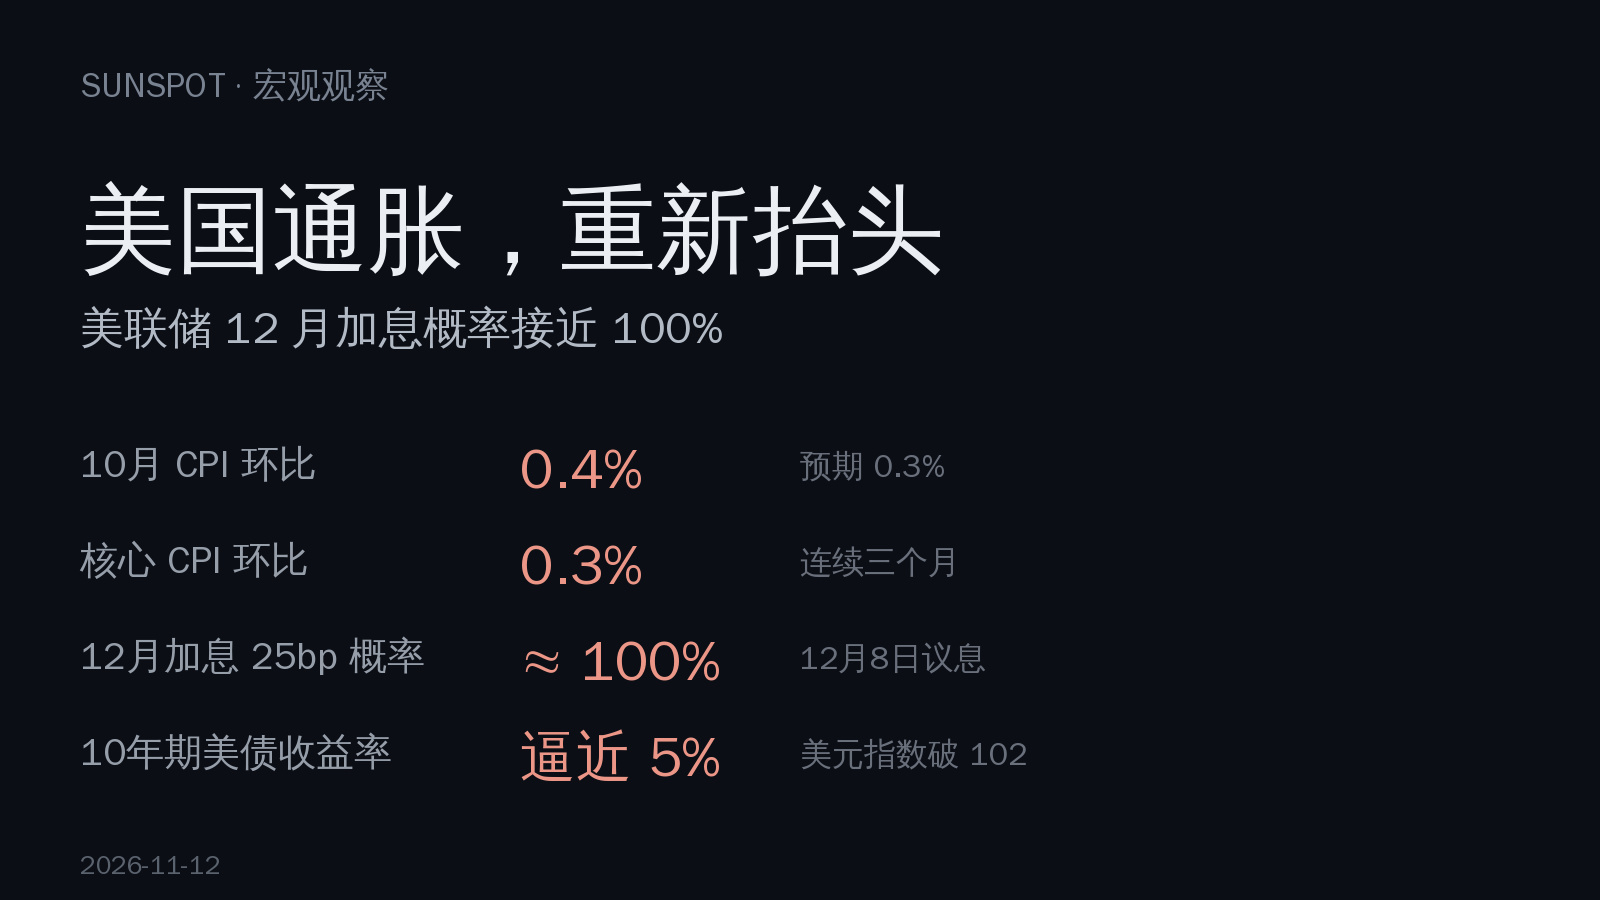
U.S. CPI rose 0.4% month over month in October, 0.1 percentage point above expectations. Core CPI rose 0.3% month over month, refusing to cool for a third consecutive month. There’s no year-over-year figure this time: the government shutdown last October distorted the base, so we can only judge by the monthly numbers. Annualized, inflation has been running above 3% over the past three months.
Housing drove prices higher, rising 0.3% month over month and accounting for more than 30% of the overall increase. Rent is sticky: once it rises, it’s hard to bring back down. Food and energy prices are also climbing.
The Fed raised rates by 25 basis points in September, the first hike since 2023. It held steady at the end of October, leaving the target range at 3.75% to 4%. The vote was 10 to 2, with two officials favoring an outright rate hike. Policymakers have made their position clear: inflation takes priority over growth.
Markets have priced in a 25-basis-point rate hike at the December 8 meeting at close to 100%. Deutsche Bank is taking an even more aggressive view, betting on three consecutive hikes in December, January, and March, pushing the range to 4.5%–4.75%.
The bond market moved first. The 2-year Treasury yield climbed to around 4.68%, the 10-year approached 5%, the dollar index broke above 102, and the S&P 500 fell at the open.
For crypto traders, this signals tightening liquidity. Valuations that rose on rate-cut expectations over the past two years now have to give back those gains. A stronger dollar and higher real interest rates make risk-free returns more attractive, weighing on risk appetite for Bitcoin and altcoins.
Don’t bet against a Fed that’s worried about inflation. Until there’s a clear turning point in sticky components like rent, the window for rate hikes will remain open.
——————————————
Thanks for following, and feel free to share your observations and ideas in the comments. I’ll continue sharing chart notes and market observations for your reference.
Housing drove prices higher, rising 0.3% month over month and accounting for more than 30% of the overall increase. Rent is sticky: once it rises, it’s hard to bring back down. Food and energy prices are also climbing.
The Fed raised rates by 25 basis points in September, the first hike since 2023. It held steady at the end of October, leaving the target range at 3.75% to 4%. The vote was 10 to 2, with two officials favoring an outright rate hike. Policymakers have made their position clear: inflation takes priority over growth.
Markets have priced in a 25-basis-point rate hike at the December 8 meeting at close to 100%. Deutsche Bank is taking an even more aggressive view, betting on three consecutive hikes in December, January, and March, pushing the range to 4.5%–4.75%.
The bond market moved first. The 2-year Treasury yield climbed to around 4.68%, the 10-year approached 5%, the dollar index broke above 102, and the S&P 500 fell at the open.
For crypto traders, this signals tightening liquidity. Valuations that rose on rate-cut expectations over the past two years now have to give back those gains. A stronger dollar and higher real interest rates make risk-free returns more attractive, weighing on risk appetite for Bitcoin and altcoins.
Don’t bet against a Fed that’s worried about inflation. Until there’s a clear turning point in sticky components like rent, the window for rate hikes will remain open.
——————————————
Thanks for following, and feel free to share your observations and ideas in the comments. I’ll continue sharing chart notes and market observations for your reference.