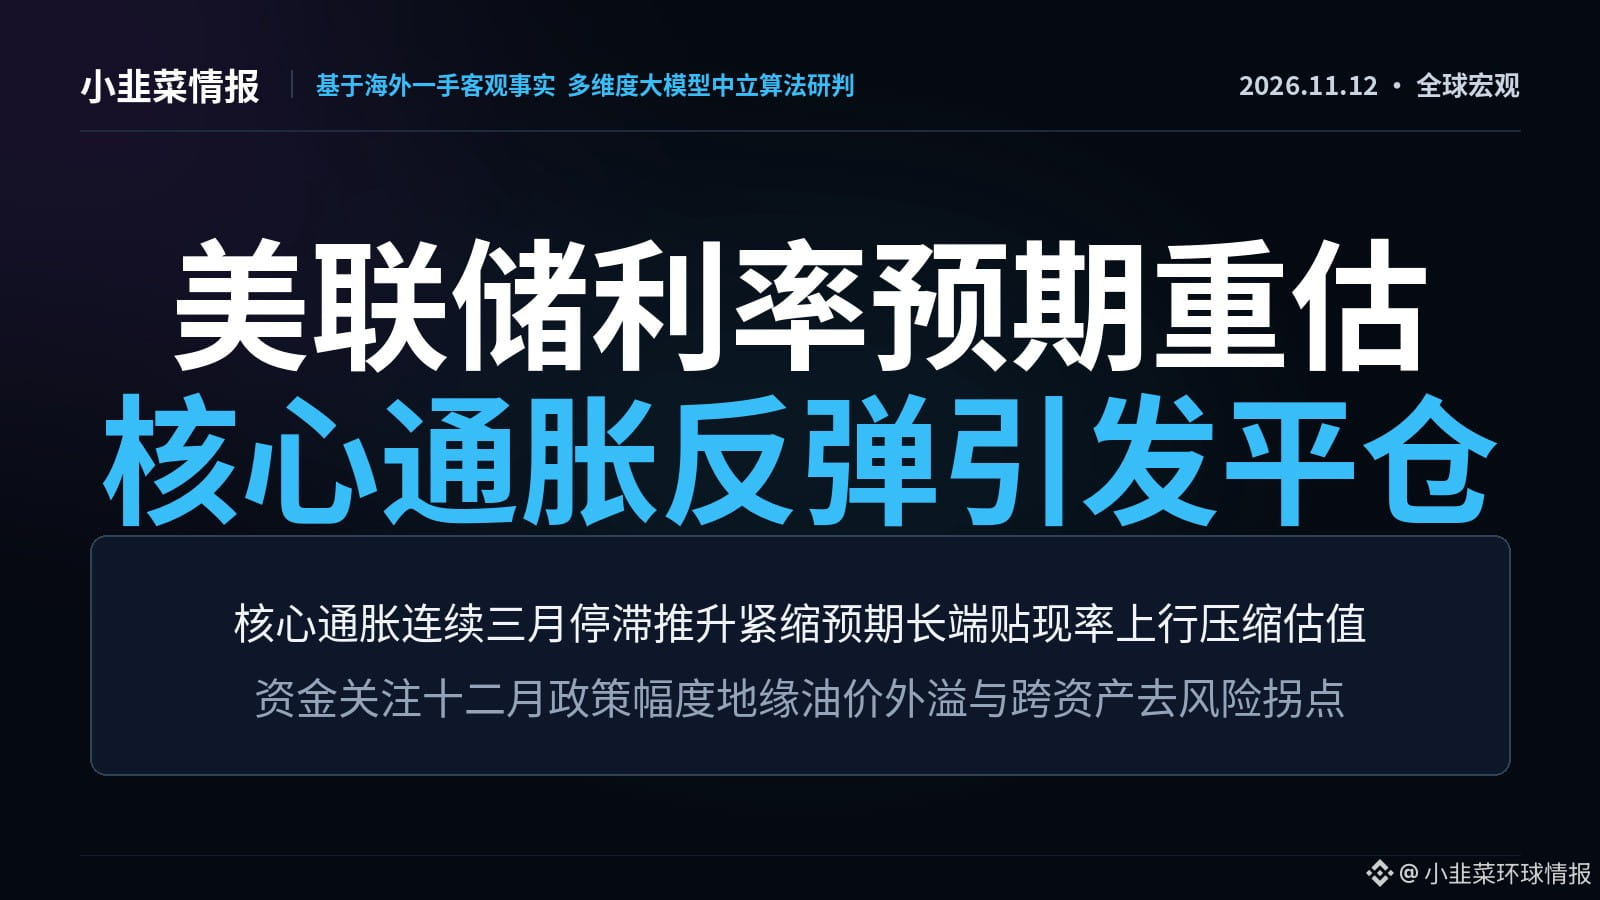
2026.11.12 · Global Macro Market Intelligence Briefing
Today’s Global Macro Theme: Core Outlook
U.S. core inflation stalled at elevated levels for the third consecutive month in October, completely reversing expectations for monetary easing and significantly extending expectations for the scale and duration of further Fed tightening. Combined with the heightened risk of a second wave of energy-driven inflation amid geopolitical maneuvering in the Middle East, this has triggered a dramatic repricing of discount rates across global assets, prompting hedge funds to carry out a risk-off liquidation rarely seen in the past decade.
Today’s Main Battleground: In-Depth Analysis
Stalled core inflation is reshaping the interest rate outlook, triggering the largest global risk-off liquidation in a decade: U.S. core CPI rose 0.3% month over month in October for the third consecutive month. Institutional forecasts have pushed the timing of rate cuts back to the end of 2027, while derivatives markets have fully priced in a December rate hike, fueling aggressive discussions of a 50-basis-point increase. Hedge funds launched their most severe wave of long-position liquidations in more than a decade during the first week of November. 【In-Depth Analysis】The pass-through of high oil prices into core services has completely undermined expectations for falling inflation, while weaker Fed forward guidance has widened the dispersion in terminal-rate pricing. The long-end discount-rate benchmark is shifting systematically higher, severely eroding returns on highly valued assets with heavy capital expenditure needs, such as AI infrastructure. A strong dollar is also siphoning liquidity across markets, forcing leveraged capital to contract defensively.
Panoramic Quantitative Anomaly Radar
• Geopolitical energy supply: Brent crude climbed to $93.90 as Middle East peace talks stalled and shipping through the strait was disrupted. Refined-product exports have recovered to just 35%, and rebounding energy costs are intensifying the pressure from imported second-wave inflation worldwide.
• Sovereign reserve realignment: Global central banks purchased more than 321 tonnes of gold in the third quarter, the fifth-largest quarterly increase on record. Amid persistently high long-term interest rates and the normalization of geopolitical tensions, sovereign funds are continuing to replace traditional fiat reserves to hedge against credit risk.
Market Dynamics and Monitoring Map
Transmission chain: Geopolitical deadlock pushes up the crude oil premium -> raises inflation expectations and reinforces the rate-hike path -> drives discount rates higher and triggers cross-asset risk reduction. Key indicators to monitor over the next 24 to 48 hours: the USD/JPY intervention threshold of 159.00, WTI crude’s consolidation level at $88.00, and the delayed change in EIA crude inventories.
Disclaimer: This publication is solely an aggregation and logical analysis of publicly available global news and objective market data from the past 24 hours. It does not constitute investment advice, an offer to buy or sell, or a basis for any trading decision. Markets involve risk; please exercise caution when making decisions.
Today’s Global Macro Theme: Core Outlook
U.S. core inflation stalled at elevated levels for the third consecutive month in October, completely reversing expectations for monetary easing and significantly extending expectations for the scale and duration of further Fed tightening. Combined with the heightened risk of a second wave of energy-driven inflation amid geopolitical maneuvering in the Middle East, this has triggered a dramatic repricing of discount rates across global assets, prompting hedge funds to carry out a risk-off liquidation rarely seen in the past decade.
Today’s Main Battleground: In-Depth Analysis
Stalled core inflation is reshaping the interest rate outlook, triggering the largest global risk-off liquidation in a decade: U.S. core CPI rose 0.3% month over month in October for the third consecutive month. Institutional forecasts have pushed the timing of rate cuts back to the end of 2027, while derivatives markets have fully priced in a December rate hike, fueling aggressive discussions of a 50-basis-point increase. Hedge funds launched their most severe wave of long-position liquidations in more than a decade during the first week of November. 【In-Depth Analysis】The pass-through of high oil prices into core services has completely undermined expectations for falling inflation, while weaker Fed forward guidance has widened the dispersion in terminal-rate pricing. The long-end discount-rate benchmark is shifting systematically higher, severely eroding returns on highly valued assets with heavy capital expenditure needs, such as AI infrastructure. A strong dollar is also siphoning liquidity across markets, forcing leveraged capital to contract defensively.
Panoramic Quantitative Anomaly Radar
• Geopolitical energy supply: Brent crude climbed to $93.90 as Middle East peace talks stalled and shipping through the strait was disrupted. Refined-product exports have recovered to just 35%, and rebounding energy costs are intensifying the pressure from imported second-wave inflation worldwide.
• Sovereign reserve realignment: Global central banks purchased more than 321 tonnes of gold in the third quarter, the fifth-largest quarterly increase on record. Amid persistently high long-term interest rates and the normalization of geopolitical tensions, sovereign funds are continuing to replace traditional fiat reserves to hedge against credit risk.
Market Dynamics and Monitoring Map
Transmission chain: Geopolitical deadlock pushes up the crude oil premium -> raises inflation expectations and reinforces the rate-hike path -> drives discount rates higher and triggers cross-asset risk reduction. Key indicators to monitor over the next 24 to 48 hours: the USD/JPY intervention threshold of 159.00, WTI crude’s consolidation level at $88.00, and the delayed change in EIA crude inventories.
Disclaimer: This publication is solely an aggregation and logical analysis of publicly available global news and objective market data from the past 24 hours. It does not constitute investment advice, an offer to buy or sell, or a basis for any trading decision. Markets involve risk; please exercise caution when making decisions.