
Nvidia has already fallen about 23% from its all-time high of $243.37, and earnings are still yet to come.
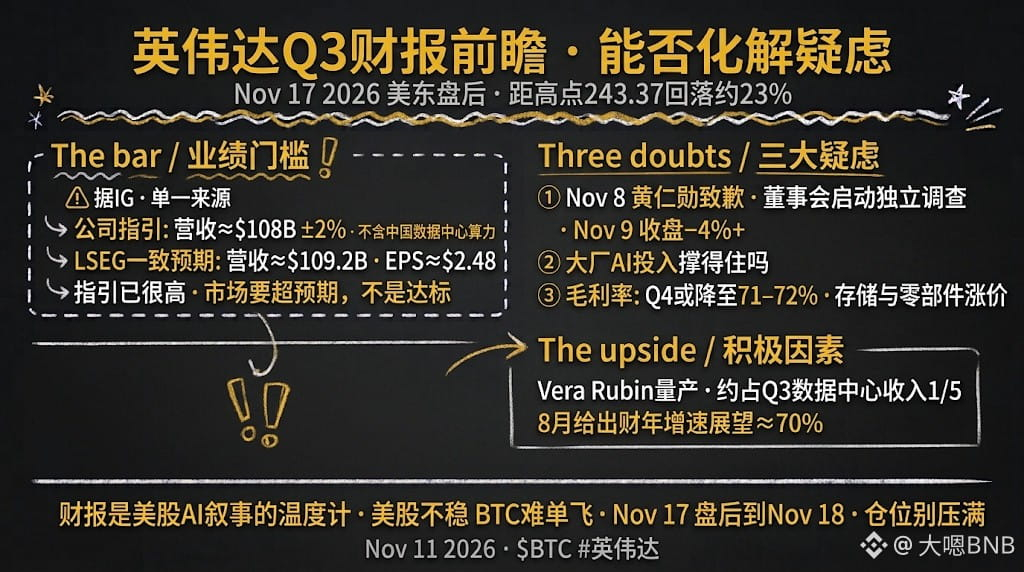
According to IG (November 10), Nvidia is scheduled to report its third-quarter earnings after market close on November 17, Eastern Time. The company’s own guidance calls for revenue of about $108 billion, plus or minus 2%, excluding data center computing revenue from China. According to LSEG, the consensus estimate is about $109.2 billion in revenue and adjusted earnings per share of about $2.48. The message is clear: guidance is already very high, and the market wants a beat, not just a meet.
What are investors worried about? I dug into it, and the concerns fall into three layers. First, Jensen Huang apologized on November 8, and the board launched an independent investigation. On November 9, the stock closed down more than 4%, after falling as much as 8.8% intraday (according to IG). Second, can the big tech companies keep up their AI spending? This is an old concern across the entire sector. Third, gross margins. According to IG, in its previous earnings report, the company warned that gross margins could fall to 71%–72% in the fourth quarter due to rising memory and component prices.
There is good news, too: according to IG, Vera Rubin is already in mass production and is expected to account for about one-fifth of third-quarter data center revenue. In August, the company also forecast fiscal-year revenue growth of about 70%. All of this comes from a single source; I couldn’t find a second source to cross-check it.
I don’t know whether the earnings report can dispel these concerns all at once. But my take is that Nvidia’s report will be a barometer for the US stock market’s AI narrative. If US stocks can’t hold steady, it’ll be hard for BTC to fly solo. From after the market close on November 17, Eastern Time, through November 18, don’t go all in.
What do you think the market will focus on this time: the revenue number, or what management says on the earnings call?
$BTC $NVDAB
#英伟达
#英伟达q3财报将至:能否化解市场疑虑?
According to IG (November 10), Nvidia is scheduled to report its third-quarter earnings after market close on November 17, Eastern Time. The company’s own guidance calls for revenue of about $108 billion, plus or minus 2%, excluding data center computing revenue from China. According to LSEG, the consensus estimate is about $109.2 billion in revenue and adjusted earnings per share of about $2.48. The message is clear: guidance is already very high, and the market wants a beat, not just a meet.
What are investors worried about? I dug into it, and the concerns fall into three layers. First, Jensen Huang apologized on November 8, and the board launched an independent investigation. On November 9, the stock closed down more than 4%, after falling as much as 8.8% intraday (according to IG). Second, can the big tech companies keep up their AI spending? This is an old concern across the entire sector. Third, gross margins. According to IG, in its previous earnings report, the company warned that gross margins could fall to 71%–72% in the fourth quarter due to rising memory and component prices.
There is good news, too: according to IG, Vera Rubin is already in mass production and is expected to account for about one-fifth of third-quarter data center revenue. In August, the company also forecast fiscal-year revenue growth of about 70%. All of this comes from a single source; I couldn’t find a second source to cross-check it.
I don’t know whether the earnings report can dispel these concerns all at once. But my take is that Nvidia’s report will be a barometer for the US stock market’s AI narrative. If US stocks can’t hold steady, it’ll be hard for BTC to fly solo. From after the market close on November 17, Eastern Time, through November 18, don’t go all in.
What do you think the market will focus on this time: the revenue number, or what management says on the earnings call?
$BTC $NVDAB
#英伟达
#英伟达q3财报将至:能否化解市场疑虑?