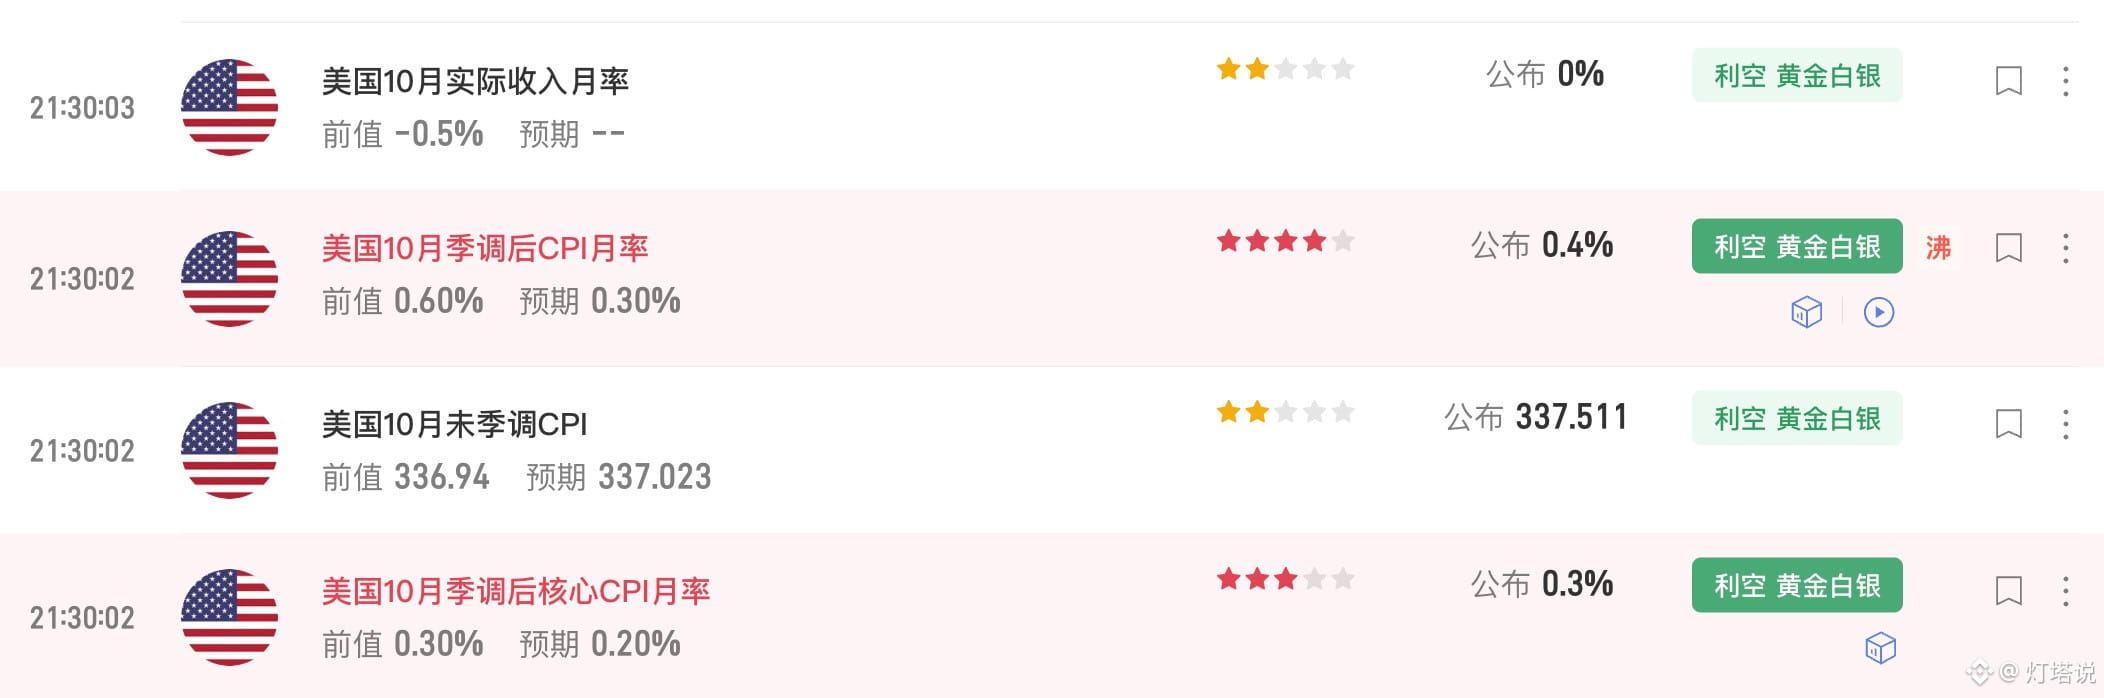
U.S. CPI rose 0.4% month over month in October on a seasonally adjusted basis, above market expectations. U.S. core CPI rose 0.3% month over month in October on a seasonally adjusted basis, also above market expectations.
U.S. Treasury yields extended their gains after the CPI data was released. The 10-year Treasury yield was last up 9.03 basis points at 4.952%. The 2-year Treasury yield was last up 16.54 basis points at 4.715%.
Core CPI rose 0.3% for the third consecutive month. This indicates that core inflation has not slowed noticeably. At a simple annualized rate, it is about 3.7%, still some distance from the 2% inflation target.
Housing costs rose 0.3%, down from 0.4% in September. This was a relatively mild bright spot, but not enough to offset pressure from other components.
Food prices rose 0.5%, and energy prices rose 0.7%. Although overall inflation eased from September, it did not cool by as much as the market had hoped.
Both CPI readings came in above expectations, a clear inflation headwind.
The data brought none of the cooling-inflation surprise the market had hoped for. Core CPI has held at 0.3% for three consecutive months, an unfavorable signal for risk assets hoping the Fed will end its tightening cycle soon.
In the short term, further downside looks more likely!
U.S. Treasury yields extended their gains after the CPI data was released. The 10-year Treasury yield was last up 9.03 basis points at 4.952%. The 2-year Treasury yield was last up 16.54 basis points at 4.715%.
Core CPI rose 0.3% for the third consecutive month. This indicates that core inflation has not slowed noticeably. At a simple annualized rate, it is about 3.7%, still some distance from the 2% inflation target.
Housing costs rose 0.3%, down from 0.4% in September. This was a relatively mild bright spot, but not enough to offset pressure from other components.
Food prices rose 0.5%, and energy prices rose 0.7%. Although overall inflation eased from September, it did not cool by as much as the market had hoped.
Both CPI readings came in above expectations, a clear inflation headwind.
The data brought none of the cooling-inflation surprise the market had hoped for. Core CPI has held at 0.3% for three consecutive months, an unfavorable signal for risk assets hoping the Fed will end its tightening cycle soon.
In the short term, further downside looks more likely!