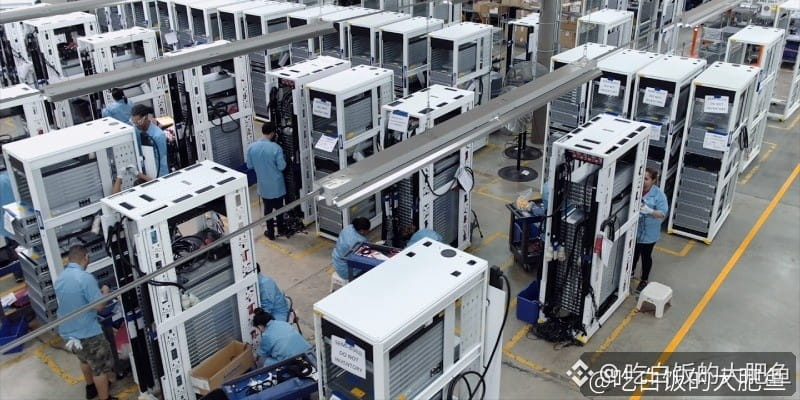
A contract manufacturer posts an 84% surge in quarterly revenue, with earnings per share jumping from $1.67 to $4.43. After the earnings report came out, its stock briefly rose more than 20% after hours. This round of AI profits isn’t going only to chip sellers—it’s also benefiting the companies that build the racks for those chips.
Sanmina ($SANM) just reported its Q4 FY2026 results (for the quarter ended October 3):
1. Revenue was $3.86 billion, up 84% year over year—10% above the market’s $3.48 billion estimate and even above the high end of the company’s own $3.3–$3.6 billion guidance.
2. Adjusted earnings per share were $4.43, up from just $1.67 in the same period last year and 35% above the market’s $3.27 estimate.
3. Revenue from cloud and AI infrastructure plus communications networks was $2.37 billion, up 179% year over year. For the full year, this segment generated $9.25 billion, or 64% of total revenue.
4. Guidance for next year is even stronger: FY2027 revenue of $17.5–$19.5 billion and adjusted earnings per share of $15.50–$17.50, with both midpoint figures well above market expectations. The stock was also up about 19.5% in premarket trading this morning.
My take: The real significance of this earnings report isn’t “how much it grew,” but “who’s footing the bill.” The cloud and AI infrastructure business generated $9.25 billion for the year, and the ZT Systems rack business—acquired from AMD last October—is the engine behind that growth. Cloud providers are putting real money into AI racks. But don’t get carried away: $0.42 of the $4.43 in earnings per share came from tariff refunds, and next year’s guidance for operating margins of 7.0–7.5% is actually below this quarter’s 9.0%. There are two possible paths: if Helios rack shipments ramp up in time and margins hold, more of this AI infrastructure spending will keep flowing to contract manufacturers; if orders slow, the valuation gains could be the first to reverse.
Sanmina ($SANM) just reported its Q4 FY2026 results (for the quarter ended October 3):
1. Revenue was $3.86 billion, up 84% year over year—10% above the market’s $3.48 billion estimate and even above the high end of the company’s own $3.3–$3.6 billion guidance.
2. Adjusted earnings per share were $4.43, up from just $1.67 in the same period last year and 35% above the market’s $3.27 estimate.
3. Revenue from cloud and AI infrastructure plus communications networks was $2.37 billion, up 179% year over year. For the full year, this segment generated $9.25 billion, or 64% of total revenue.
4. Guidance for next year is even stronger: FY2027 revenue of $17.5–$19.5 billion and adjusted earnings per share of $15.50–$17.50, with both midpoint figures well above market expectations. The stock was also up about 19.5% in premarket trading this morning.
My take: The real significance of this earnings report isn’t “how much it grew,” but “who’s footing the bill.” The cloud and AI infrastructure business generated $9.25 billion for the year, and the ZT Systems rack business—acquired from AMD last October—is the engine behind that growth. Cloud providers are putting real money into AI racks. But don’t get carried away: $0.42 of the $4.43 in earnings per share came from tariff refunds, and next year’s guidance for operating margins of 7.0–7.5% is actually below this quarter’s 9.0%. There are two possible paths: if Helios rack shipments ramp up in time and margins hold, more of this AI infrastructure spending will keep flowing to contract manufacturers; if orders slow, the valuation gains could be the first to reverse.