Tonight at 21:30, the U.S. October Consumer Price Index will be released—and whether Monday’s revenge rally can stay alive hinges on this one report.
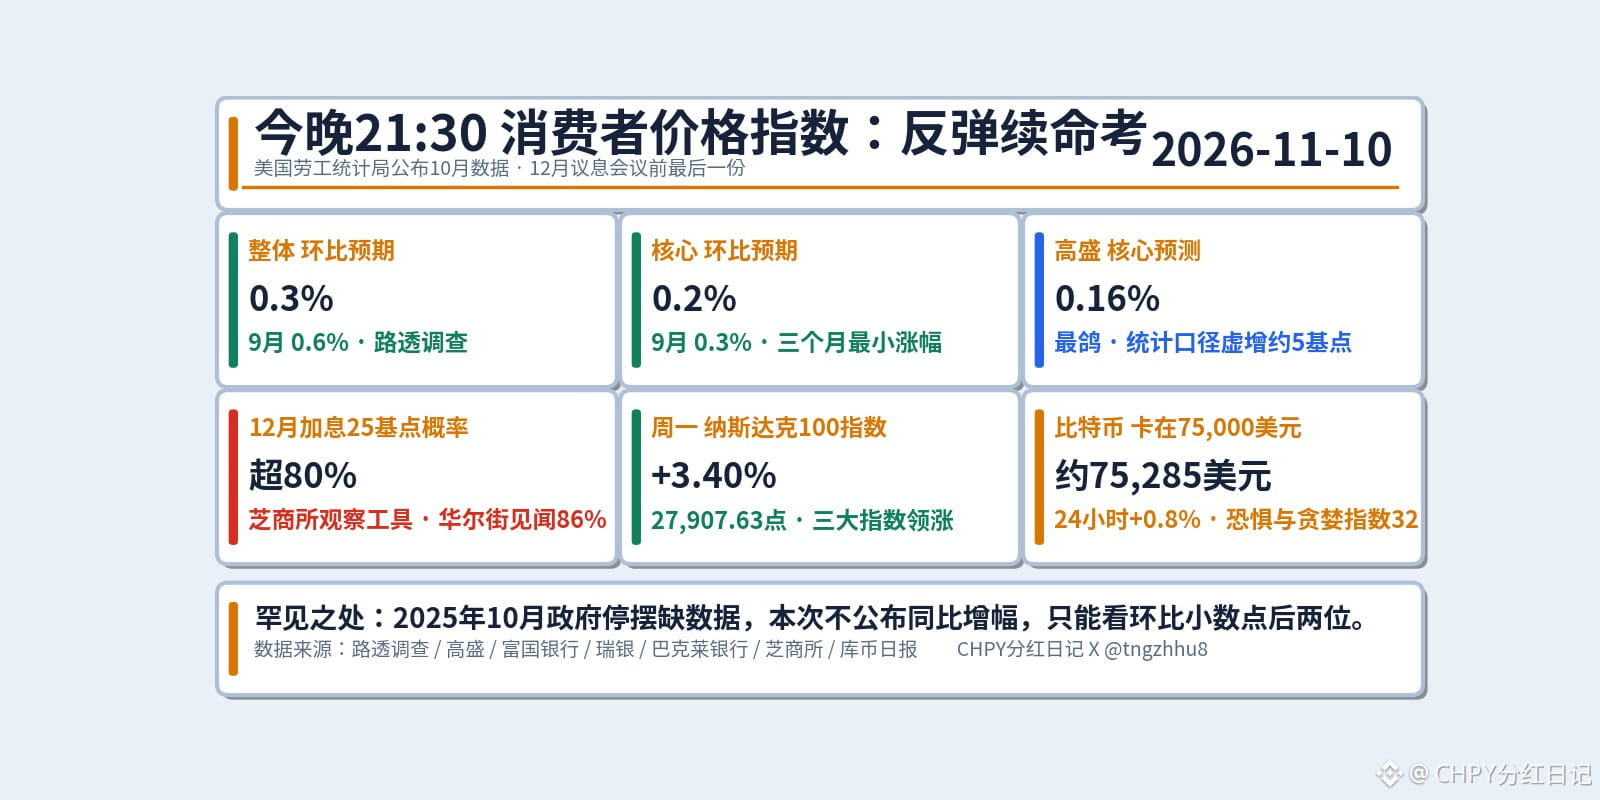
First, the forecasts: A Reuters poll shows headline CPI is expected to rise 0.3% month over month, down from 0.6% in September. Core CPI, which excludes food and energy prices, is expected to rise 0.2%, down from 0.3% in September and potentially the smallest increase in three months. The differences are hiding in the second decimal place: Goldman Sachs is the most dovish, forecasting just 0.16% for core CPI; Wells Fargo expects 0.21%, UBS 0.23%, JPMorgan 0.23%, and Barclays 0.2%. Gasoline prices are expected to fall about 1% month over month.
This report has a rare peculiarity: there will be no year-over-year data. During the U.S. federal government shutdown in October 2025, the Bureau of Labor Statistics did not collect price data for the month, leaving it without a comparison base period. Year-over-year changes in headline and core CPI, as well as year-over-year real wage data, will all be missing. Markets will have to make their judgment based solely on the monthly readings. Using an interpolation method, Bank of America estimates headline inflation at about 3.8% year over year and core inflation at about 2.7%—both 0.1 percentage point higher than in September and far above the Fed’s 2% inflation target.
More importantly, this is the last CPI report before the Fed’s December policy meeting. The next CPI report won’t be released until later on the day of the policy decision. The CME FedWatch tool shows that markets are pricing in more than an 80% chance of a 25-basis-point rate hike in December; Wallstreetcn puts the figure at 86%.
The transmission mechanism is straightforward, with three scenarios: If core CPI rises 0.2% month over month or less, rate-hike pricing could ease, giving Monday’s rally a reason to stay alive, with the Nasdaq 100 first eyeing the 28,000 mark. If core CPI rises 0.3%, a hike is all but certain, and Monday’s big green candle will have been just an oversold rebound; the inflation relief from falling oil prices will have been disproved. If core CPI rises 0.4% or more, markets will start questioning whether a 25-basis-point hike in December will be enough, and hawkish pricing will return.
There’s another pitfall that’s easy to miss: Goldman Sachs warns that the BLS is filling in the missing base period using the geometric mean of the September and November 2025 indexes. This statistical method will inflate this month’s seasonally adjusted core reading by about 5 basis points. The difference between 0.16% and 0.21% isn’t inflation itself—it’s the statistical methodology. The Fed is really focused on the core Personal Consumption Expenditures Price Index. Goldman estimates it will rise about 0.23% month over month, while UBS’s estimate is 0.20%, equivalent to an annualized rate of about 3.1%. CPI is only an early signal.
Here’s the backdrop from Monday: Brent crude fell more than 5%; the Dow Jones Industrial Average surged 1,104.02 points, or 2.15%, to 52,389.75; the S&P 500 rose 2.35% to 7,549.94, its best performance since April 8; and the Nasdaq Composite gained 2.74% to 25,253.14. The Nasdaq 100 climbed 3.40% to 27,907.63, with all 11 sectors advancing.
But Bitcoin didn’t follow. Bitcoin is around $75,285, up 0.8% over 24 hours, down 2.0% over seven days and down 9.4% over 30 days, stuck around $75,000. The Crypto Fear & Greed Index is at 32, still in fear territory, while Ethereum is around $2,135. U.S. stocks rallied, but Bitcoin didn’t—showing that the crypto market is still waiting for its own catalyst. If tonight’s core monthly reading comes in below expectations, Bitcoin could first target $76,000. If it comes in above expectations, the previous low around $73,700 will be tested again. Spot Bitcoin ETFs saw $201 million in net outflows in a single day, and institutional money hasn’t returned yet.
One final risk to keep in mind: October’s Producer Price Index is also due this Friday, with year-over-year growth expected to accelerate to 6.6%. Upstream price increases have yet to fully filter through. For now, watch the second decimal place in tonight’s monthly reading at 21:30—and hold off on chasing the rally until the numbers are out.
#美国消费者价格指数 #美联储 $BTC
First, the forecasts: A Reuters poll shows headline CPI is expected to rise 0.3% month over month, down from 0.6% in September. Core CPI, which excludes food and energy prices, is expected to rise 0.2%, down from 0.3% in September and potentially the smallest increase in three months. The differences are hiding in the second decimal place: Goldman Sachs is the most dovish, forecasting just 0.16% for core CPI; Wells Fargo expects 0.21%, UBS 0.23%, JPMorgan 0.23%, and Barclays 0.2%. Gasoline prices are expected to fall about 1% month over month.
This report has a rare peculiarity: there will be no year-over-year data. During the U.S. federal government shutdown in October 2025, the Bureau of Labor Statistics did not collect price data for the month, leaving it without a comparison base period. Year-over-year changes in headline and core CPI, as well as year-over-year real wage data, will all be missing. Markets will have to make their judgment based solely on the monthly readings. Using an interpolation method, Bank of America estimates headline inflation at about 3.8% year over year and core inflation at about 2.7%—both 0.1 percentage point higher than in September and far above the Fed’s 2% inflation target.
More importantly, this is the last CPI report before the Fed’s December policy meeting. The next CPI report won’t be released until later on the day of the policy decision. The CME FedWatch tool shows that markets are pricing in more than an 80% chance of a 25-basis-point rate hike in December; Wallstreetcn puts the figure at 86%.
The transmission mechanism is straightforward, with three scenarios: If core CPI rises 0.2% month over month or less, rate-hike pricing could ease, giving Monday’s rally a reason to stay alive, with the Nasdaq 100 first eyeing the 28,000 mark. If core CPI rises 0.3%, a hike is all but certain, and Monday’s big green candle will have been just an oversold rebound; the inflation relief from falling oil prices will have been disproved. If core CPI rises 0.4% or more, markets will start questioning whether a 25-basis-point hike in December will be enough, and hawkish pricing will return.
There’s another pitfall that’s easy to miss: Goldman Sachs warns that the BLS is filling in the missing base period using the geometric mean of the September and November 2025 indexes. This statistical method will inflate this month’s seasonally adjusted core reading by about 5 basis points. The difference between 0.16% and 0.21% isn’t inflation itself—it’s the statistical methodology. The Fed is really focused on the core Personal Consumption Expenditures Price Index. Goldman estimates it will rise about 0.23% month over month, while UBS’s estimate is 0.20%, equivalent to an annualized rate of about 3.1%. CPI is only an early signal.
Here’s the backdrop from Monday: Brent crude fell more than 5%; the Dow Jones Industrial Average surged 1,104.02 points, or 2.15%, to 52,389.75; the S&P 500 rose 2.35% to 7,549.94, its best performance since April 8; and the Nasdaq Composite gained 2.74% to 25,253.14. The Nasdaq 100 climbed 3.40% to 27,907.63, with all 11 sectors advancing.
But Bitcoin didn’t follow. Bitcoin is around $75,285, up 0.8% over 24 hours, down 2.0% over seven days and down 9.4% over 30 days, stuck around $75,000. The Crypto Fear & Greed Index is at 32, still in fear territory, while Ethereum is around $2,135. U.S. stocks rallied, but Bitcoin didn’t—showing that the crypto market is still waiting for its own catalyst. If tonight’s core monthly reading comes in below expectations, Bitcoin could first target $76,000. If it comes in above expectations, the previous low around $73,700 will be tested again. Spot Bitcoin ETFs saw $201 million in net outflows in a single day, and institutional money hasn’t returned yet.
One final risk to keep in mind: October’s Producer Price Index is also due this Friday, with year-over-year growth expected to accelerate to 6.6%. Upstream price increases have yet to fully filter through. For now, watch the second decimal place in tonight’s monthly reading at 21:30—and hold off on chasing the rally until the numbers are out.
#美国消费者价格指数 #美联储 $BTC