Analysts’ average price target is $285, more than 20% above the current price, and results have beaten expectations in each of the past two quarters—but the stock is still 14% below its 52-week high. Ahead of Monday’s earnings report, the first question is whether the residential market, which accounts for half of revenue, is holding up.
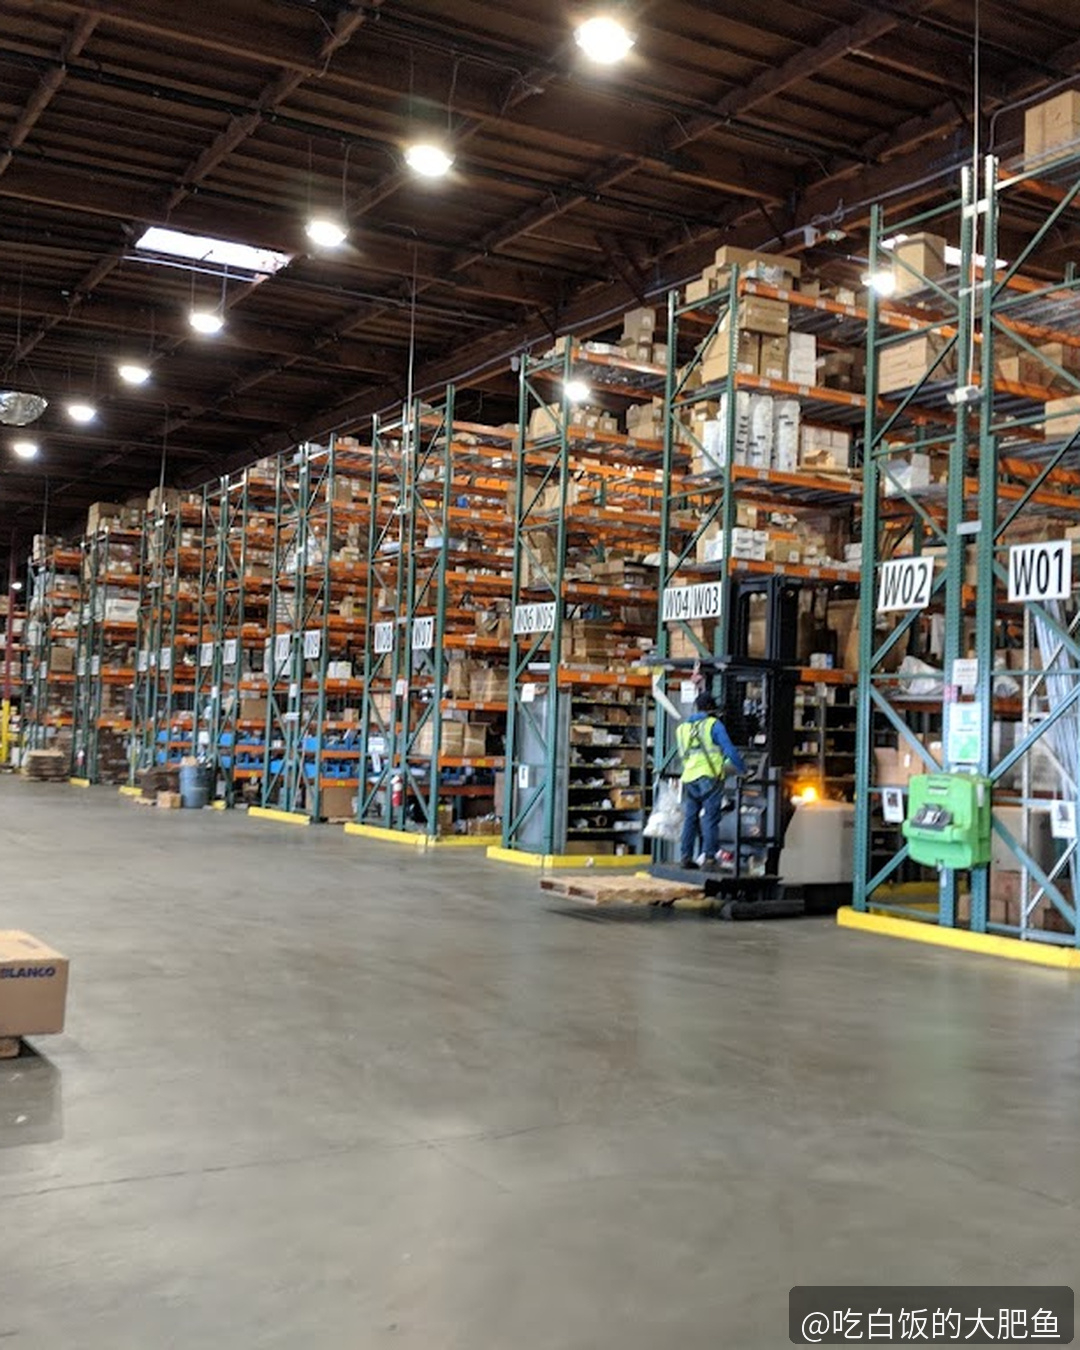
Ferguson ($FERG), North America’s largest distributor of plumbing and building supplies, will report fiscal third-quarter 2026 results before the U.S. market opens on Monday, November 9. The quarter ended in September. Consensus expectations are earnings of about $3.28 to $3.36 per share and revenue of roughly $8.7 billion to $9.0 billion, compared with $2.84 per share in the same quarter last year.
Last quarter’s results were solid: reported August 10, earnings were $3.39 per share, topping the $3.31 estimate, while revenue came in at $8.75 billion. Results have beaten expectations in each of the past two quarters. Analysts’ overall rating is “moderate buy,” with an average price target of $285.35 from 24 firms.
The stock’s performance has been mixed: it closed Friday at $233.70, down 0.83%. It is up 7.83% over the past month and 4.97% year to date. Its 52-week range is $212.13 to $271.64, and its market capitalization is about $46.5 billion.
My take, in three scenarios: A rebound in housing starts and repair demand, with nonresidential and infrastructure orders holding steady, would need to lift revenue above $9.0 billion and earnings above $3.36 per share to justify the price target. If results merely land within the consensus range and management still describes residential demand as weak on the call, treat that as business as usual—don’t read too much into the two straight beats. If results come in near the low end or full-year guidance softens, reassess the valuation in light of the stock’s 14% discount to its high, and wait for the call to break out residential and nonresidential trends.
Ferguson ($FERG), North America’s largest distributor of plumbing and building supplies, will report fiscal third-quarter 2026 results before the U.S. market opens on Monday, November 9. The quarter ended in September. Consensus expectations are earnings of about $3.28 to $3.36 per share and revenue of roughly $8.7 billion to $9.0 billion, compared with $2.84 per share in the same quarter last year.
Last quarter’s results were solid: reported August 10, earnings were $3.39 per share, topping the $3.31 estimate, while revenue came in at $8.75 billion. Results have beaten expectations in each of the past two quarters. Analysts’ overall rating is “moderate buy,” with an average price target of $285.35 from 24 firms.
The stock’s performance has been mixed: it closed Friday at $233.70, down 0.83%. It is up 7.83% over the past month and 4.97% year to date. Its 52-week range is $212.13 to $271.64, and its market capitalization is about $46.5 billion.
My take, in three scenarios: A rebound in housing starts and repair demand, with nonresidential and infrastructure orders holding steady, would need to lift revenue above $9.0 billion and earnings above $3.36 per share to justify the price target. If results merely land within the consensus range and management still describes residential demand as weak on the call, treat that as business as usual—don’t read too much into the two straight beats. If results come in near the low end or full-year guidance softens, reassess the valuation in light of the stock’s 14% discount to its high, and wait for the call to break out residential and nonresidential trends.