
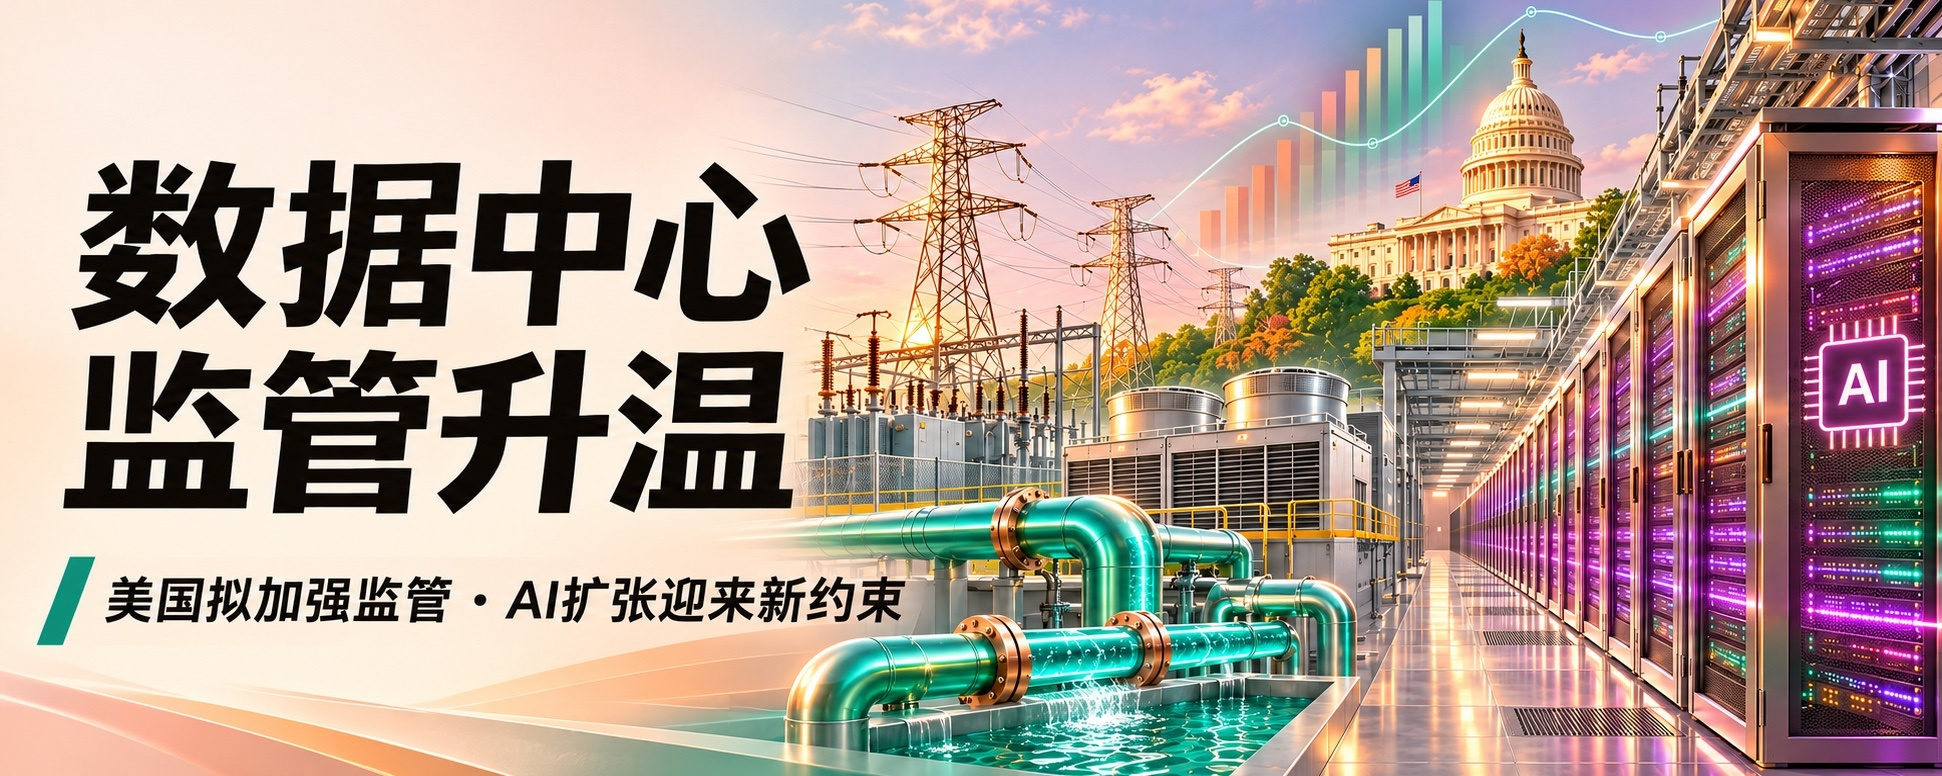
The AI industry is facing a new reality: computing capacity can continue to expand, but electricity, water resources, and regulatory approvals may not keep pace.
Recently, discussions in the U.S. about regulating AI data centers have intensified. With the midterm elections over, Democrats are preparing to push for stricter regulations on AI and data centers in 2027.
This could become a new factor affecting the global AI industry, following chip supply and energy shortages.
1. What is the U.S. preparing to restrict?
On November 4, the U.S. technology policy organization Chamber of Progress submitted policy recommendations to Democratic leaders in Congress, focusing on three areas:
1. Power costs: Who uses the power, and who pays?
It is recommended that data centers with a power demand of 100 megawatts or more be required to cover all incremental costs of additional power supply and related infrastructure, so ordinary residents do not bear extra electricity costs from AI expansion.
2. Water resources: Improve transparency
Encourage large data centers to disclose their water use, establish water-use efficiency standards, and strengthen water resource protection.
3. Permitting and public interest
Tie certain expedited approvals and federal support to whether a project relies on subsidies and whether it can deliver public benefits to the local community.
Note: These are still policy recommendations, not new U.S. federal regulations that are already in full effect.
However, California has already signed several laws concerning data center electricity use, water use, and land use, indicating that regulation is being implemented in some areas.
II. Why could this affect the AI industry?
For the past few years, the core logic of the AI industry has been simple:
Invest more money → build more data centers → buy more GPUs → increase computing capacity.
But now, this chain could face new constraints.
If building data centers means not only buying chips, but also covering the costs of grid upgrades, energy supply, water management, and more, then:
Data center construction costs could rise.
Approval and commissioning timelines for some projects could be extended.
Cloud computing companies could face greater pressure to earn returns on their capital expenditures.
The expansion of AI computing capacity could be slower than previously expected.
The key question is no longer just whether there is money to buy GPUs, but whether those GPUs can be deployed, powered up, and made profitable in time.
III. Which U.S. stocks are worth watching?
Category 1: AI chips and semiconductors
Nvidia (NVDA), AMD, Broadcom (AVGO), Micron (MU).
If data center construction slows, purchases of new servers and chips could be affected.
But that does not mean demand for these companies will necessarily decline. The actual impact depends on orders, customer capital expenditures, and the extent of project delays.
Category 2: Cloud computing and data center operators
Microsoft (MSFT), Amazon (AMZN), Google (GOOGL), Oracle (ORCL).
These companies need to carefully assess the costs of additional power and infrastructure, as well as whether AI investments can ultimately generate sufficient revenue and profits.
Category 3: Power and data center infrastructure
Companies in power equipment, grid construction, liquid cooling, and energy management could instead see new demand.
If regulators require data centers to cover the costs of grid upgrades and energy-efficiency improvements themselves, investment in related infrastructure may not decrease and could even increase.
💡 IV. Competition in AI is shifting from chips to overall infrastructure
This round of regulatory changes is worth taking seriously, but it should not simply be viewed as bad news for AI.
In the past, the market focused on:
Who has the most GPUs? Whose AI models are the strongest?
Going forward, three more questions may need to be added:
Who can secure a long-term, reliable power supply at a reasonable price?
Who can build and operate data centers at a lower cost?
Who can make massive AI capital expenditures truly pay off?
Tighter regulation could raise the bar for the industry and force some underfunded projects out of the competition.
But for companies with capital, access to power, mature infrastructure, and high operational efficiency, it could also create a competitive advantage.
The real concern is not that AI will stop advancing, but that expectations for AI growth and investment returns may be too high.
If investment in AI continues to grow rapidly but revenue and profits fail to keep pace, technology stock valuations could face a reset.
One final question:
What will be the biggest bottleneck for the AI industry in the future: chip computing power, power supply, or the ability to generate commercial profits?
Are you more bullish on AI chip companies or on the power and infrastructure industries behind them?