Good morning, Saturday. The coffee’s brewed, and last night’s nonfarm report is finally out ☕
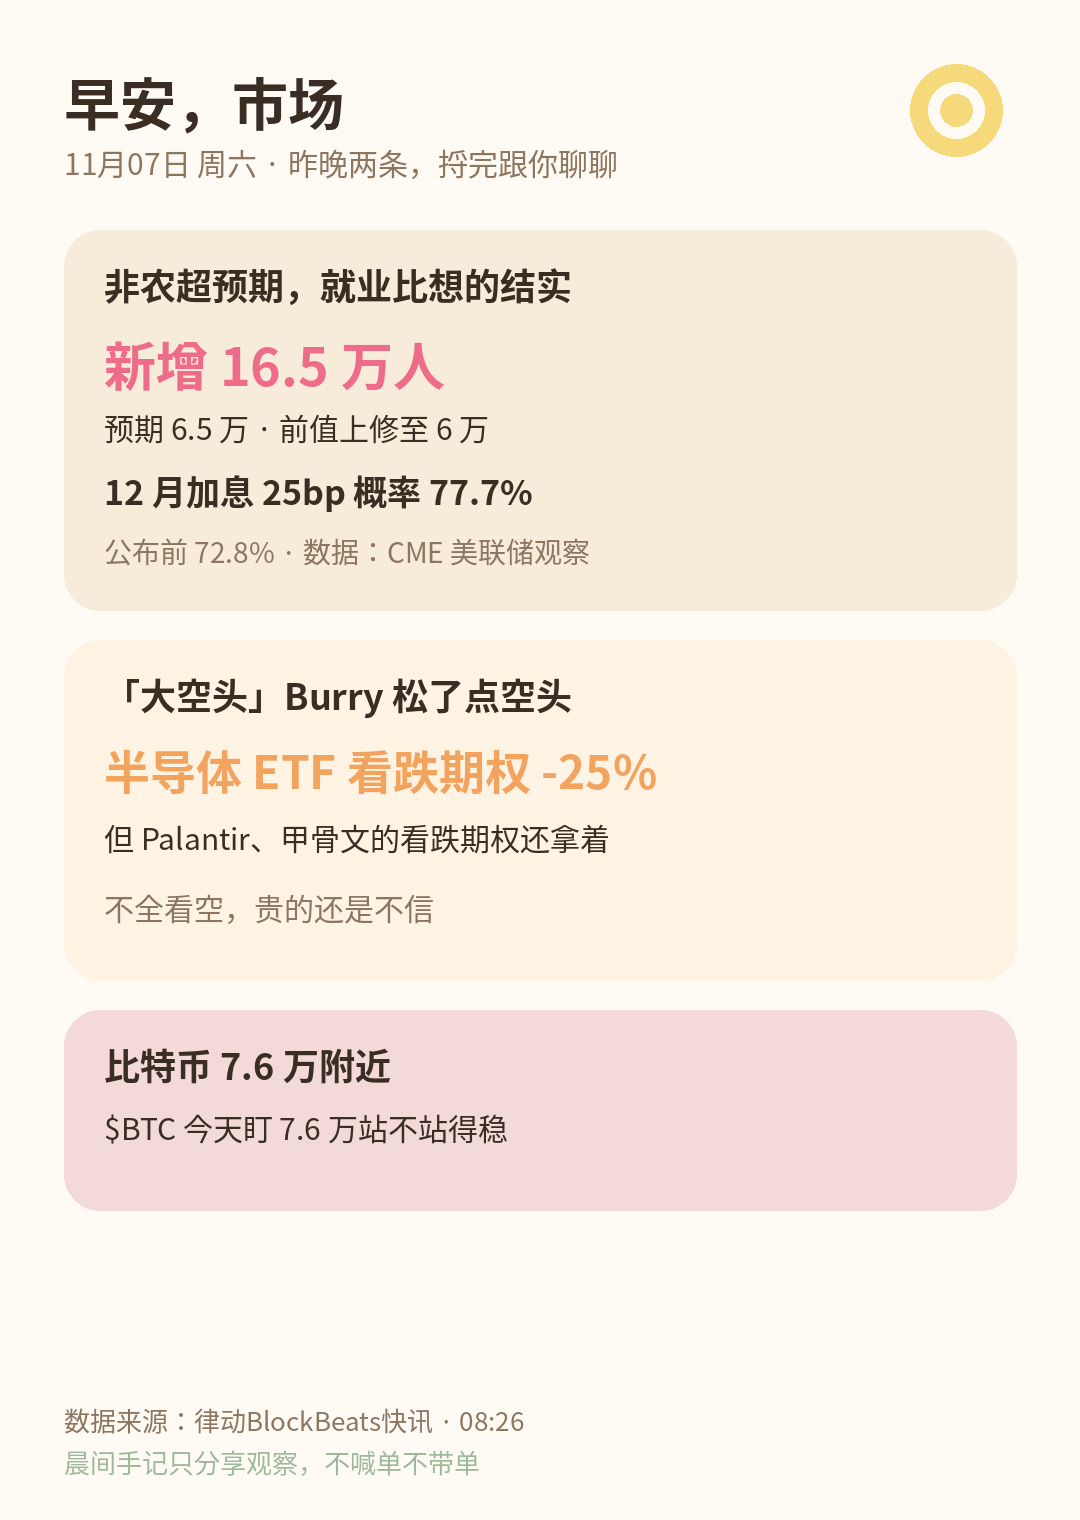
First, the U.S. added 165,000 jobs in October, far above expectations of 65,000. The previous figure was also revised up from 29,000 to 60,000. My take: the job market is much sturdier than expected. No wonder the odds of a 25-basis-point rate hike in December on CME jumped to 77.7%, up from 72.8% before the report. The market has more or less started treating a hike as the default option.
Second, “Big Short” investor Burry updated his holdings: he cut his put options on semiconductor ETFs by 25%, but is still holding puts on Palantir and Oracle. My take: he’s eased up a little on his bet against chips, but his skepticism toward AI darling stocks hasn’t budged. Basically, he’s saying, “I’m not bearish on everything, but I still don’t trust the expensive stuff.”
What I’m watching today: after rate-hike expectations climbed, can $BTC hold at 76,000? And will U.S. stocks continue to take diverging views on AI stocks?
If a December rate hike does happen, do you think the market will drop first, or has it already priced it in?
First, the U.S. added 165,000 jobs in October, far above expectations of 65,000. The previous figure was also revised up from 29,000 to 60,000. My take: the job market is much sturdier than expected. No wonder the odds of a 25-basis-point rate hike in December on CME jumped to 77.7%, up from 72.8% before the report. The market has more or less started treating a hike as the default option.
Second, “Big Short” investor Burry updated his holdings: he cut his put options on semiconductor ETFs by 25%, but is still holding puts on Palantir and Oracle. My take: he’s eased up a little on his bet against chips, but his skepticism toward AI darling stocks hasn’t budged. Basically, he’s saying, “I’m not bearish on everything, but I still don’t trust the expensive stuff.”
What I’m watching today: after rate-hike expectations climbed, can $BTC hold at 76,000? And will U.S. stocks continue to take diverging views on AI stocks?
If a December rate hike does happen, do you think the market will drop first, or has it already priced it in?