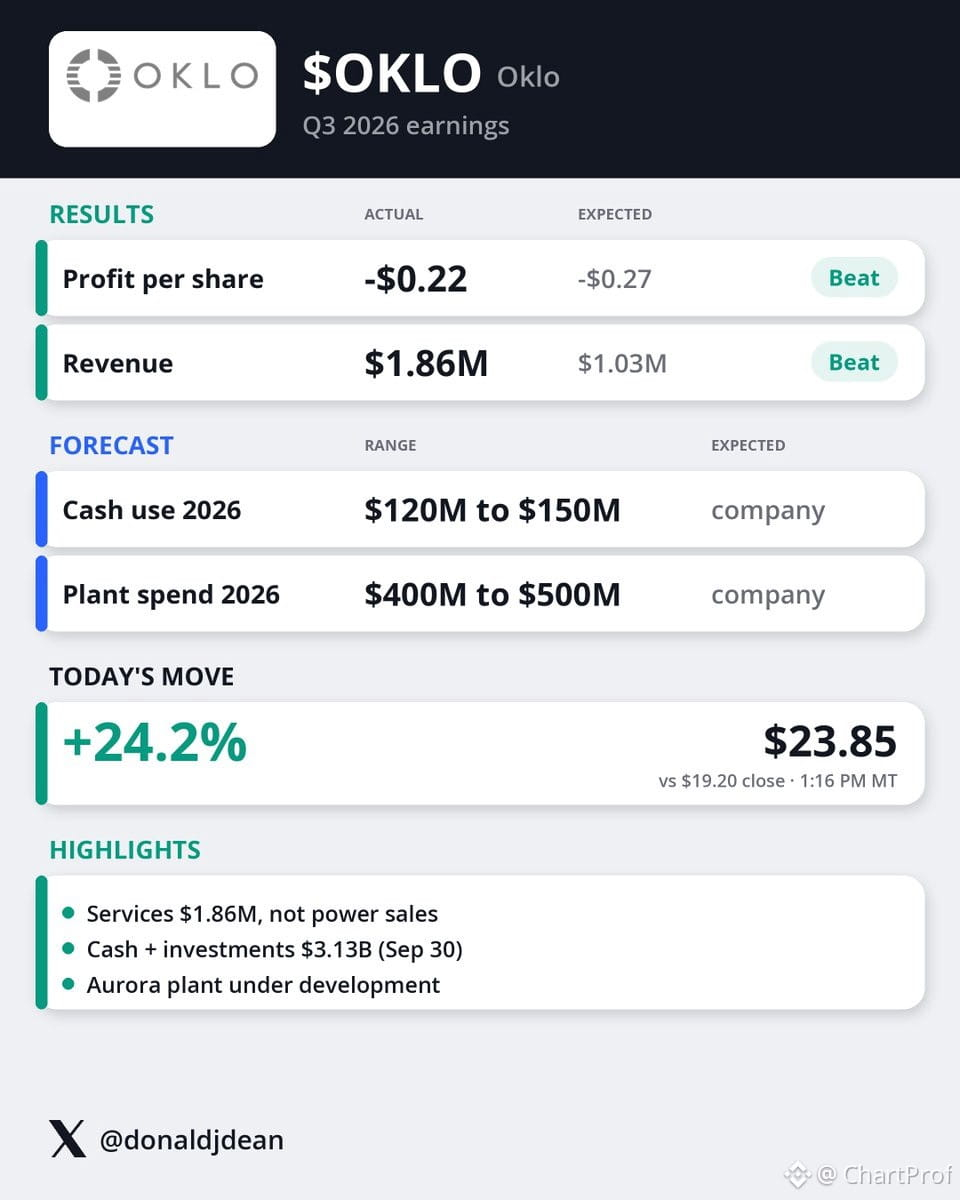
$OKLO just posted Q3 numbers — revenue hit $1.86M vs $1.03M expected, loss tightened to $0.22/share vs $0.27 forecast.
But here's the thing: that revenue is all services, not actual power sales. Aurora's still in development, so we're not at the operational phase yet.
Balance sheet looks solid — $3.13B in cash and investments as of Sept 30. Guidance for 2026 calls for $120M-$150M cash burn and $400M-$500M in plant capex.
So the structure here: beat on revenue, tighter loss, huge cash cushion. But the real catalyst is still ahead — when Aurora goes live and they shift from services to actual power generation. Until then, you're paying for the runway and the promise. Watch the development timeline and how fast they deploy that capex.
But here's the thing: that revenue is all services, not actual power sales. Aurora's still in development, so we're not at the operational phase yet.
Balance sheet looks solid — $3.13B in cash and investments as of Sept 30. Guidance for 2026 calls for $120M-$150M cash burn and $400M-$500M in plant capex.
So the structure here: beat on revenue, tighter loss, huge cash cushion. But the real catalyst is still ahead — when Aurora goes live and they shift from services to actual power generation. Until then, you're paying for the runway and the promise. Watch the development timeline and how fast they deploy that capex.