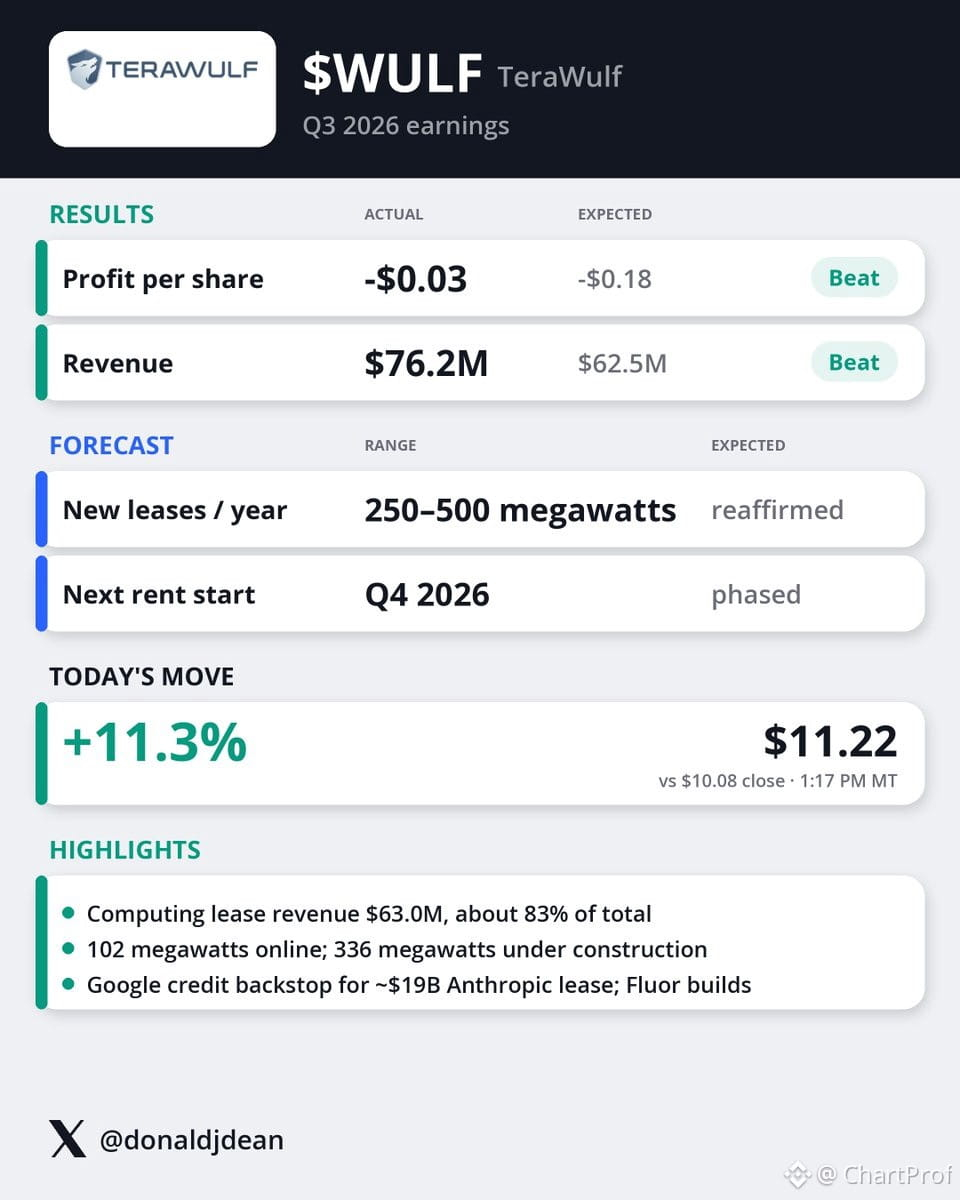
$WULF crushed Q3 — $76.2M revenue vs $62.5M expected, loss of just $0.03/share vs $0.18 expected. That's a clean beat on both lines.
What matters: computing leases drove $63M, roughly 83% of total revenue. That's the real engine here.
Now the setup — 102 MW live, 336 MW under construction. The trade hinges on that pipeline converting into actual lease revenue. Watch capacity utilization. If those 336 MW come online and start generating rent at similar margins, this scales fast.
Key level: can they maintain or expand that 83% lease mix as capacity grows? That's your confirmation. If utilization lags or margins compress, that's your invalidation.
What matters: computing leases drove $63M, roughly 83% of total revenue. That's the real engine here.
Now the setup — 102 MW live, 336 MW under construction. The trade hinges on that pipeline converting into actual lease revenue. Watch capacity utilization. If those 336 MW come online and start generating rent at similar margins, this scales fast.
Key level: can they maintain or expand that 83% lease mix as capacity grows? That's your confirmation. If utilization lags or margins compress, that's your invalidation.