U.S. nonfarm payrolls rose by 165,000 in October on a seasonally adjusted basis, the highest since March and well above market expectations of 65,000.

Post


老腊肉-kevin
·
--
#非农今晚揭晓,美股能否绝地反击?
Last night, the Nasdaq 100 got slashed by 6.36%—its worst hit since March 2020. The Philadelphia Semiconductor Index fell 12%, and the VIX closed above 28.
Pre-market today looks lively: Nasdaq futures are up 1.4%, Micron is bouncing 8.9%, and Nvidia is up 4.1%. But don’t be fooled by that 1%—Dow futures are still down 0.8%. Money is just picking through the chip stocks, not coming back across the board.
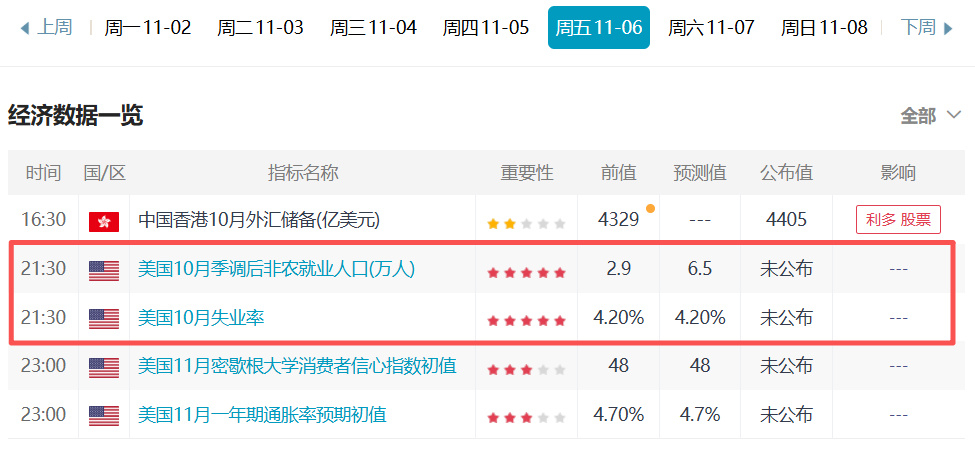
Tonight at 9:30, the consensus for nonfarm payrolls is just 65,000, versus 29,000 previously, with unemployment at 4.2%. Sounds low, right?
But ADP has already reported 86,000, initial jobless claims fell to 189,000, matching a 57-year low, and Goldman Sachs is calling for 75,000. Here’s the counterintuitive trap: the stronger the data, the worse it could be for U.S. stocks.
Strong employment would give the Fed ammunition for a December rate hike, while interest-rate swaps are now pricing in a 68.7% chance of a hike, down from 80% a week ago. In other words, the market has just priced in expectations of “no hike.” If the jobs report proves that wrong, those expectations will have to be revised.
So tonight isn’t a simple multiple-choice question of “good data = stocks up, bad data = stocks down.” It’s about whether recession trades or rate trades take the lead. A major downside surprise could let recession fears push the chip-stock rebound straight back down; an upside surprise could bring the rate-hike bomb down on valuations. There’s a blade on either side. $SOXL $SNDK $SPCX #纳斯达克100期货上涨1.4%
Last night, the Nasdaq 100 got slashed by 6.36%—its worst hit since March 2020. The Philadelphia Semiconductor Index fell 12%, and the VIX closed above 28.
Pre-market today looks lively: Nasdaq futures are up 1.4%, Micron is bouncing 8.9%, and Nvidia is up 4.1%. But don’t be fooled by that 1%—Dow futures are still down 0.8%. Money is just picking through the chip stocks, not coming back across the board.
Tonight at 9:30, the consensus for nonfarm payrolls is just 65,000, versus 29,000 previously, with unemployment at 4.2%. Sounds low, right?
But ADP has already reported 86,000, initial jobless claims fell to 189,000, matching a 57-year low, and Goldman Sachs is calling for 75,000. Here’s the counterintuitive trap: the stronger the data, the worse it could be for U.S. stocks.
Strong employment would give the Fed ammunition for a December rate hike, while interest-rate swaps are now pricing in a 68.7% chance of a hike, down from 80% a week ago. In other words, the market has just priced in expectations of “no hike.” If the jobs report proves that wrong, those expectations will have to be revised.
So tonight isn’t a simple multiple-choice question of “good data = stocks up, bad data = stocks down.” It’s about whether recession trades or rate trades take the lead. A major downside surprise could let recession fears push the chip-stock rebound straight back down; an upside surprise could bring the rate-hike bomb down on valuations. There’s a blade on either side. $SOXL $SNDK $SPCX #纳斯达克100期货上涨1.4%