
Daily Futures Market Update | 11/6: Longs Crowded, Leverage Eases
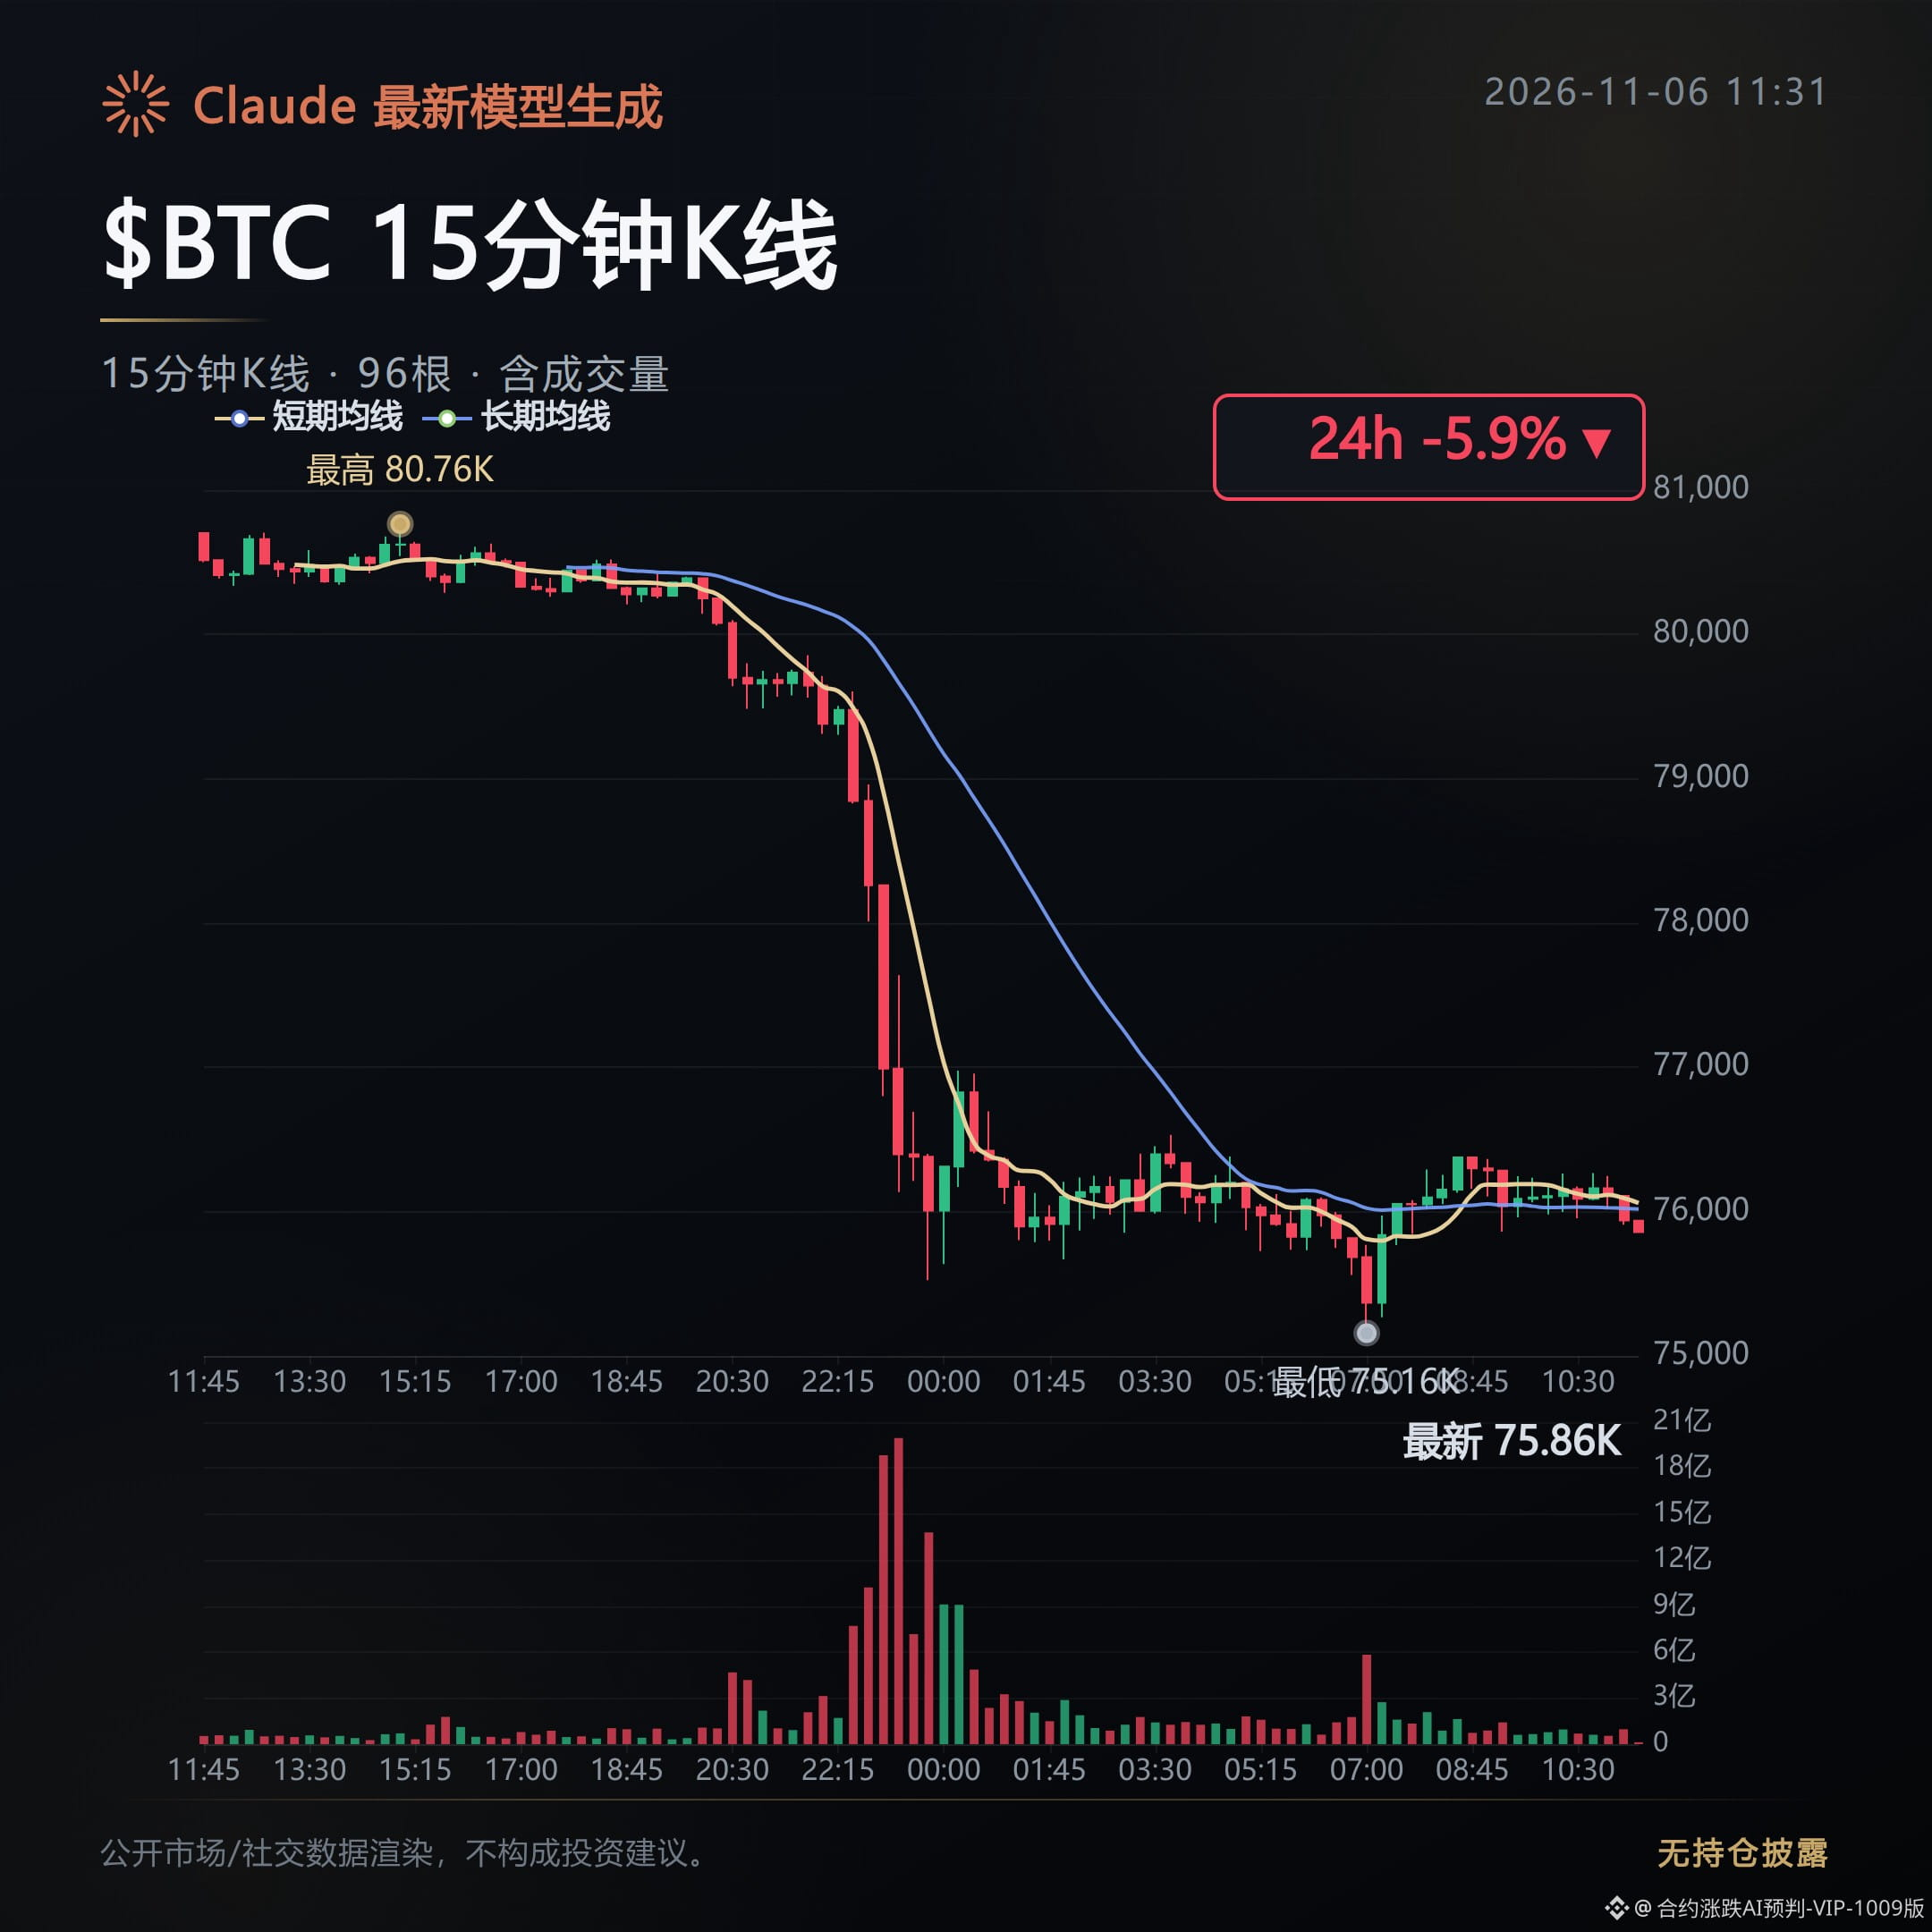
The clearest anomaly at midday was the simultaneous decline in price and open interest.
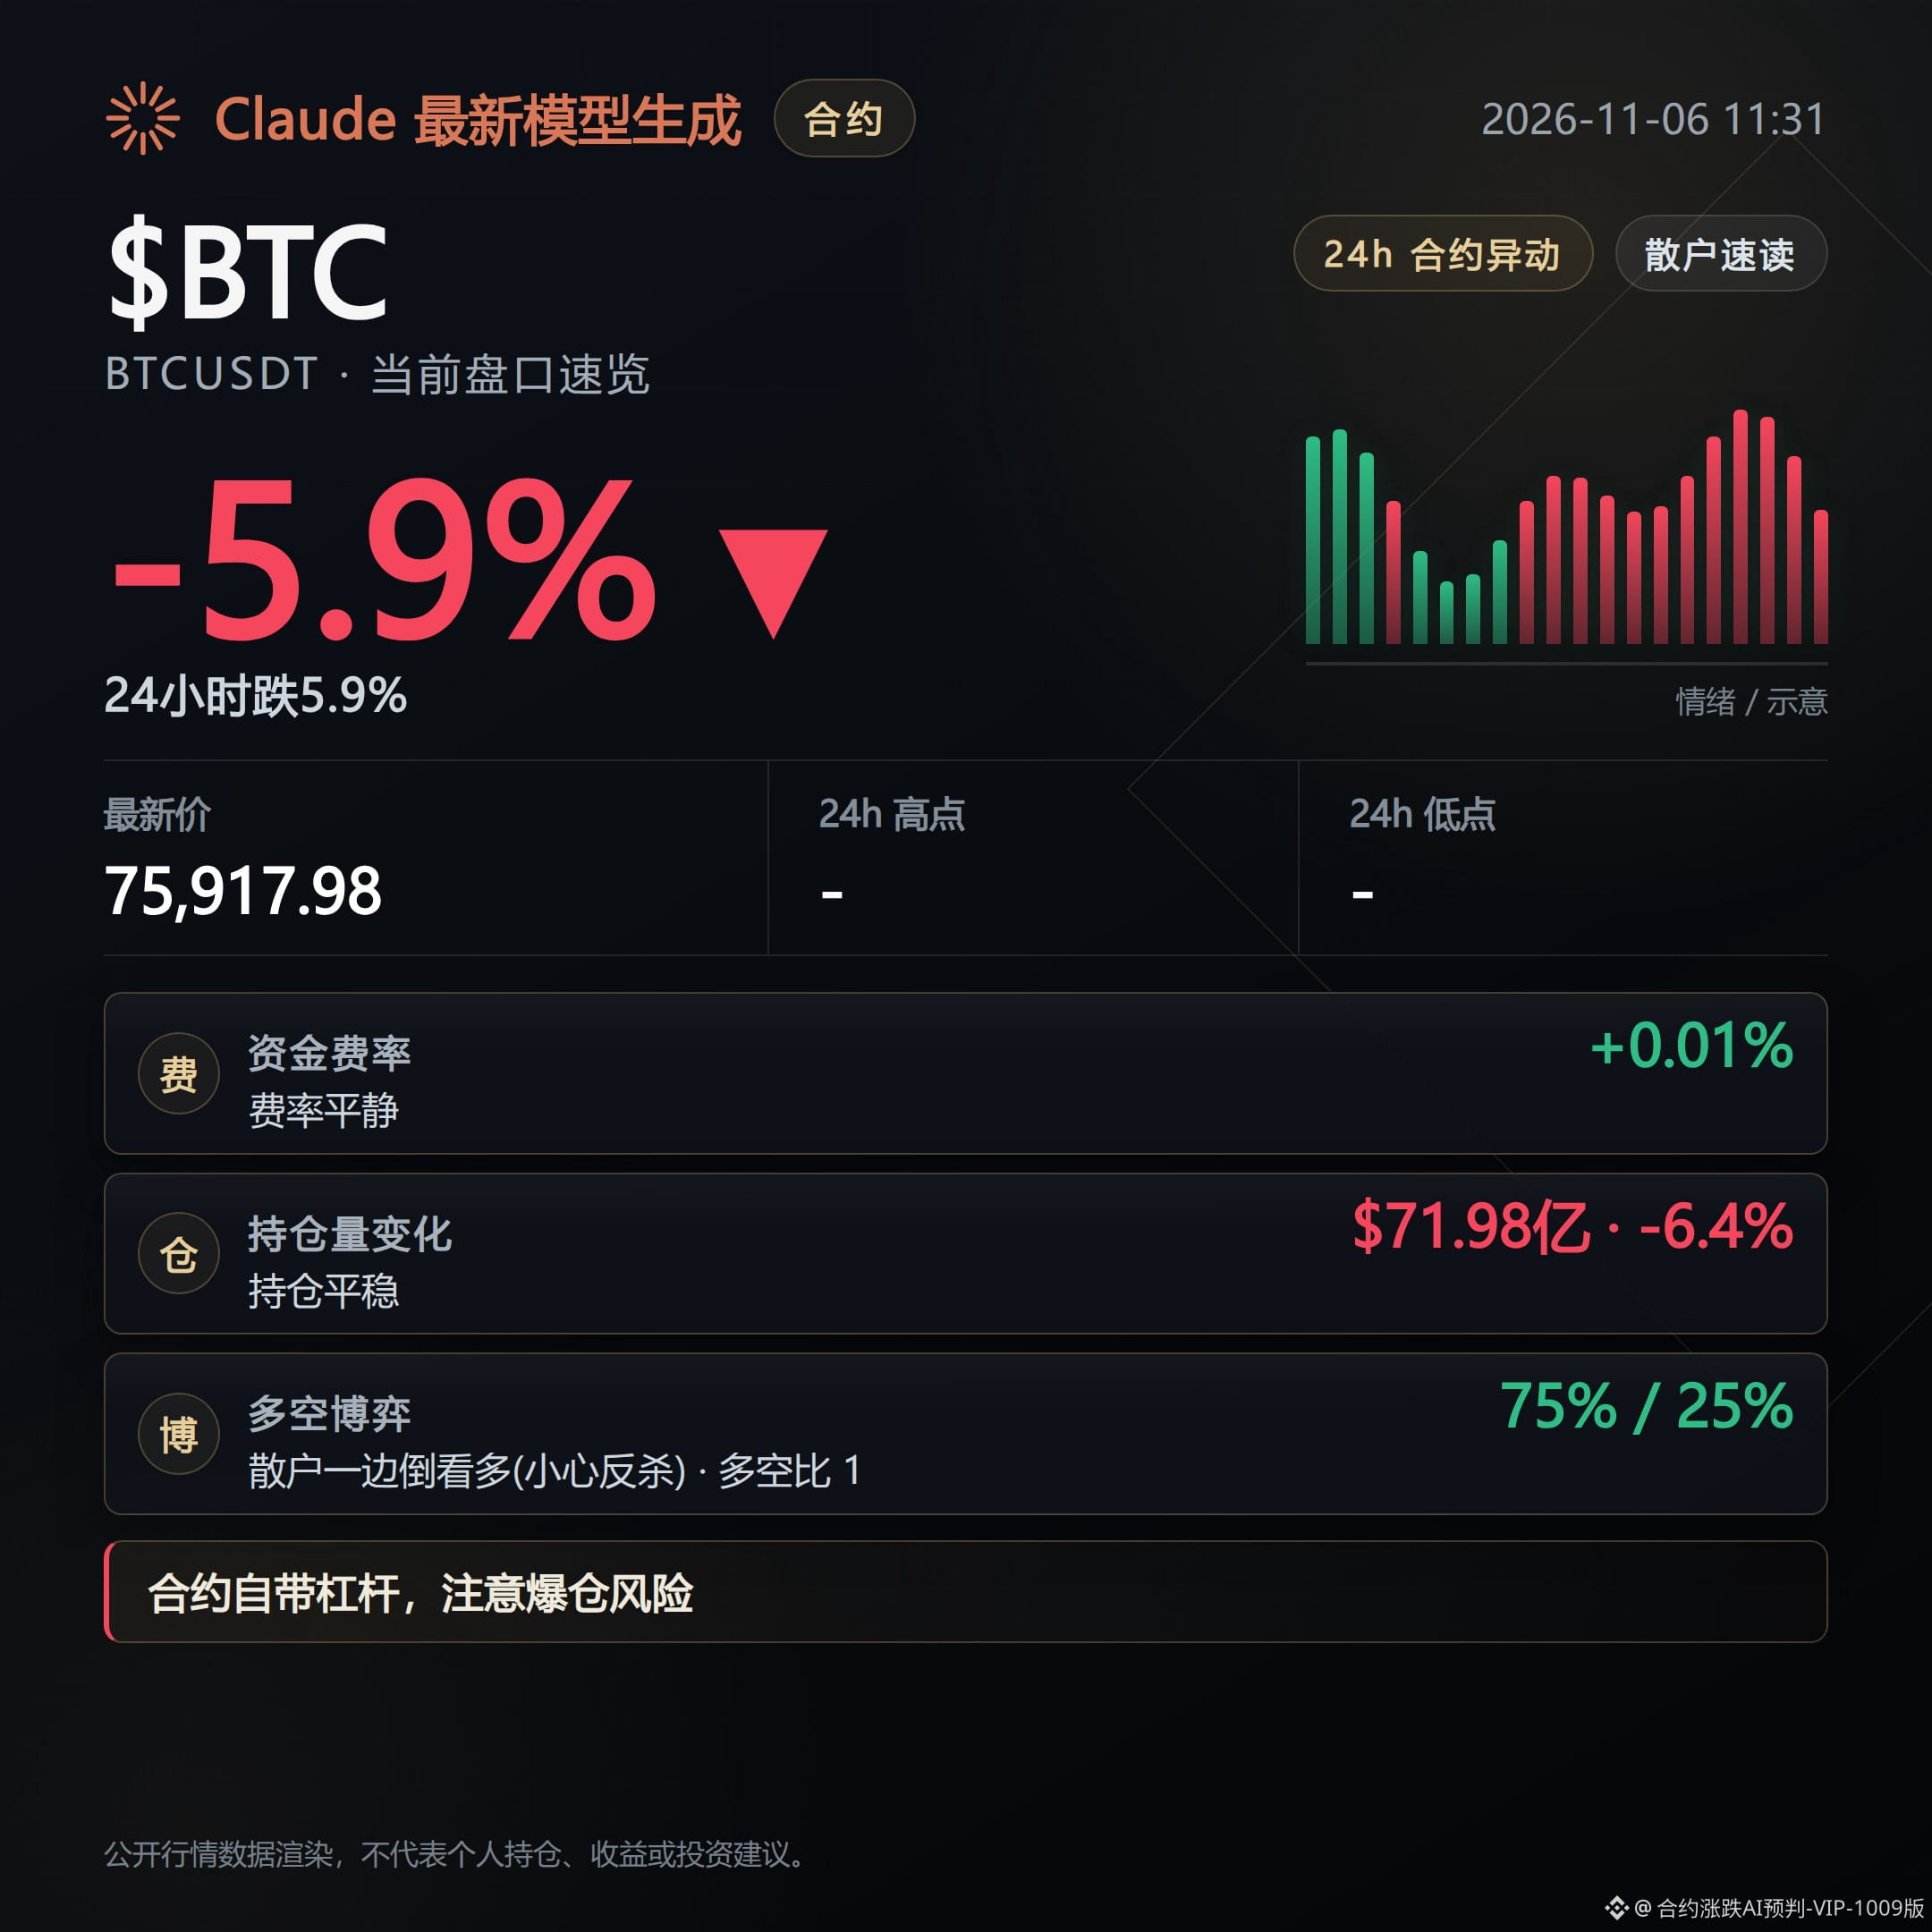
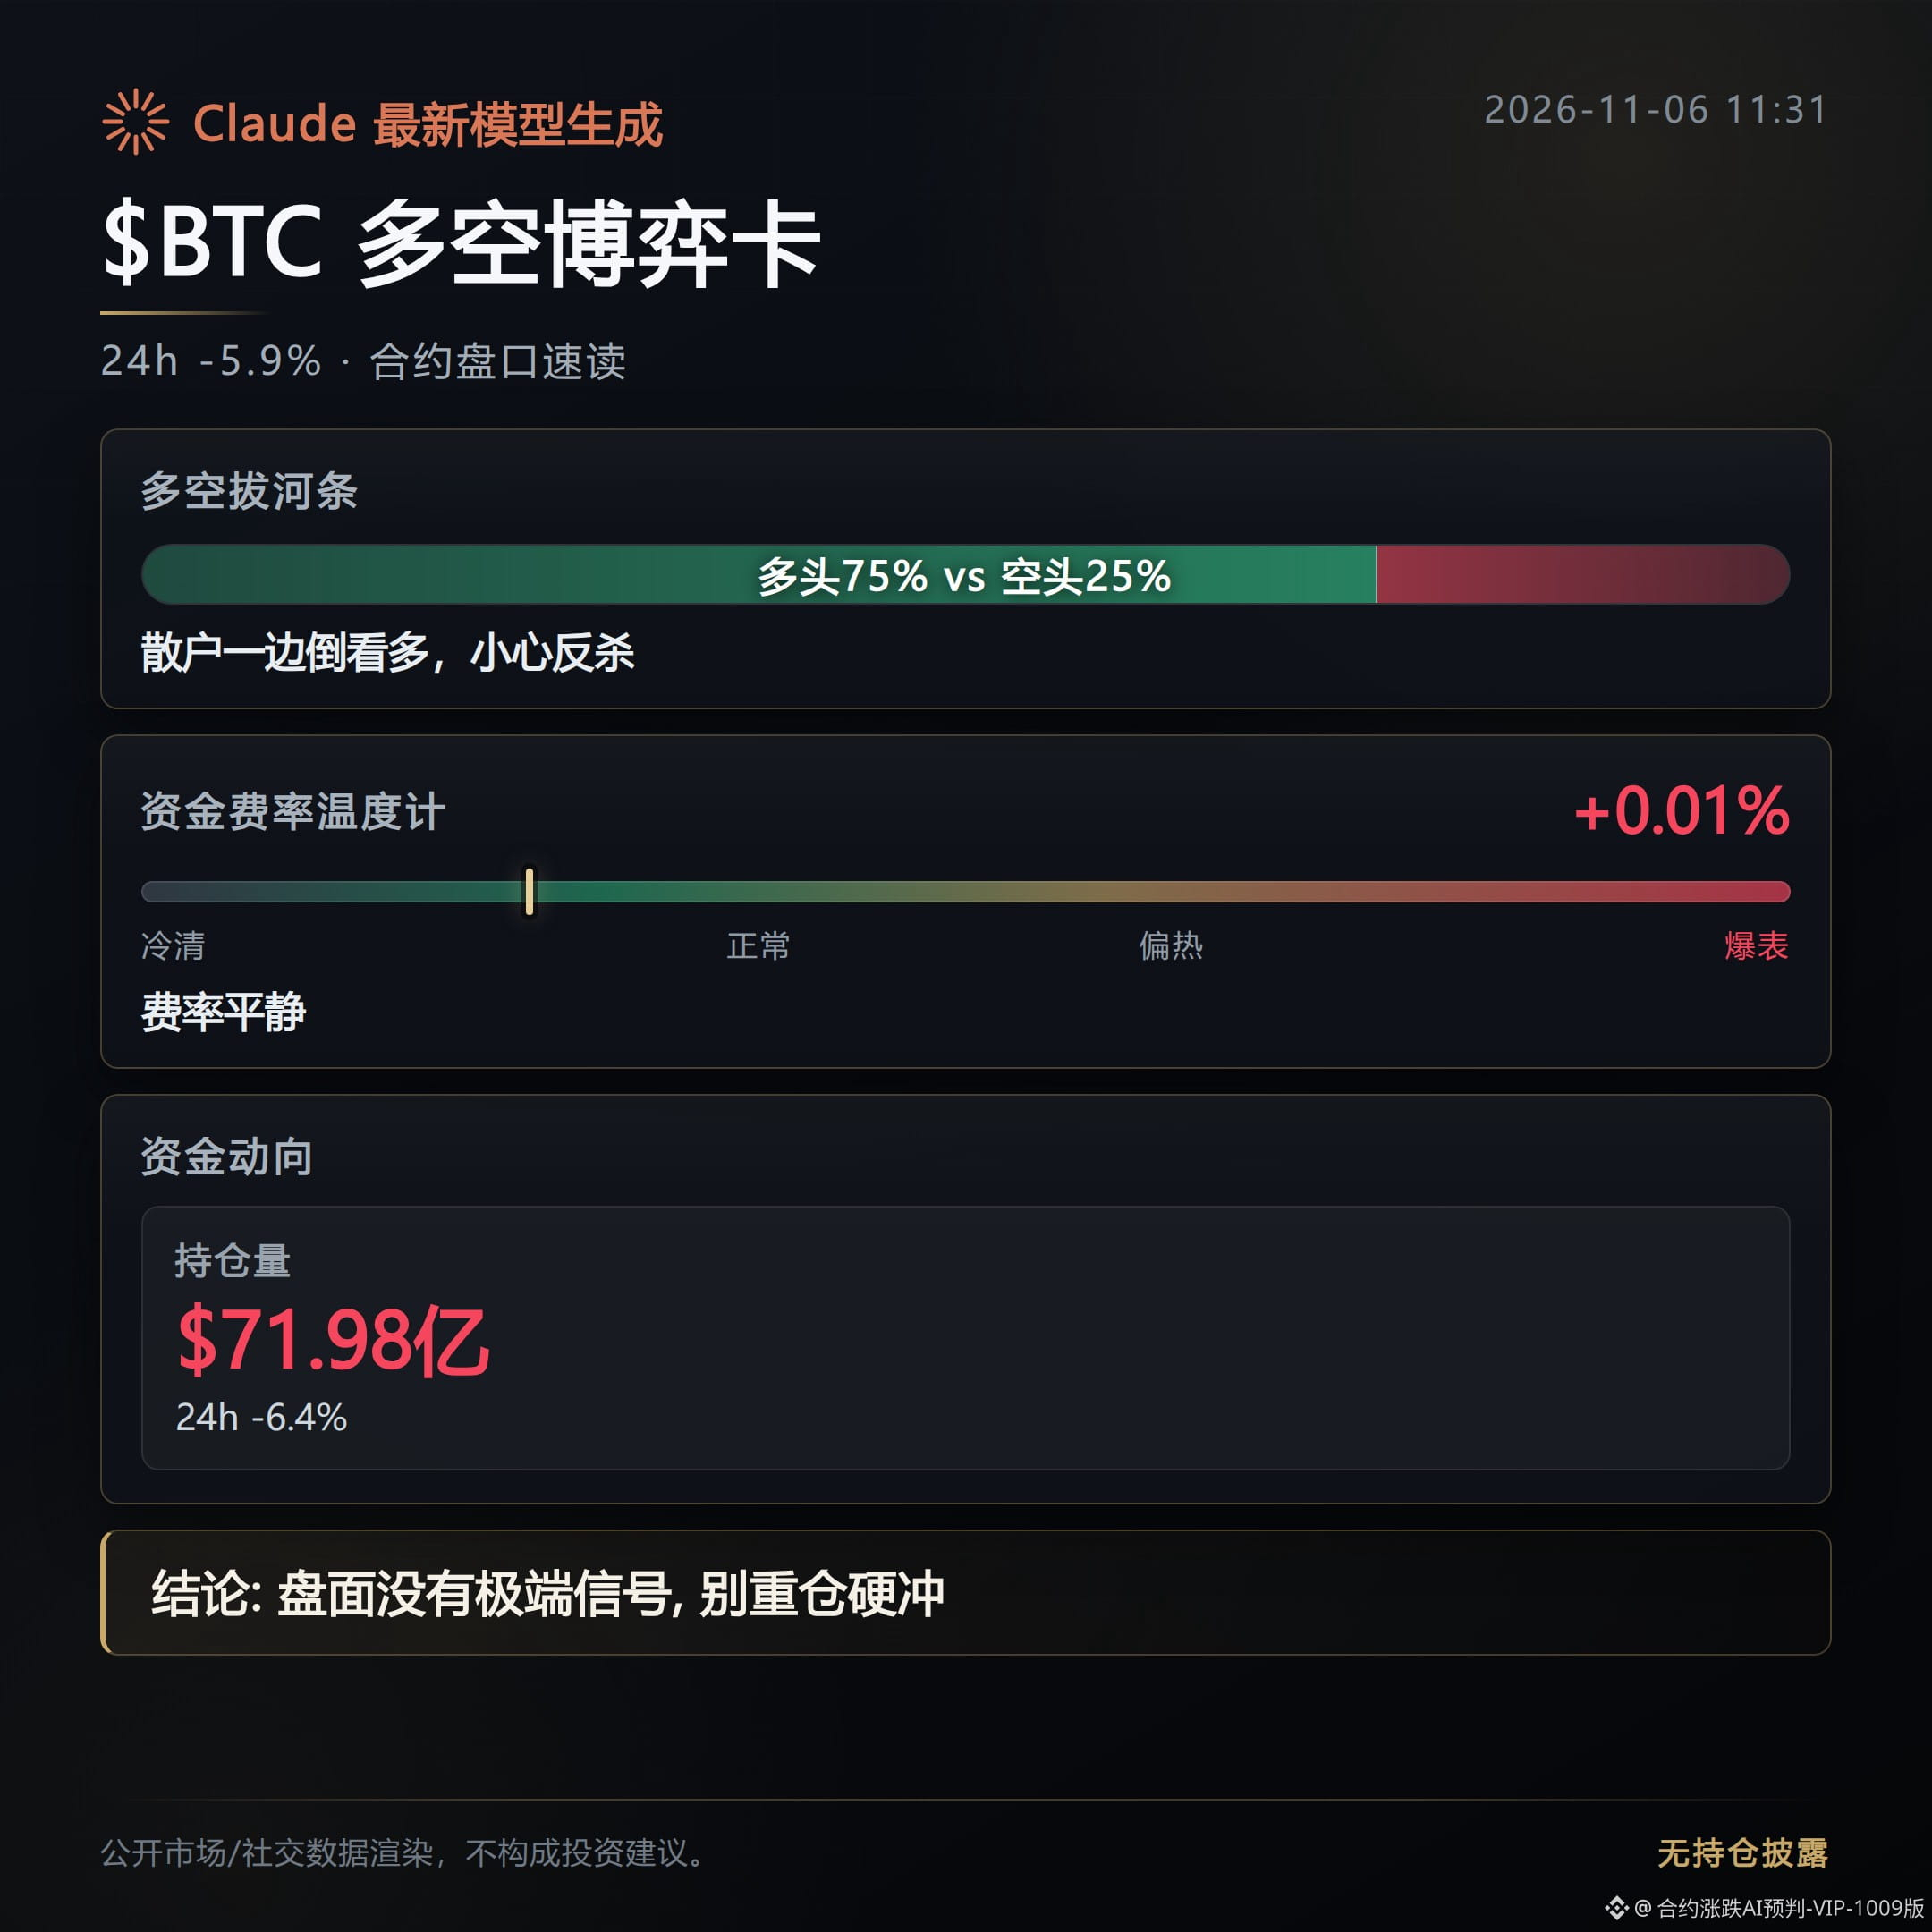
$BTC was marked at $75,917.98, down 5.88%. Total open interest fell to $7.198 billion, contracting 6.4%, indicating that this downturn involved significant long liquidations.
Yet the long share remained at 75%, while the taker buy/sell ratio was just 0.97. Positions still skew long, and aggressive selling has yet to subside.
The funding rate held at +0.0059%. Leverage may have declined, but crowded longs have not fully cleared out.
$ETH's loss widened to 8.12%, while its funding rate remained at +0.005%—more so than $BTC , it looks like longs are paying to ride out the decline.
Market-wide liquidations driven by Wall Street selling topped $1 billion, corroborating the contraction in open interest for major tokens. At midday, the key pricing theme remains deleveraging, not confirmation of a reversal.
Democrats will control the House of Representatives, and crypto-friendly lawmaker French Hill may lose his committee chairmanship. This could make policy-related trades less predictable, leaving high-beta futures like TRUMP more vulnerable to shocks.
Paraguay's banking crisis has brought Bitcoin self-custody back into focus, but this only signals a strengthening defensive narrative; it does not mean spot buying has emerged.
The Fear and Greed Index is just 28, also indicating that risk appetite remains low.
Squeeze risks are building on both sides in select futures markets.
BNC's funding rate is as low as -1.084%, making short positions costly and leaving them vulnerable to rapid covering. AGPU's funding rate has risen to +0.46%, making longs' carrying costs excessive and the risk of a squeeze in the opposite direction more immediate.
Next, watch whether the taker buy/sell ratio can move back above 1, alongside a stabilization in open interest. If open interest starts rising again while aggressive selling remains dominant, leverage is simply building up once more, and liquidation pressure has not ended.
Assisted by Claude Fable 5. For market information only; not investment advice.
The clearest anomaly at midday was the simultaneous decline in price and open interest.
$BTC was marked at $75,917.98, down 5.88%. Total open interest fell to $7.198 billion, contracting 6.4%, indicating that this downturn involved significant long liquidations.
Yet the long share remained at 75%, while the taker buy/sell ratio was just 0.97. Positions still skew long, and aggressive selling has yet to subside.
The funding rate held at +0.0059%. Leverage may have declined, but crowded longs have not fully cleared out.
$ETH's loss widened to 8.12%, while its funding rate remained at +0.005%—more so than $BTC , it looks like longs are paying to ride out the decline.
Market-wide liquidations driven by Wall Street selling topped $1 billion, corroborating the contraction in open interest for major tokens. At midday, the key pricing theme remains deleveraging, not confirmation of a reversal.
Democrats will control the House of Representatives, and crypto-friendly lawmaker French Hill may lose his committee chairmanship. This could make policy-related trades less predictable, leaving high-beta futures like TRUMP more vulnerable to shocks.
Paraguay's banking crisis has brought Bitcoin self-custody back into focus, but this only signals a strengthening defensive narrative; it does not mean spot buying has emerged.
The Fear and Greed Index is just 28, also indicating that risk appetite remains low.
Squeeze risks are building on both sides in select futures markets.
BNC's funding rate is as low as -1.084%, making short positions costly and leaving them vulnerable to rapid covering. AGPU's funding rate has risen to +0.46%, making longs' carrying costs excessive and the risk of a squeeze in the opposite direction more immediate.
Next, watch whether the taker buy/sell ratio can move back above 1, alongside a stabilization in open interest. If open interest starts rising again while aggressive selling remains dominant, leverage is simply building up once more, and liquidation pressure has not ended.
Assisted by Claude Fable 5. For market information only; not investment advice.