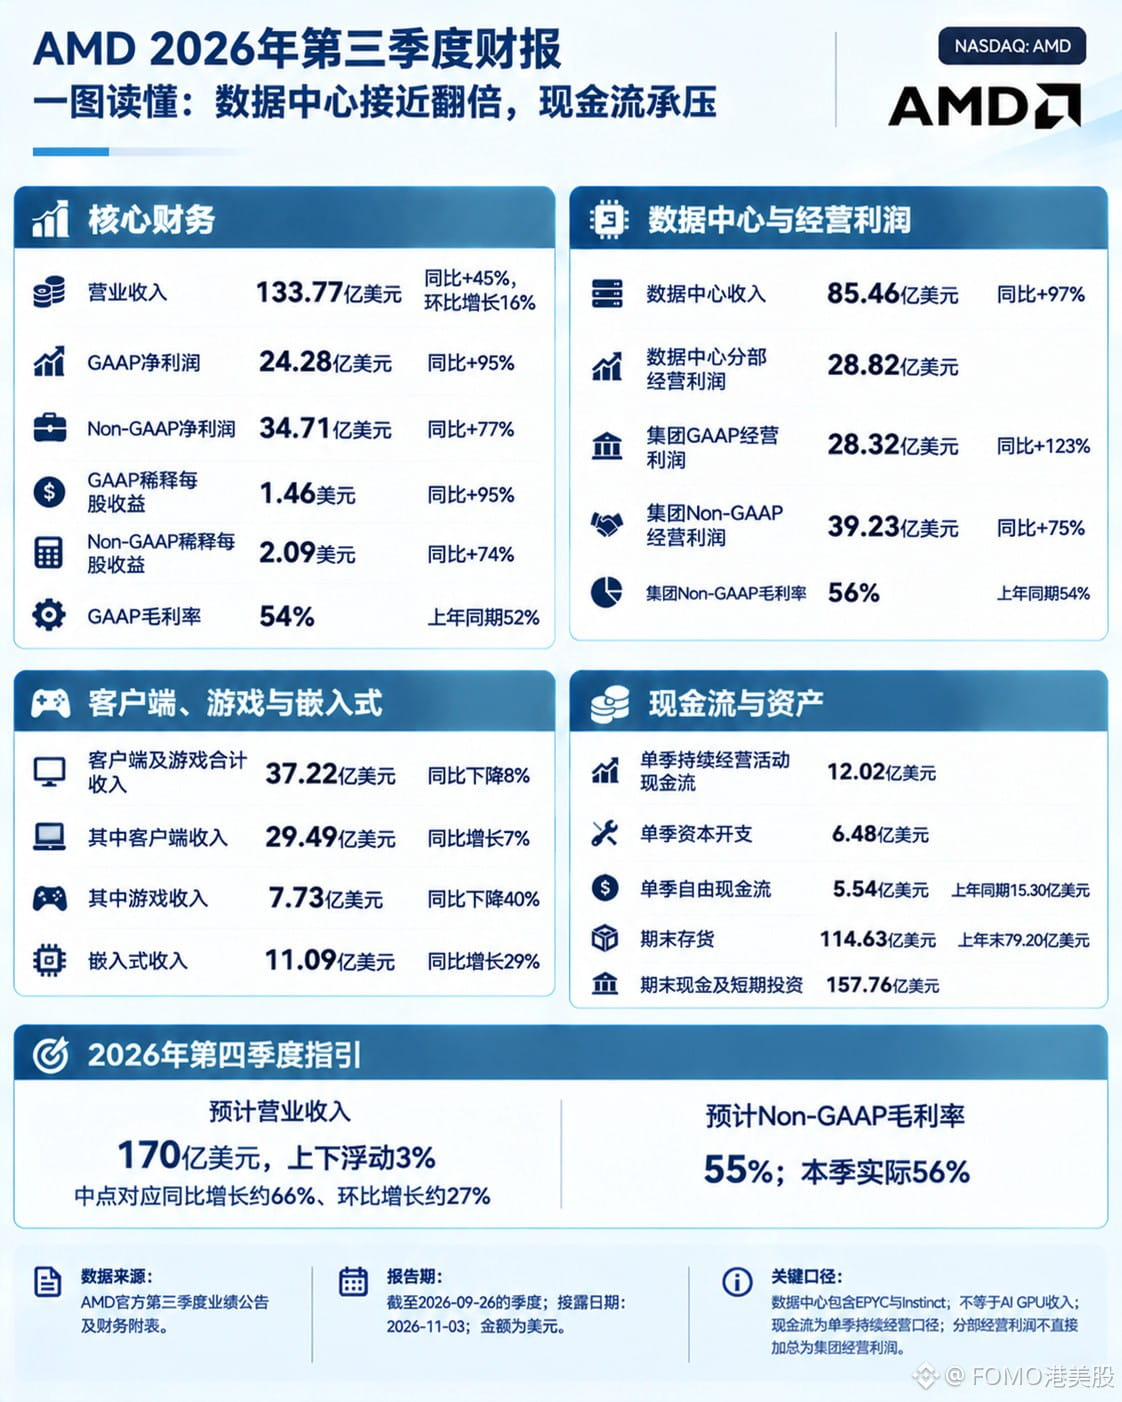
Advanced Micro Devices $AMDB third-quarter revenue was $13.377 billion, up 45% year over year and 16% quarter over quarter; GAAP operating income was $2.832 billion, up 123%. Data center revenue was $8.546 billion, up 97%, making it the main driver of growth for the quarter.
The other three segments diverged. Client revenue was $2.949 billion, up 7%; gaming was $773 million, down 40%. Combined, they totaled $3.722 billion, down 8%. Embedded revenue was $1.109 billion, up 29%. But the $8.546 billion includes both EPYC server processors and Instinct accelerators, so it cannot be treated as pure AI GPU revenue. Gaming is still weighing on the overall business.
Profit rose, but cash flow did not keep pace. Operating cash flow was $1.202 billion, capital expenditures were $648 million, and free cash flow was $554 million, compared with $1.530 billion in the same period last year.
A $2.995 billion increase in inventory tied up cash, bringing quarter-end inventory to $11.463 billion, versus $7.920 billion at the end of last year. Fourth-quarter guidance is $17 billion, plus or minus 3%, implying 66% year-over-year and 27% quarter-over-quarter growth at the midpoint. However, the Non-GAAP gross margin is expected to be 55%, below this quarter’s 56%. Whether inventory can be converted into deliveries and cash receipts is the one thing to watch next quarter.
#AMD #BStocks #股票财报季
The other three segments diverged. Client revenue was $2.949 billion, up 7%; gaming was $773 million, down 40%. Combined, they totaled $3.722 billion, down 8%. Embedded revenue was $1.109 billion, up 29%. But the $8.546 billion includes both EPYC server processors and Instinct accelerators, so it cannot be treated as pure AI GPU revenue. Gaming is still weighing on the overall business.
Profit rose, but cash flow did not keep pace. Operating cash flow was $1.202 billion, capital expenditures were $648 million, and free cash flow was $554 million, compared with $1.530 billion in the same period last year.
A $2.995 billion increase in inventory tied up cash, bringing quarter-end inventory to $11.463 billion, versus $7.920 billion at the end of last year. Fourth-quarter guidance is $17 billion, plus or minus 3%, implying 66% year-over-year and 27% quarter-over-quarter growth at the midpoint. However, the Non-GAAP gross margin is expected to be 55%, below this quarter’s 56%. Whether inventory can be converted into deliveries and cash receipts is the one thing to watch next quarter.
#AMD #BStocks #股票财报季