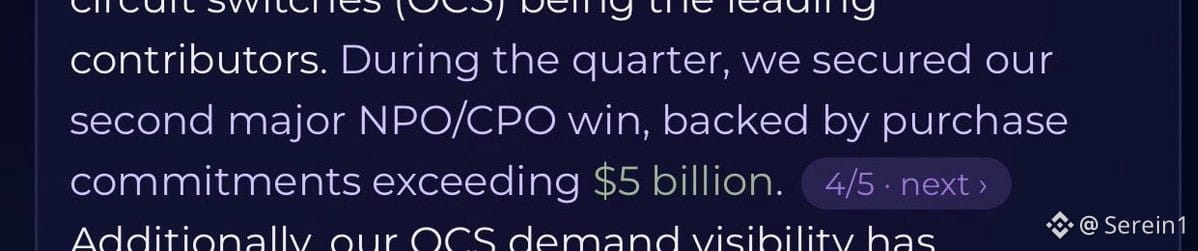
LITE on a standalone basis will probably rise after earnings, because they just announced $5 billion in CPO/NPO orders (unrelated to NVDA).
Margins on this could probably exceed 60%… showing just how profitable laser players can be once they scale up.
(Greensboro alone could generate $5 billion in annual revenue.)
As for the MRVL deal:
- It’s very positive for Marvell strategically. It also makes the remaining laser players much more valuable.
- But LITE shareholders may be crying, since the deal won’t close until 2028, leaving more than a year of overhang in the meantime.
Independent price discovery will also weaken, since many will anchor around 4.5 Marvell shares : 1.
- I think Lumentum shareholders would probably be a bit happier if Marvell’s stock hadn’t sold off before the announcement…
Because LITE was initially valued at about $115 billion, with a 23.9% premium.
- Marvell’s drop immediately revealed the downside of this deal; if it had risen, LITE shareholders might have been a little happier with the valuation.
A fixed-dollar market cap floor would probably be better than a 4.5:1 stock exchange ratio.
There were quite a few trades that were long LITE and short some other name, weighing on valuations across the photonics sector, so at least those pairs may now need to be unwound.
$LITE
Margins on this could probably exceed 60%… showing just how profitable laser players can be once they scale up.
(Greensboro alone could generate $5 billion in annual revenue.)
As for the MRVL deal:
- It’s very positive for Marvell strategically. It also makes the remaining laser players much more valuable.
- But LITE shareholders may be crying, since the deal won’t close until 2028, leaving more than a year of overhang in the meantime.
Independent price discovery will also weaken, since many will anchor around 4.5 Marvell shares : 1.
- I think Lumentum shareholders would probably be a bit happier if Marvell’s stock hadn’t sold off before the announcement…
Because LITE was initially valued at about $115 billion, with a 23.9% premium.
- Marvell’s drop immediately revealed the downside of this deal; if it had risen, LITE shareholders might have been a little happier with the valuation.
A fixed-dollar market cap floor would probably be better than a 4.5:1 stock exchange ratio.
There were quite a few trades that were long LITE and short some other name, weighing on valuations across the photonics sector, so at least those pairs may now need to be unwound.
$LITE