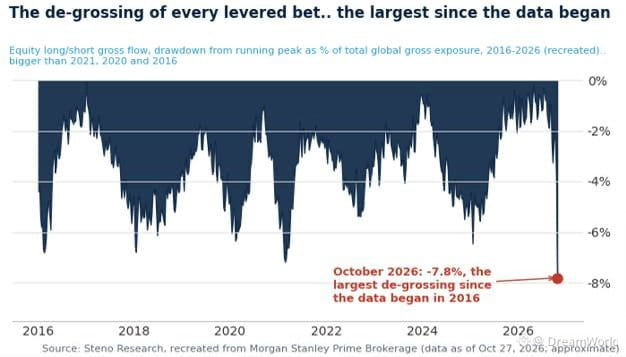

Hedge funds are cutting risk at the fastest pace since 2016.
This is the biggest deleveraging in 10 years 🤯
According to Morgan Stanley, the gross exposure of long/short funds (the sum of their bets on rising and falling prices) has fallen 7.8% from its peak. That’s more than during the sell-offs of 2020 and 2021.
Semiconductors, memory, turbines, cooling, and cloud services are falling the hardest. Funds had poured money into these areas, jumping along the AI supply chain from one bottleneck to the next. The reversal came without an obvious cause: hyperscalers are still investing in data centers, AI labs are going public to fund this spending, and equipment remains in short supply.
Funds may have started doubting that this spending can continue forever, or they may simply be taking profits before year-end.
These are technical selling pressures, so quality companies are getting cheaper for reasons unrelated to their own problems. For those who can pick the right one, this is an opportunity—but no one is promising a quick rebound.
This is the biggest deleveraging in 10 years 🤯
According to Morgan Stanley, the gross exposure of long/short funds (the sum of their bets on rising and falling prices) has fallen 7.8% from its peak. That’s more than during the sell-offs of 2020 and 2021.
Semiconductors, memory, turbines, cooling, and cloud services are falling the hardest. Funds had poured money into these areas, jumping along the AI supply chain from one bottleneck to the next. The reversal came without an obvious cause: hyperscalers are still investing in data centers, AI labs are going public to fund this spending, and equipment remains in short supply.
Funds may have started doubting that this spending can continue forever, or they may simply be taking profits before year-end.
These are technical selling pressures, so quality companies are getting cheaper for reasons unrelated to their own problems. For those who can pick the right one, this is an opportunity—but no one is promising a quick rebound.