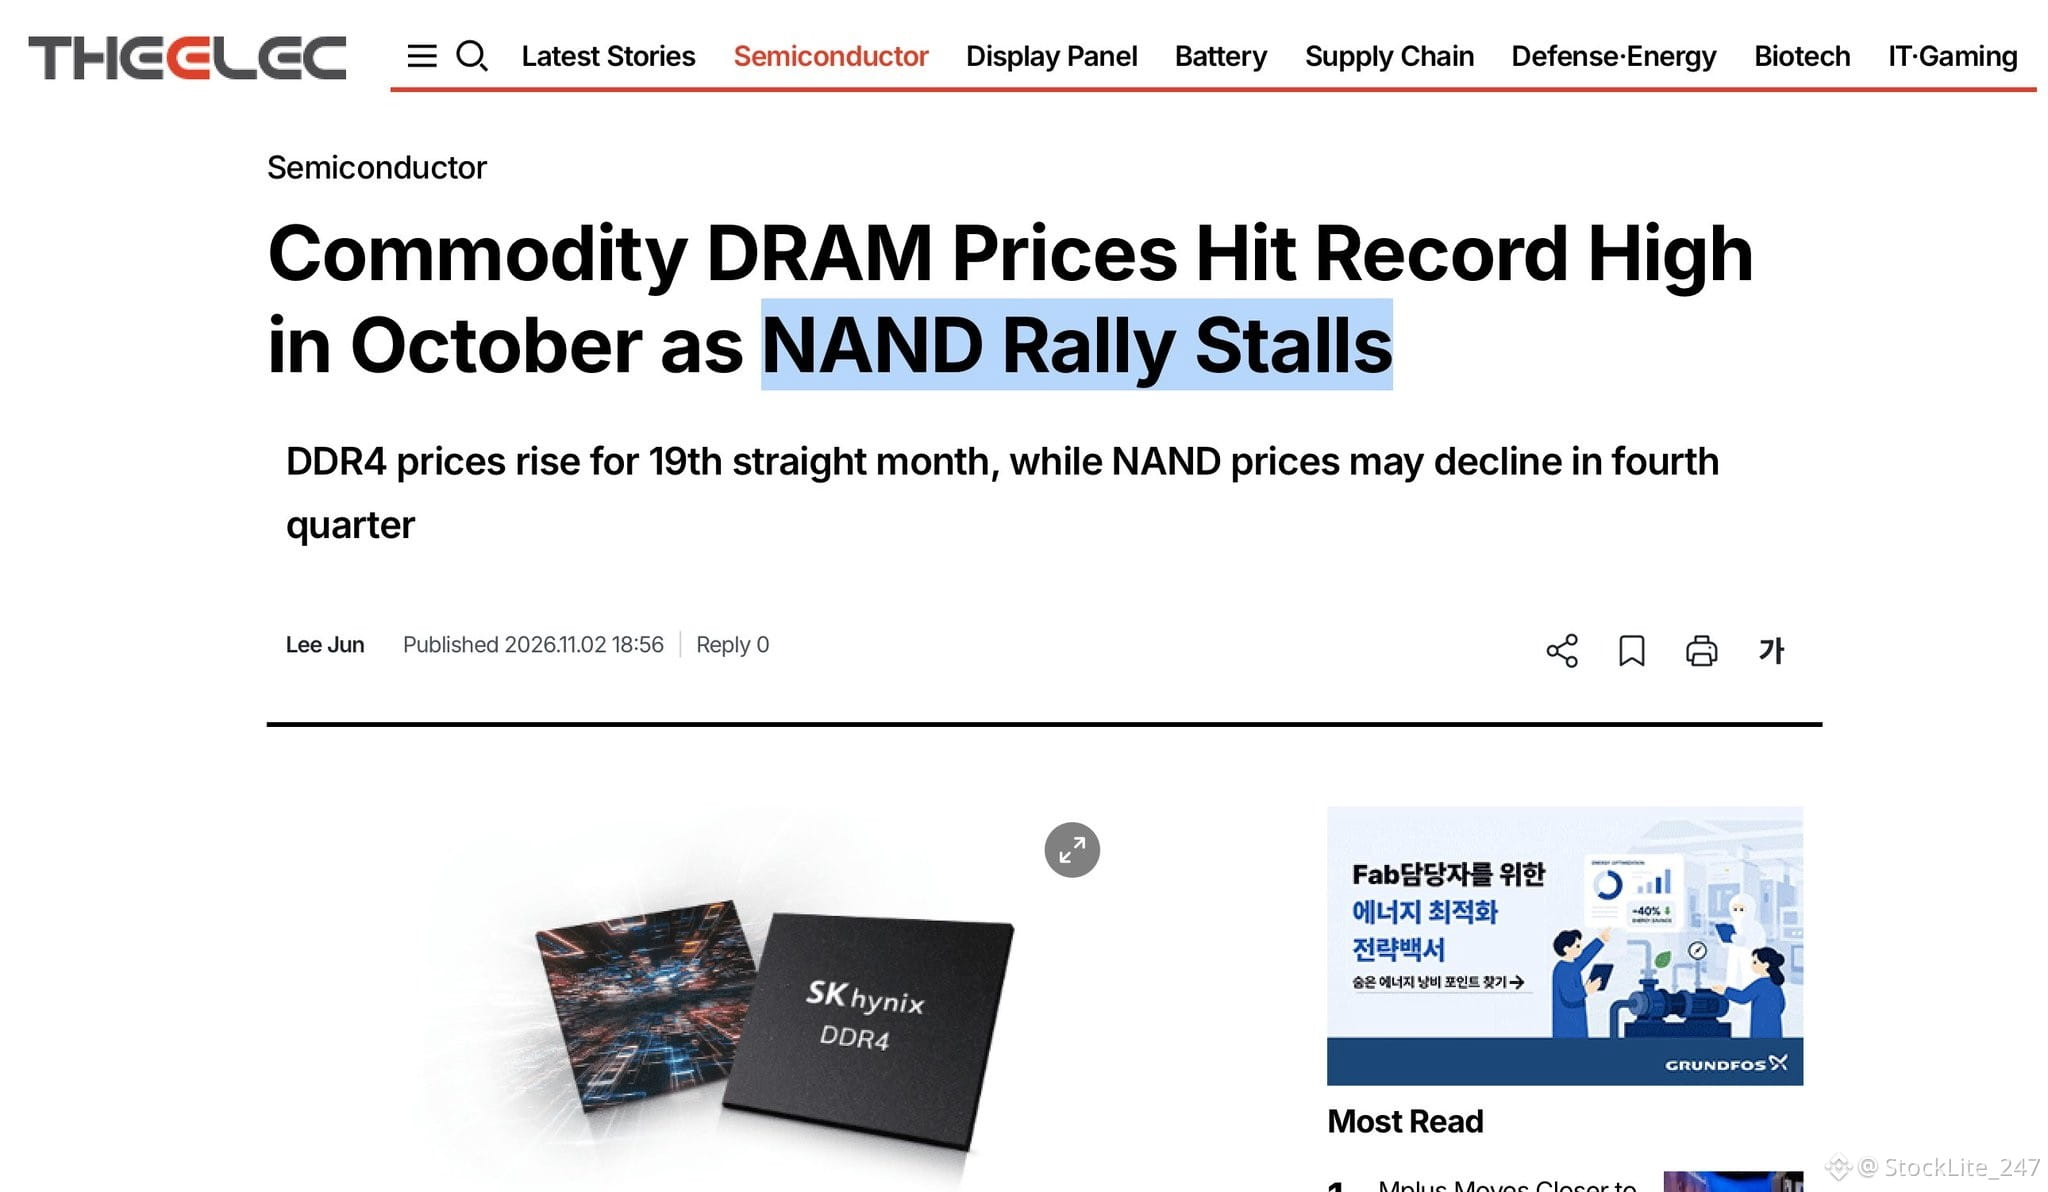
first flat NAND print in ~21 months + the first MoM dip in Korean chip exports, while DRAM keeps rising, points to a DRAM vs NAND split that hits $SNDK before $MU .
What I'm watching is the gap between DRAM-heavy and NAND-heavy names. $MU is mostly DRAM and HBM and guided FQ1 to ~$61.5B. SNDK has no DRAM to lean on.
If NAND rolls over in Q4 while DRAM keeps climbing, those two trades separate.
What I'm watching is the gap between DRAM-heavy and NAND-heavy names. $MU is mostly DRAM and HBM and guided FQ1 to ~$61.5B. SNDK has no DRAM to lean on.
If NAND rolls over in Q4 while DRAM keeps climbing, those two trades separate.