SanDisk is set to grow again next quarter, and high margins aren’t going away yet
In SanDisk’s earnings report, consumer revenue fell 29% quarter over quarter, but it wasn’t enough to slow the company’s overall growth.
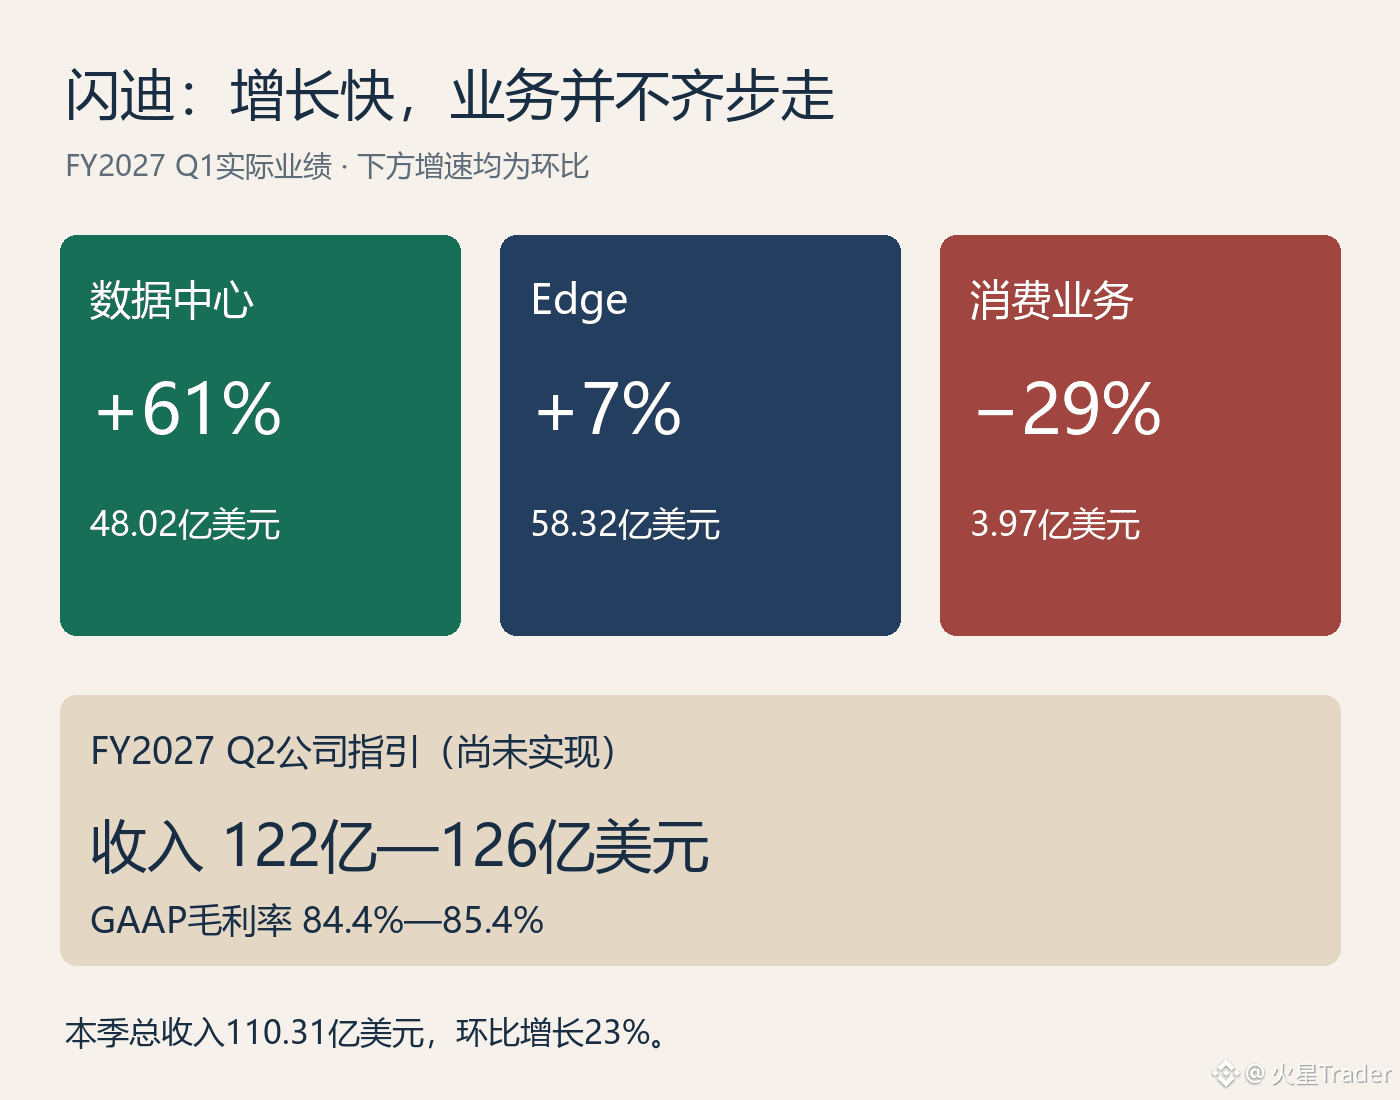
The reason is straightforward: consumer revenue was just $397 million this quarter, while data center revenue had already reached $4.802 billion, up 61% quarter over quarter. Company-wide revenue was $11.031 billion, up 23% from the previous quarter. Focusing only on the decline in consumer revenue means missing the business that’s really driving the results.
The company guided to revenue of $12.2 billion to $12.6 billion next quarter, with a GAAP gross margin of 84.4% to 85.4%. Gross margin was 85% this quarter, and the company did not signal that its high margins are about to fade.
That leaves me still broadly positive on SanDisk’s operating performance. Data center growth has reached scale, and next quarter’s revenue guidance points higher still. Weakness in consumer demand is real, but it’s not yet enough to conclude that SanDisk’s growth is about to turn around.
There was one dip in cash flow: operating cash flow was $6.363 billion this quarter, down from $7.126 billion last quarter. This change needs to be explained over the next few quarters; a one-quarter decline alone isn’t enough to suggest there’s a problem with collections.
The company also announced an eight-for-one stock split, with split-adjusted trading expected to begin on the 20th of next month. A split can change the share price, but not the value of the business. The weight of this earnings report still lies in data center revenue and the high gross margin forecast for next quarter.
In SanDisk’s earnings report, consumer revenue fell 29% quarter over quarter, but it wasn’t enough to slow the company’s overall growth.
The reason is straightforward: consumer revenue was just $397 million this quarter, while data center revenue had already reached $4.802 billion, up 61% quarter over quarter. Company-wide revenue was $11.031 billion, up 23% from the previous quarter. Focusing only on the decline in consumer revenue means missing the business that’s really driving the results.
The company guided to revenue of $12.2 billion to $12.6 billion next quarter, with a GAAP gross margin of 84.4% to 85.4%. Gross margin was 85% this quarter, and the company did not signal that its high margins are about to fade.
That leaves me still broadly positive on SanDisk’s operating performance. Data center growth has reached scale, and next quarter’s revenue guidance points higher still. Weakness in consumer demand is real, but it’s not yet enough to conclude that SanDisk’s growth is about to turn around.
There was one dip in cash flow: operating cash flow was $6.363 billion this quarter, down from $7.126 billion last quarter. This change needs to be explained over the next few quarters; a one-quarter decline alone isn’t enough to suggest there’s a problem with collections.
The company also announced an eight-for-one stock split, with split-adjusted trading expected to begin on the 20th of next month. A split can change the share price, but not the value of the business. The weight of this earnings report still lies in data center revenue and the high gross margin forecast for next quarter.