Amazon’s AWS business is growing strongly, but the group’s cash flow is moving in a different direction.
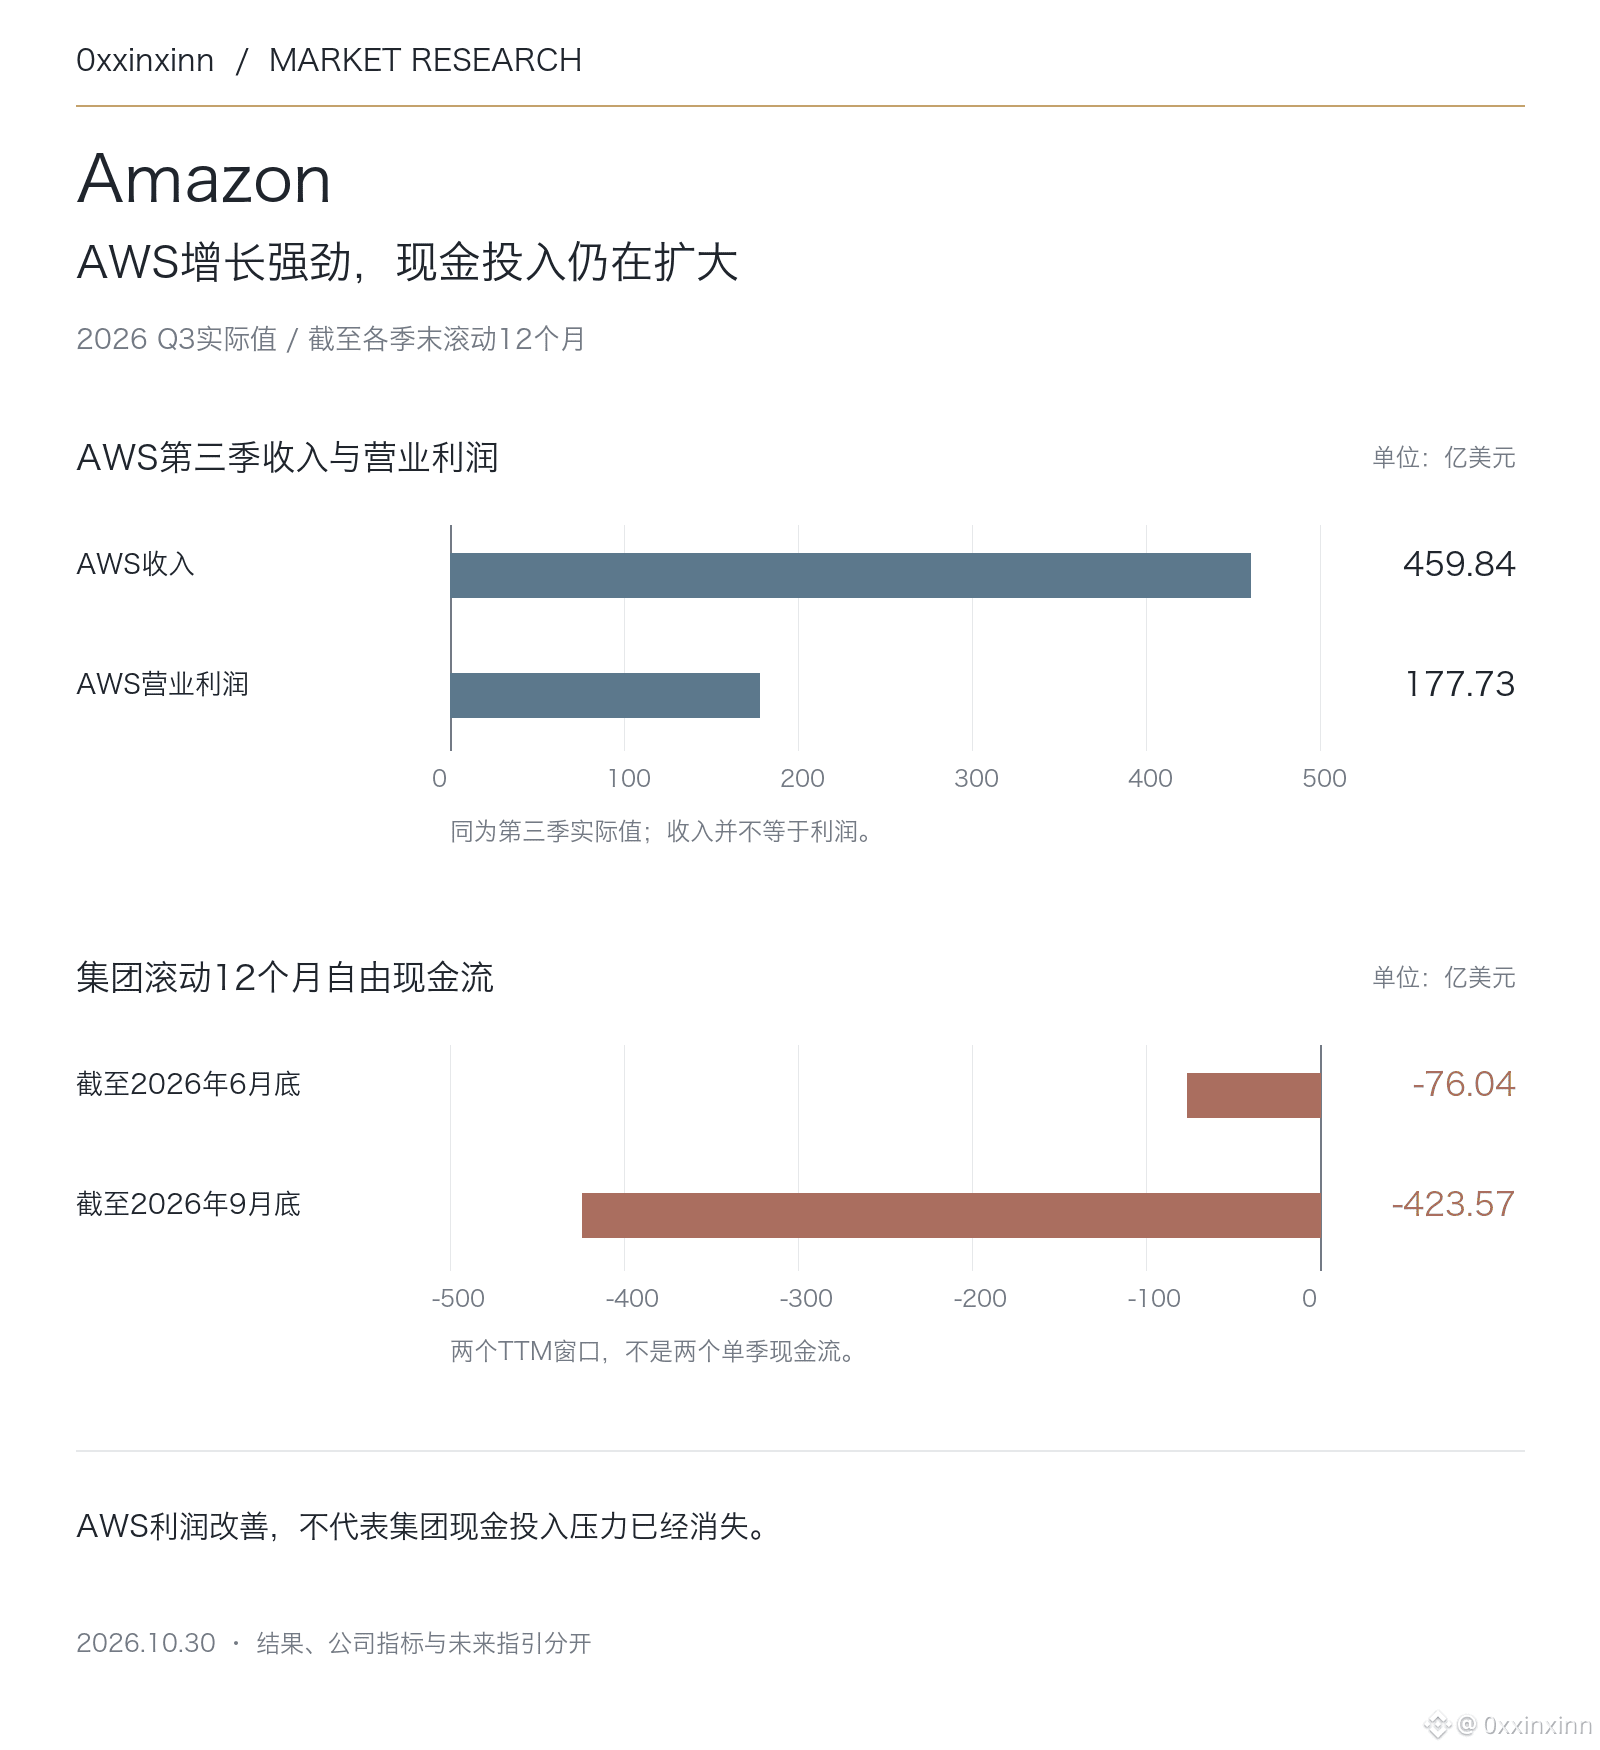
In the third quarter of 2026, AWS revenue was $45.984 billion, up 39.3% year over year, and operating income was $17.773 billion. The group’s operating margin rose to 13.9%, but free cash flow for the trailing 12 months ended September 30 was an outflow of $42.36 billion, a substantial increase from the $7.60 billion outflow for the 12 months ended June 30. These are two trailing 12-month periods—not $42.36 billion burned in the third quarter alone.
Over the same trailing 12 months, operating cash flow was $168.3 billion, while net purchases of property and equipment totaled $210.66 billion. Growth generated cash, but expansion consumed even more. Both figures need to be considered together.
The company still expects cash capital expenditures of about $220 billion in 2026, and forecasts fourth-quarter sales of $240 billion–$247 billion and operating income of $28.5 billion–$33.5 billion. These are forecasts, not actual results.
The year-over-year decline in net income was also affected by investment gains from Anthropic that boosted the year-ago comparison, so it cannot simply be attributed to a deterioration in the core business. The key going forward is whether AWS delivery and profit growth can gradually cover equipment investment—not just using cloud growth rates to explain the valuation.
In the third quarter of 2026, AWS revenue was $45.984 billion, up 39.3% year over year, and operating income was $17.773 billion. The group’s operating margin rose to 13.9%, but free cash flow for the trailing 12 months ended September 30 was an outflow of $42.36 billion, a substantial increase from the $7.60 billion outflow for the 12 months ended June 30. These are two trailing 12-month periods—not $42.36 billion burned in the third quarter alone.
Over the same trailing 12 months, operating cash flow was $168.3 billion, while net purchases of property and equipment totaled $210.66 billion. Growth generated cash, but expansion consumed even more. Both figures need to be considered together.
The company still expects cash capital expenditures of about $220 billion in 2026, and forecasts fourth-quarter sales of $240 billion–$247 billion and operating income of $28.5 billion–$33.5 billion. These are forecasts, not actual results.
The year-over-year decline in net income was also affected by investment gains from Anthropic that boosted the year-ago comparison, so it cannot simply be attributed to a deterioration in the core business. The key going forward is whether AWS delivery and profit growth can gradually cover equipment investment—not just using cloud growth rates to explain the valuation.