【October 28 | Global Market News and Data Analysis】
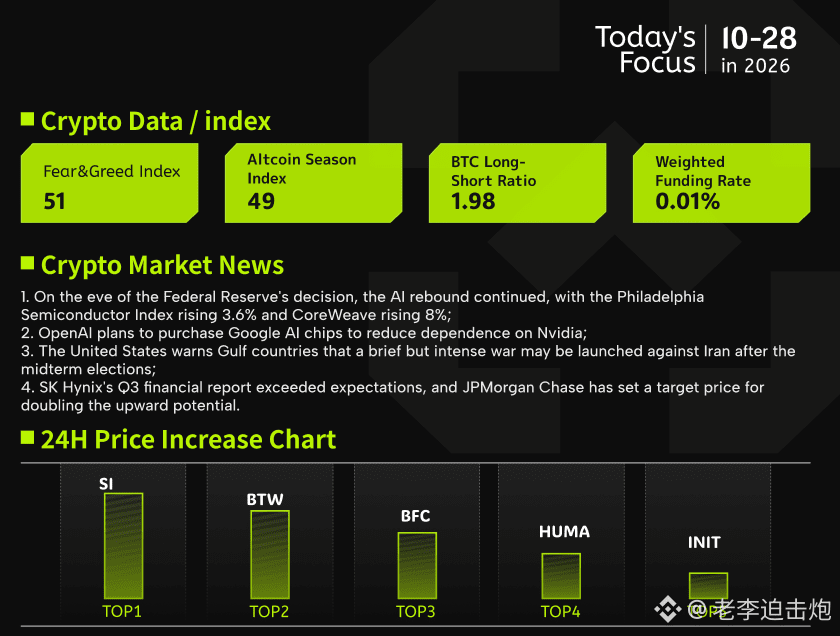
1. On the eve of the Fed decision, the AI rebound continued: the Philadelphia Semiconductor Index rose 3.6%, and CoreWeave gained 8%;
2. OpenAI plans to buy Google AI chips to reduce its dependence on Nvidia;
3. The U.S. warned Gulf states that it could launch a brief but intense war against Iran after the midterm elections;
4. SK Hynix's Q3 results beat expectations, and JPMorgan set a price target implying a potential doubling.
U.S. stocks extended their gains, with AI-related sectors providing the main lift. The semiconductor industry rose particularly sharply, while emerging cloud service providers and optical communications and memory stocks broadly advanced. Improved financing conditions were a key catalyst behind the rally: Broadcom finalized a major financing arrangement with several institutions to purchase AI accelerator equipment and lease it to Anthropic; Oracle expanded its cloud partnership with OpenAI; and Meta's new share offering was oversubscribed. Goldman Sachs attributed the rebound to easing financing concerns and improving earnings expectations. Attention now turns to the Fed's rate decision and earnings reports from major technology companies. Rates are widely expected to remain unchanged, although expectations of a rate hike by year-end remain elevated. Oil prices fell amid hopes of easing tensions in the Middle East, while U.S. Treasury yields and the dollar index remained high.
The crypto market presented a different picture. On-chain data shows that buying support for Bitcoin remains weak, with demand indicators staying negative. The price gap between U.S. and overseas platforms also points to a lack of domestic buying power, while the paper profits of short-term holders have narrowed significantly. However, the overall score remains in neutral-to-positive territory, with most underlying indicators still bullish. Current conditions look more like a cooldown during an uptrend than a trend reversal. For BTC, a dovish Fed stance this week and continued strong earnings could improve risk appetite and encourage funds to flow back into crypto assets. Conversely, continued strength in the dollar and interest rates would further constrain its upside, and it may remain range-bound in the near term.
1. On the eve of the Fed decision, the AI rebound continued: the Philadelphia Semiconductor Index rose 3.6%, and CoreWeave gained 8%;
2. OpenAI plans to buy Google AI chips to reduce its dependence on Nvidia;
3. The U.S. warned Gulf states that it could launch a brief but intense war against Iran after the midterm elections;
4. SK Hynix's Q3 results beat expectations, and JPMorgan set a price target implying a potential doubling.
U.S. stocks extended their gains, with AI-related sectors providing the main lift. The semiconductor industry rose particularly sharply, while emerging cloud service providers and optical communications and memory stocks broadly advanced. Improved financing conditions were a key catalyst behind the rally: Broadcom finalized a major financing arrangement with several institutions to purchase AI accelerator equipment and lease it to Anthropic; Oracle expanded its cloud partnership with OpenAI; and Meta's new share offering was oversubscribed. Goldman Sachs attributed the rebound to easing financing concerns and improving earnings expectations. Attention now turns to the Fed's rate decision and earnings reports from major technology companies. Rates are widely expected to remain unchanged, although expectations of a rate hike by year-end remain elevated. Oil prices fell amid hopes of easing tensions in the Middle East, while U.S. Treasury yields and the dollar index remained high.
The crypto market presented a different picture. On-chain data shows that buying support for Bitcoin remains weak, with demand indicators staying negative. The price gap between U.S. and overseas platforms also points to a lack of domestic buying power, while the paper profits of short-term holders have narrowed significantly. However, the overall score remains in neutral-to-positive territory, with most underlying indicators still bullish. Current conditions look more like a cooldown during an uptrend than a trend reversal. For BTC, a dovish Fed stance this week and continued strong earnings could improve risk appetite and encourage funds to flow back into crypto assets. Conversely, continued strength in the dollar and interest rates would further constrain its upside, and it may remain range-bound in the near term.