【U.S. Earnings Preview · Google】
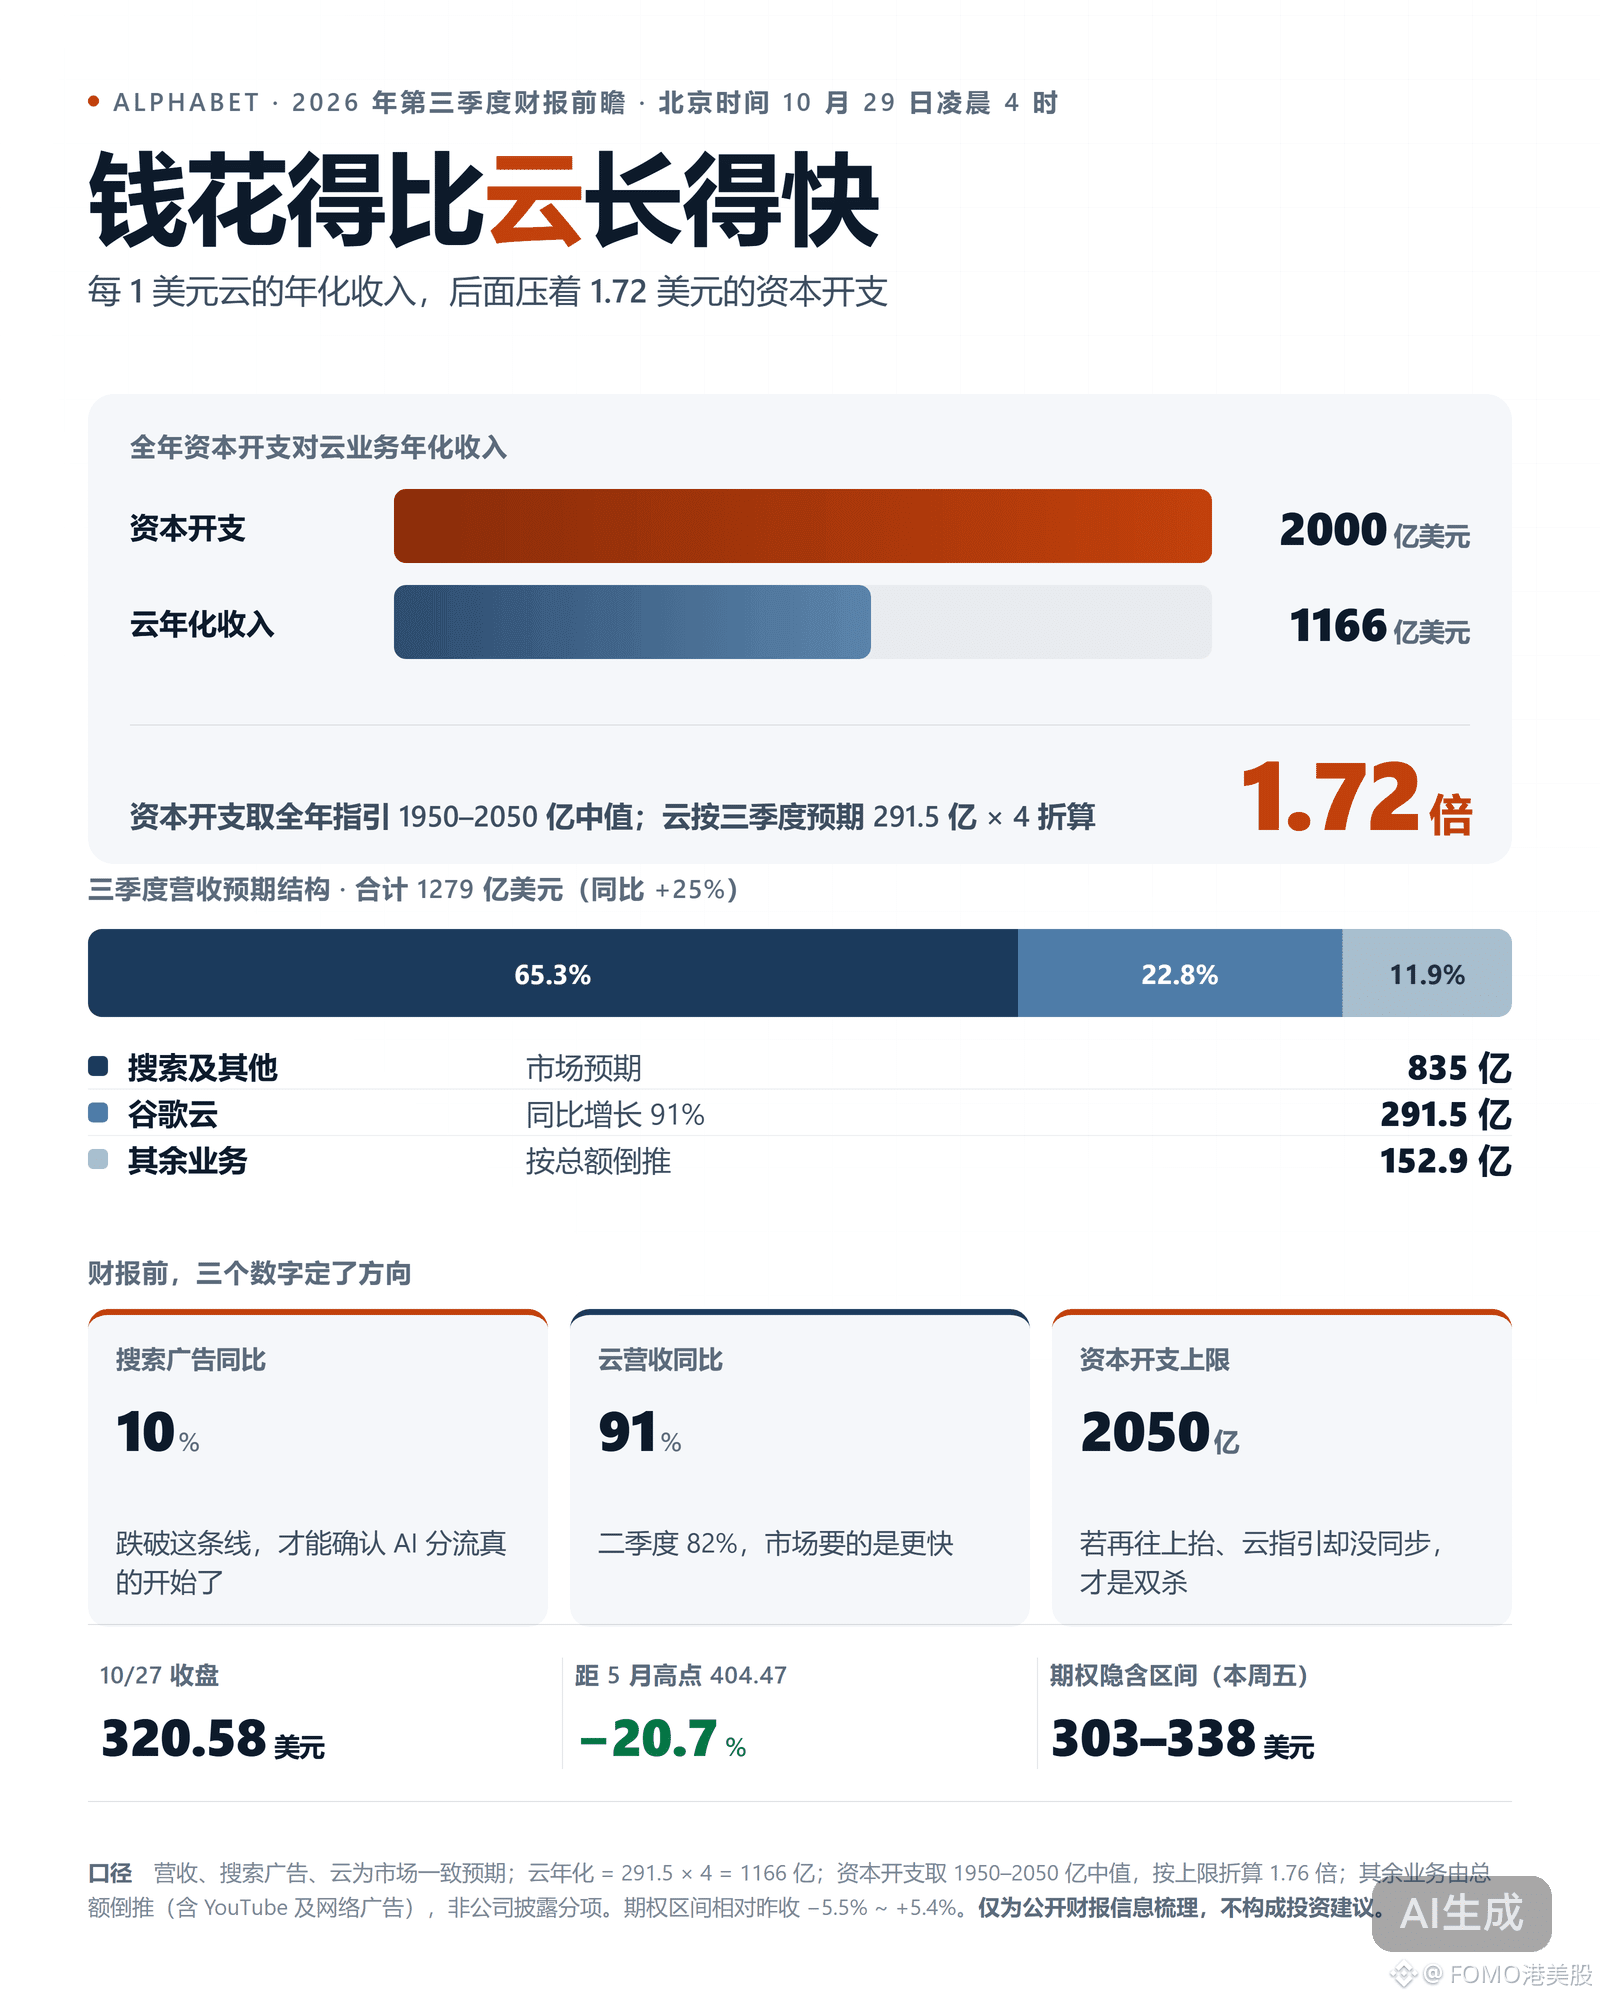
Alphabet $GOOGLB reports Q3 earnings after market close tonight (4 a.m. Beijing time on the 29th). It closed yesterday at $320.58. The market expects revenue of $127.9 billion (up 25% year over year), EPS of $2.96 to $3.01, and cloud revenue of $29.15 billion (up 91% year over year).
Options pricing implies a share-price move of about 6% by this Friday, putting the range at $303 to $338. The stock is still 21% below its May high of $404 and is up just 2% year to date. But Google’s core business isn’t cloud. Search ad revenue is expected to reach $83.5 billion, or 65% of total revenue, while cloud revenue of $29.15 billion accounts for just 23%. Cloud’s year-over-year growth is accelerating from 82% to 91%, so demand is indeed real; but growth in network ad impressions fell to 12% in Q2, and the first signs of traffic diversion have emerged.
The financial pressure is coming from another direction. Full-year capex guidance is $195 billion to $205 billion, with a midpoint of $200 billion—1.72 times cloud’s annualized revenue of $116.6 billion.
Ahead of earnings, I’m not guessing which way the stock will move. I’m watching just two numbers: if search ad growth falls below 10% year over year, it means traffic diversion is truly underway; if the capex ceiling rises above $205 billion while cloud guidance isn’t raised in tandem, that’s when the double hit comes.
It’s better to wait for those two numbers before adjusting positions than to guess the direction now.
#谷歌财报能否守住基本盘 #BStocks #股票财报季