📅 On October 29, Amazon will publish its financial results for the third quarter of 2026. My prediction for Binance Pick: YES — Amazon has a chance to exceed market expectations, primarily thanks to its AWS cloud business and AI development.
📊 What are analysts expecting?
According to MarketBeat’s consensus forecast:
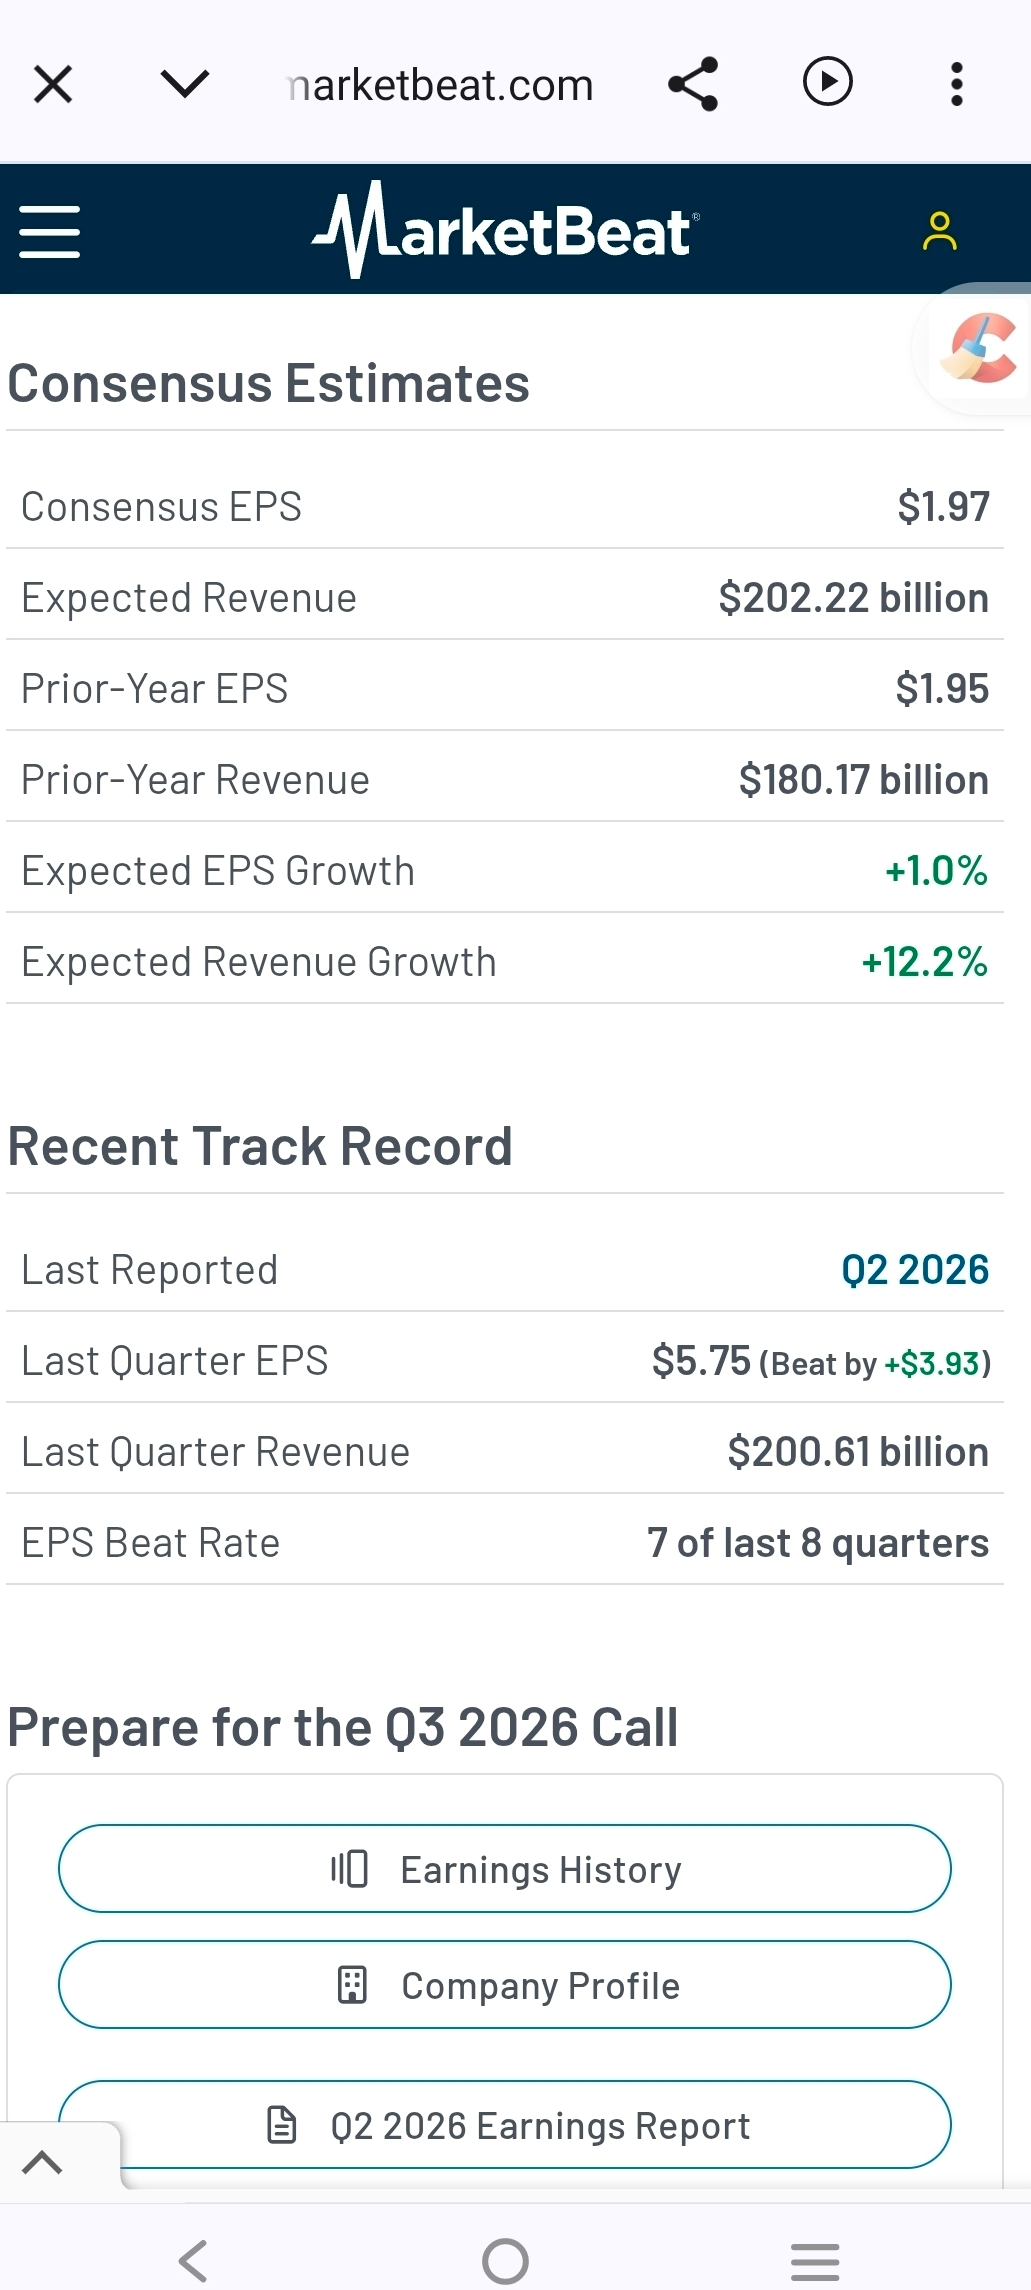
▪️ Revenue — around $202.22 billion, up 12.2% year over year.
▪️ Earnings per share (EPS) — about $1.97 versus $1.95 a year earlier, an increase of approximately 1%.
▪️ According to MarketBeat, Amazon beat EPS expectations in 7 of the last 8 quarters.
But the main question is not just total revenue, but also how much profit Amazon can generate from the expansion of cloud computing and AI infrastructure.
☁️ AWS — the strongest candidate to beat forecasts
In Q2 2026, AWS revenue grew 37% year over year to $42.2 billion. That was its fastest growth in 18 quarters.
There are other important signals too:
▪️ AWS’s AI business exceeded $25 billion in annualized revenue.
▪️ Amazon’s proprietary chip business also exceeded $25 billion in annualized revenue.
▪️ The advertising business grew 26% year over year.
Amazon is no longer just an online store: it is developing cloud services, AI, proprietary chips, and digital advertising all at once. AWS could be one of the key drivers of a potential earnings beat.
⚠️ What could go wrong?
Investments in data centers and computing capacity require enormous amounts of capital. Over the 12 months through the end of June, Amazon’s free cash flow was negative — about $7.6 billion — largely due to increased capital expenditures.
In addition, Q2 net income included significant non-operating investment income, primarily from Anthropic. So the quarter’s EPS of $5.75 should not be viewed as a normal level of business profitability.
So what matters is not only how much Amazon earns, but also whether its massive AI investments pay off.
📈 My outlook for the stock
🟢 Bullish scenario: AWS grows faster than expected, cloud business profitability improves, and management issues strong Q4 guidance. This could support the stock.
🔴 Bearish scenario: AI spending weighs on cash flow, while cloud business growth fails to meet investor expectations. Even beating forecasts may not be enough to lift the share price.
💭 My conclusion: I choose “YES” for Binance Pick. AWS, proprietary chips, and advertising create the conditions for strong results. However, the market’s short-term reaction will also depend on margins, cash flow, and management’s guidance.
What do you expect from Amazon: a fresh growth catalyst or pressure from AI spending?
This is my view of the market, not financial advice.
#EarningsSeason #BinancePick #AMZN #AMZNB #Amazon