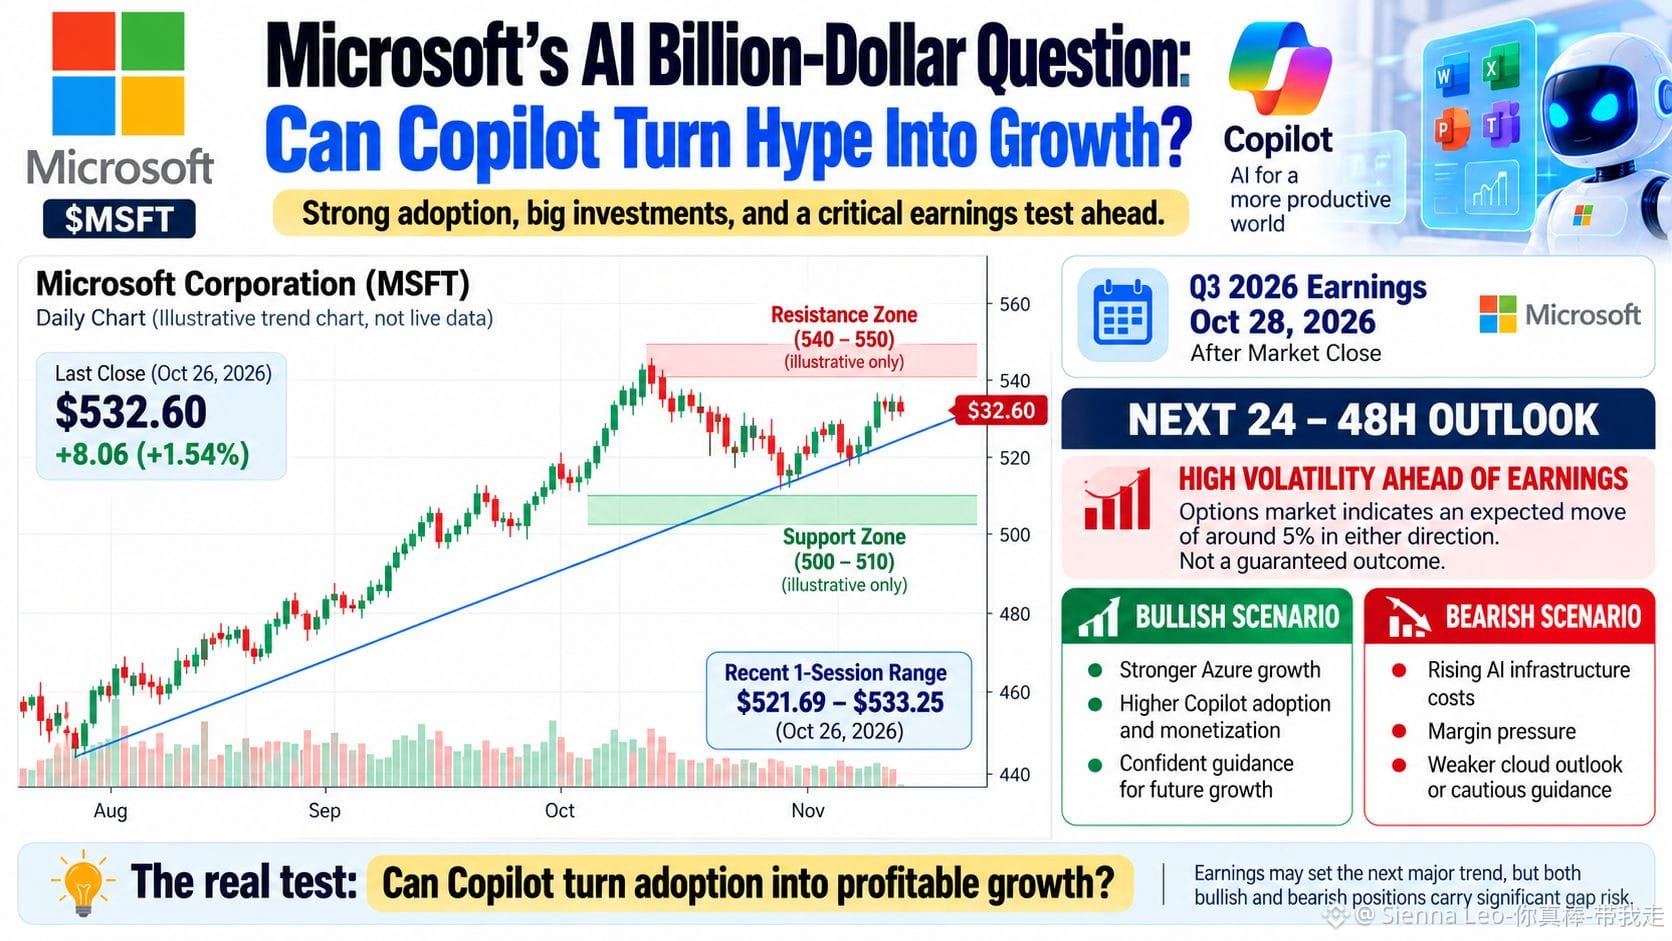
Microsoft's AI Billion-Dollar Question: Can Copilot Turn Hype Into Growth? 🤖
The future belongs not to the company with the smartest AI, but to the one that makes it indispensable.
Microsoft is approaching a critical test: can Copilot turn AI excitement into recurring revenue?
The Evidence: In July 2026, Microsoft reported $90 billion in quarterly revenue, up 18% year over year. Microsoft 365 Copilot had surpassed 30 million paid seats, while Azure revenue grew 43%. These are meaningful signs of demand, but adoption alone does not guarantee attractive returns.
The real question is whether businesses will keep paying for AI tools that deliver measurable productivity gains.
What the Market May Be Missing
AI infrastructure requires enormous investment. If Copilot increases customer spending, strengthens Microsoft's ecosystem, and improves productivity, those investments could pay off. If monetization fails to keep pace with computing costs, margins could face pressure.
MSFT Price: The latest reliably retrieved quote was $521.20, dated October 22, 2026, at 3:06 p.m. ET. A verified live price is unavailable here.
Prediction | Next 24–48 Hours: Microsoft's October 28 earnings are the major catalyst. Strong Azure growth, Copilot adoption, and confident guidance could support bullish momentum. Disappointing cloud growth, weak monetization, or higher-than-expected AI spending could trigger a pullback. Options markets indicate an expected move of approximately 5% in either direction, not a guarantee.
Short-term traders may find opportunities around earnings, but both bullish and bearish positions carry substantial gap risk.
The bottom line: AI hype attracts attention. Profitable adoption creates lasting value.
Will Copilot become Microsoft's next growth engine, or will its costs outrun its commercial rewards?
For educational purposes only. Not financial advice.
#GrowWithSAC #EarningsSeason #BinancePick $MSFT
$MSFTB
#CanGoogleDefindItsCore #CanMicrosoftDeliverOnAI