
Daily Futures Order Book | 10/27: Open Interest Rises as Selling Pressures Prices
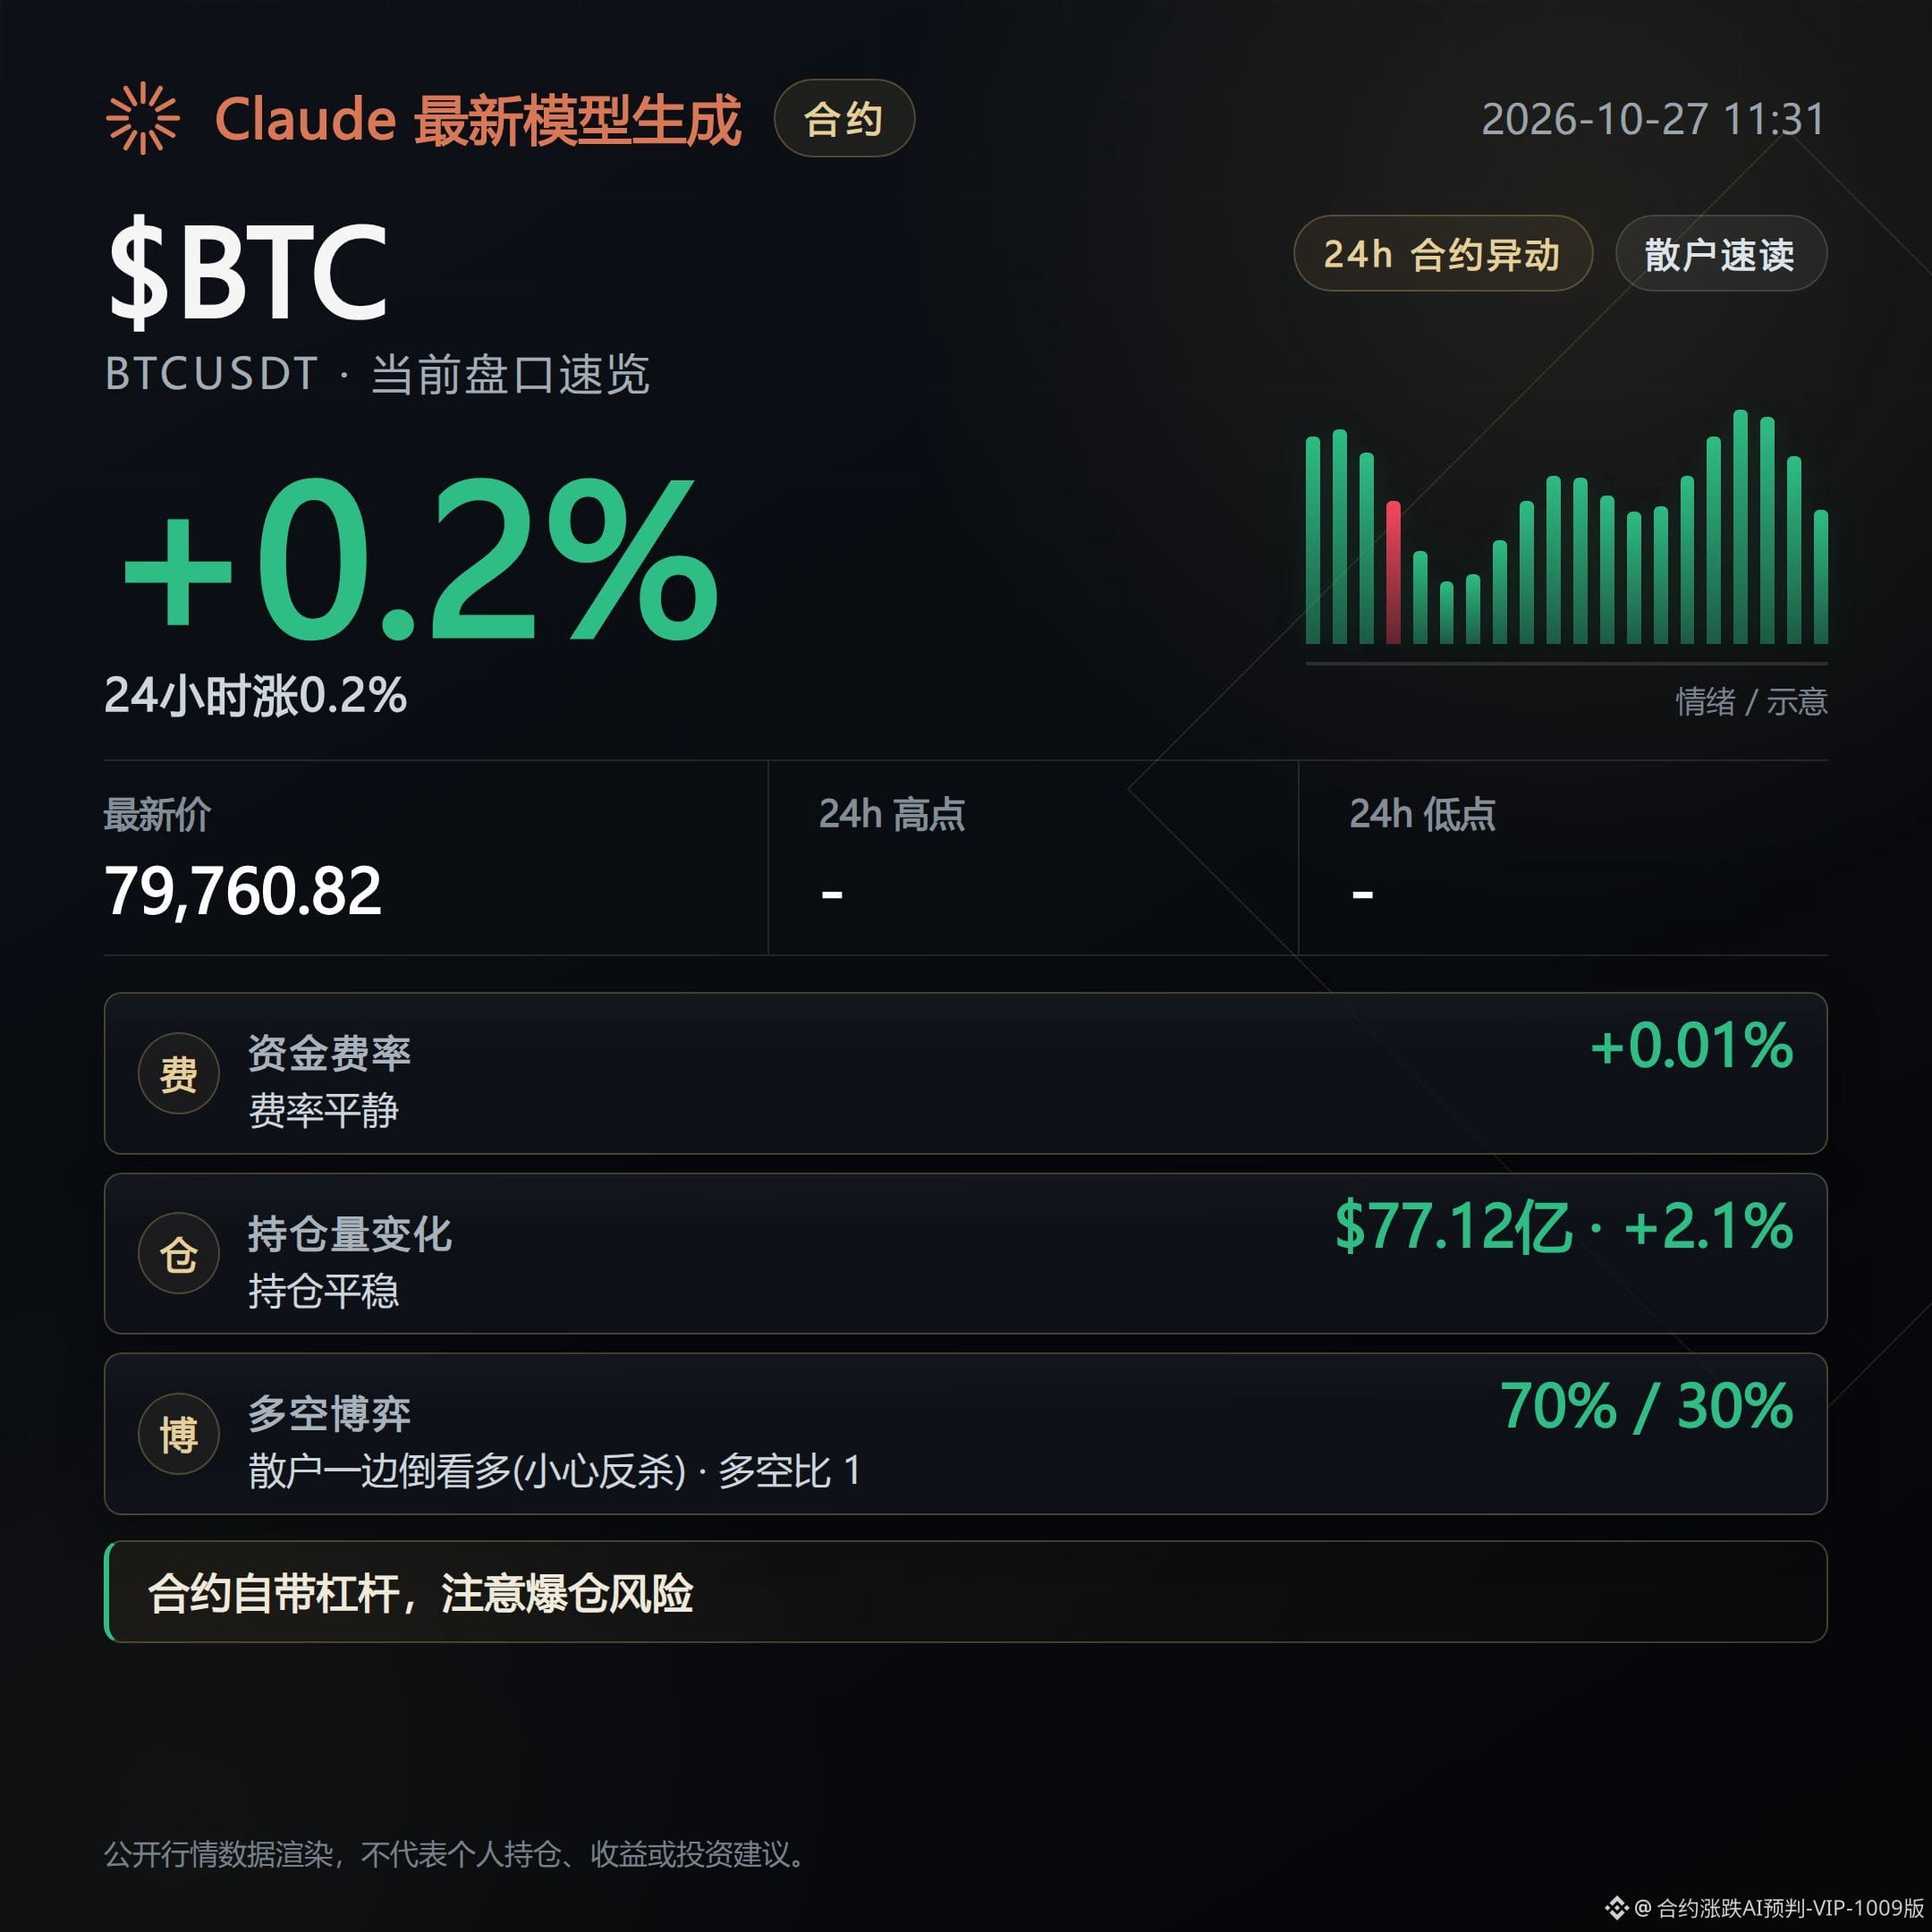
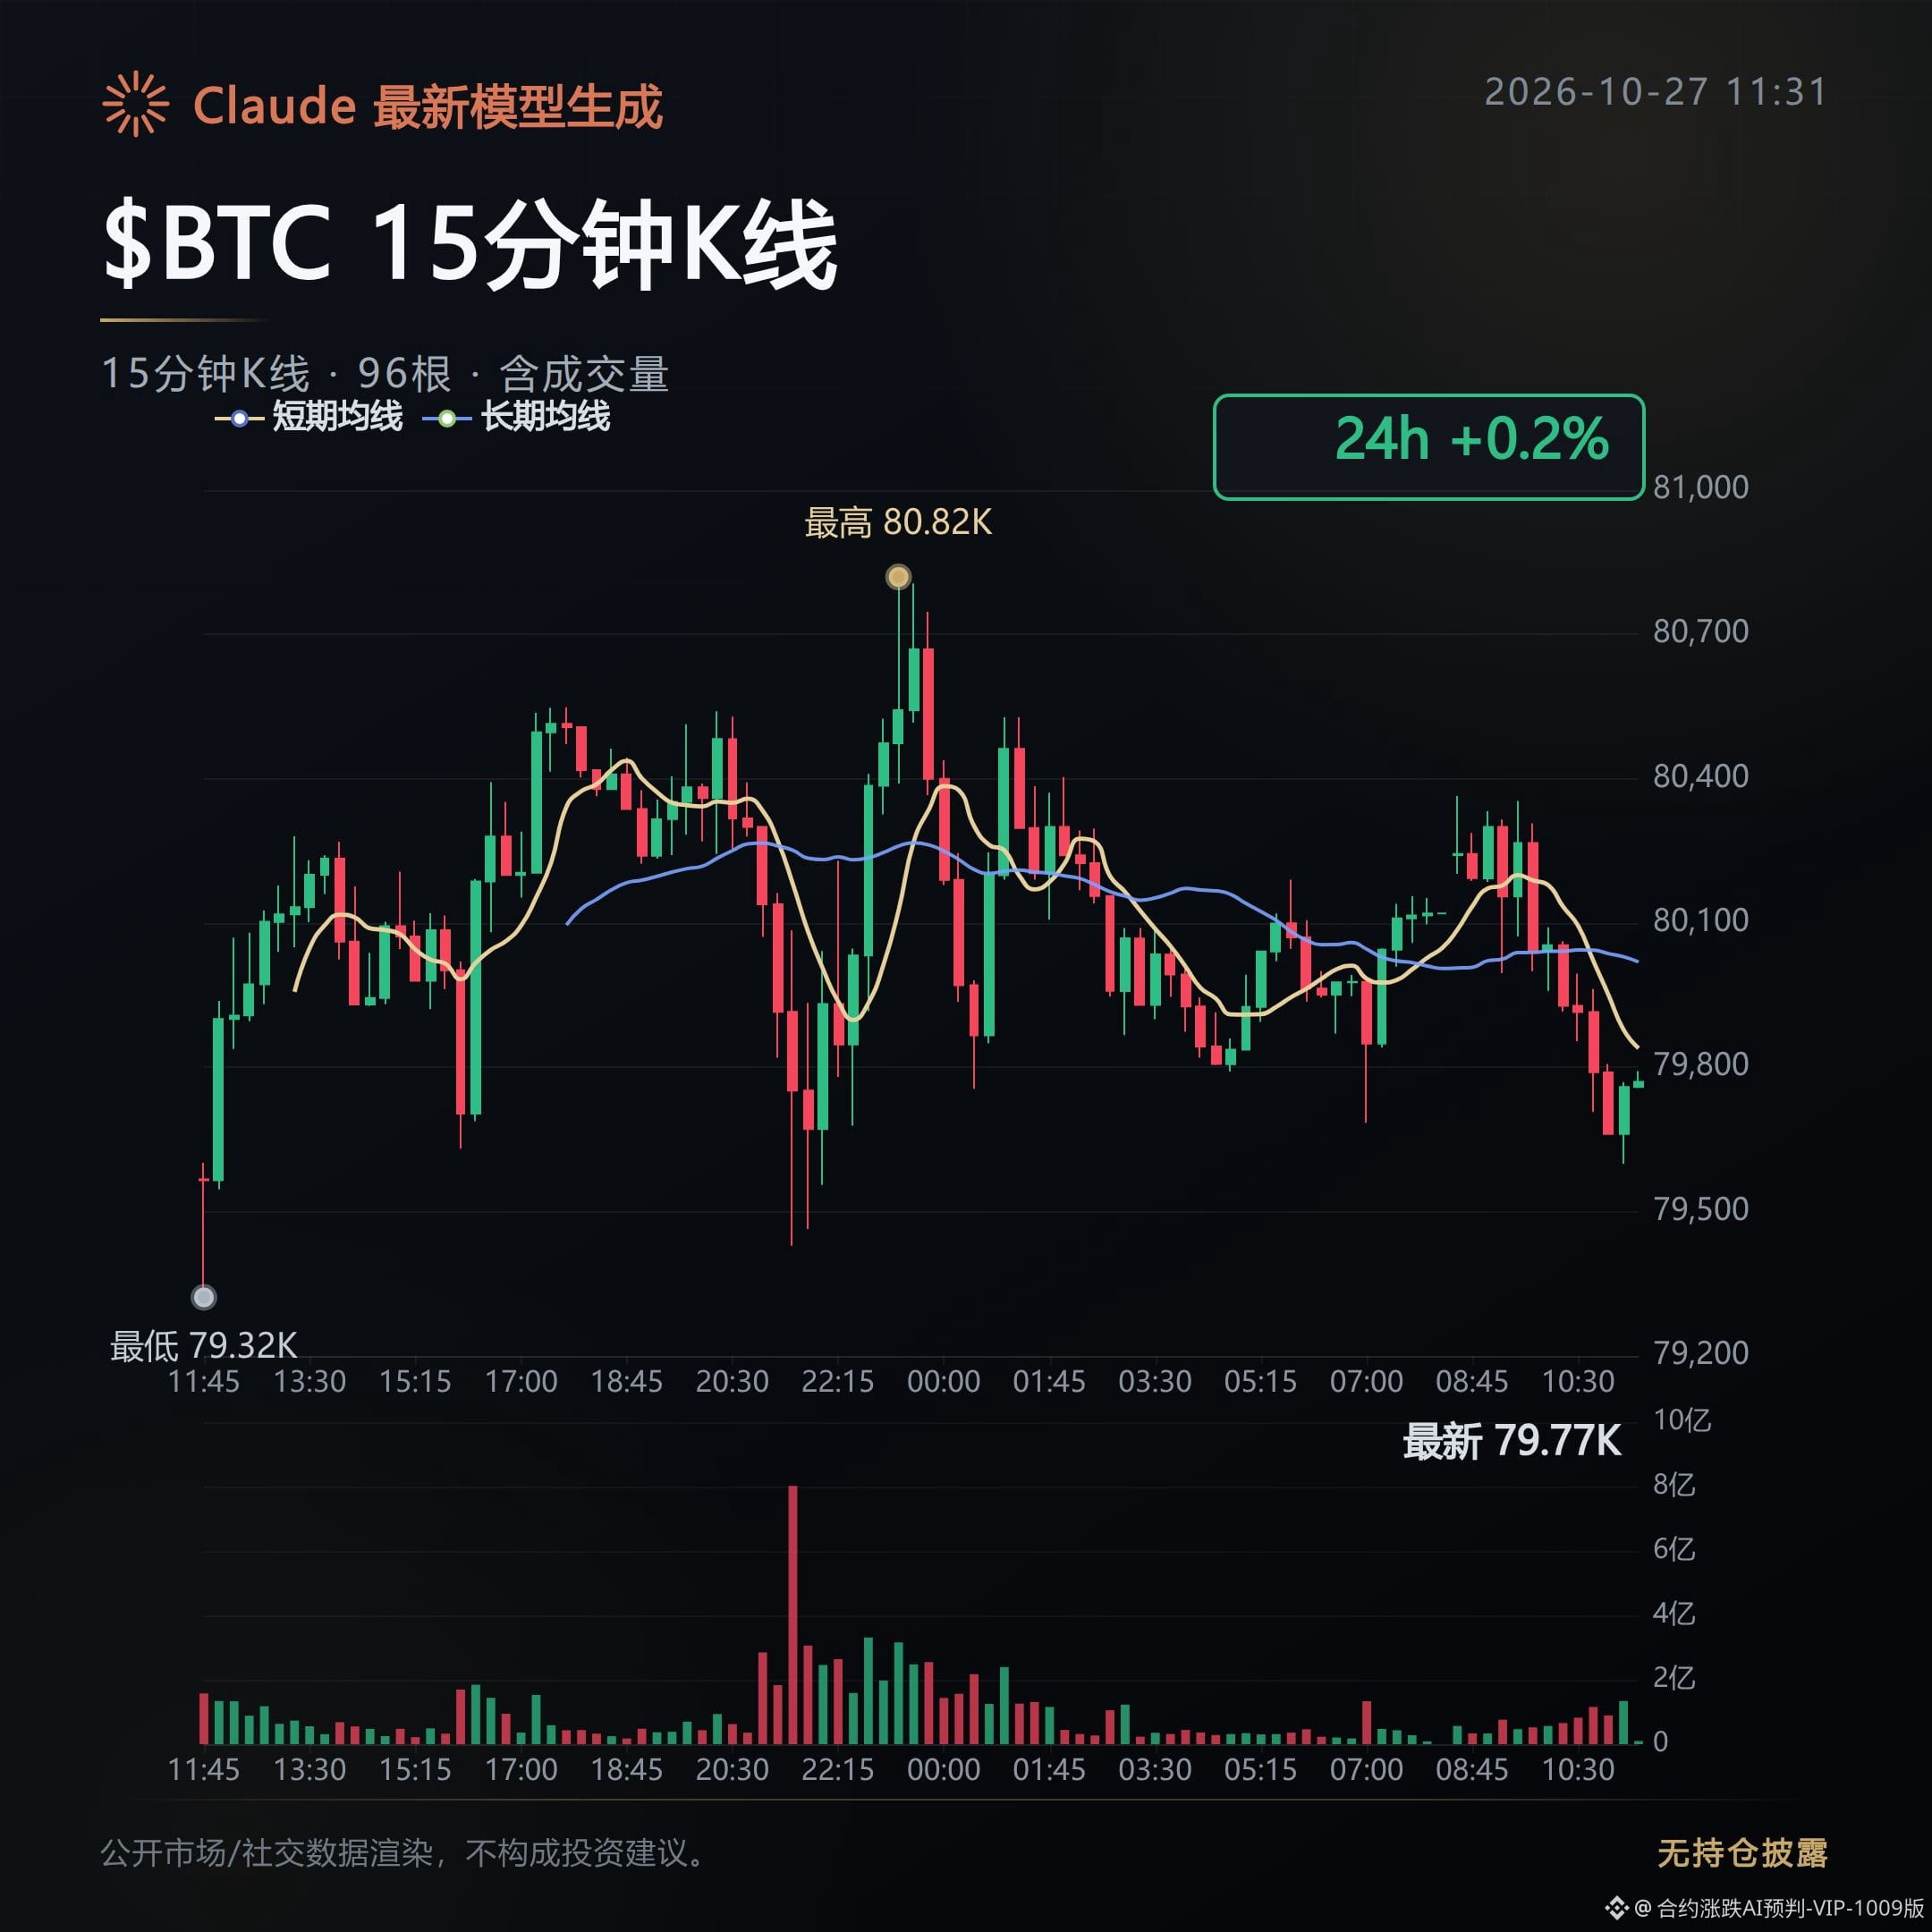
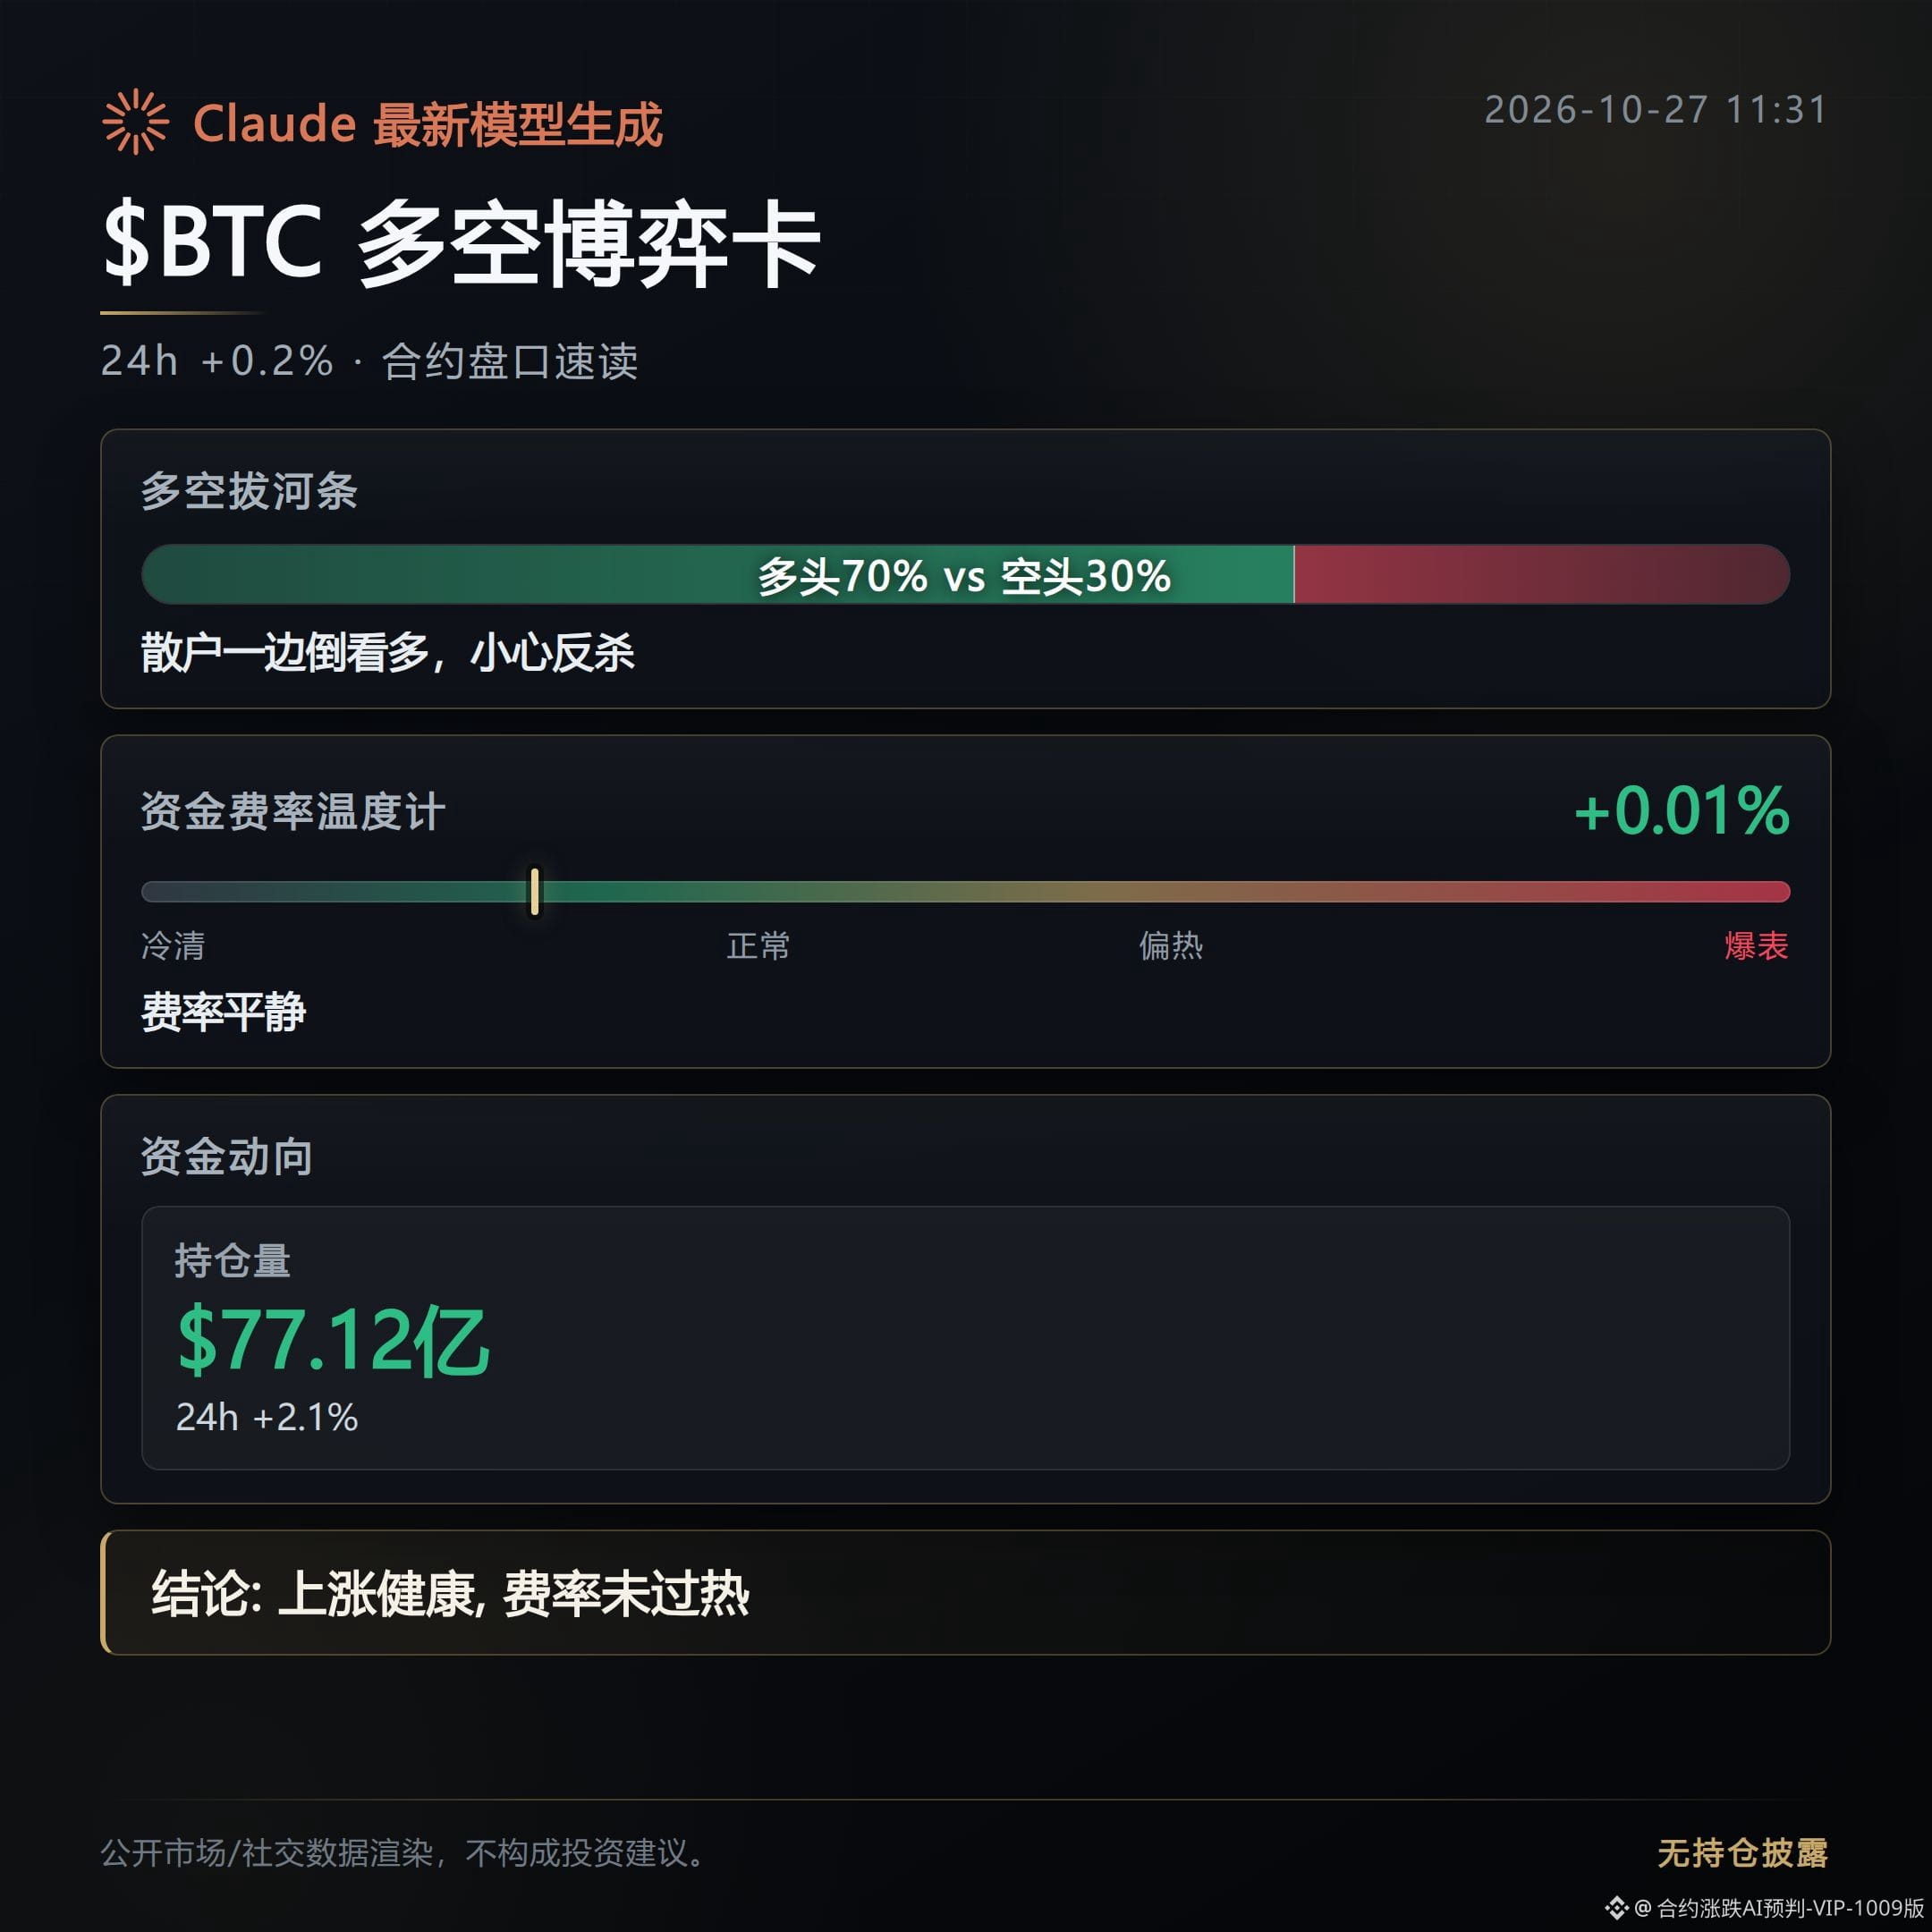
The most unusual midday development was that $BTC was priced at $79,760.82, up just 0.17%, while futures open interest rose 2.1% to $7.712 billion.
Long positions accounted for 70%, but the taker buy/sell ratio was only 0.75—equivalent to just 75 units of aggressive buying for every 100 units of aggressive selling.
This points to leveraged longs building up, without a corresponding increase in actual buying demand.
Funding rates across major futures contracts were all positive, indicating that longs are still paying to maintain their positions. But the Fear and Greed Index was only 48, suggesting spot market sentiment is far from exuberant.
Funding rates among smaller tokens were even more extreme: $UNITREE was at -0.835%, indicating an overcrowded short position, while $BWET was at +0.367%, suggesting elevated long-side crowding.
Extreme funding rates are not directional signals; they are fuel for liquidations on either side.
There are two catalysts on the payments front: the U.S. Office of the Comptroller of the Currency is encouraging community banks to issue payment stablecoins, and Ripple has received final approval for a U.S. national trust bank.
This could raise expectations for compliant stablecoins and payment rails, but in the near term, it is not enough to reverse the dominance of aggressive selling in the $BTC order book.
Security is a headwind: the keys Keystone uses to verify the authenticity of hardware wallets were stolen, further increasing trust risks around self-custody devices.
The risk boundary is $80,000: reclaiming that level is not enough on its own—the taker buy/sell ratio needs to rise above 1. If open interest keeps increasing while the ratio remains below 1, crowded longs could turn into liquidation pressure first.
This content was generated with assistance from Claude Fable 5 and is for informational purposes only. Please verify it independently.