For Celestica’s earnings report this time, I’ll look at margins first, then whether revenue can continue to scale.
CLS will report its third-quarter results after the market closes in the U.S. on October 26, which is early October 27 Beijing time. The earnings call won’t take place until 20:00 on October 27, so don’t confuse the two times.
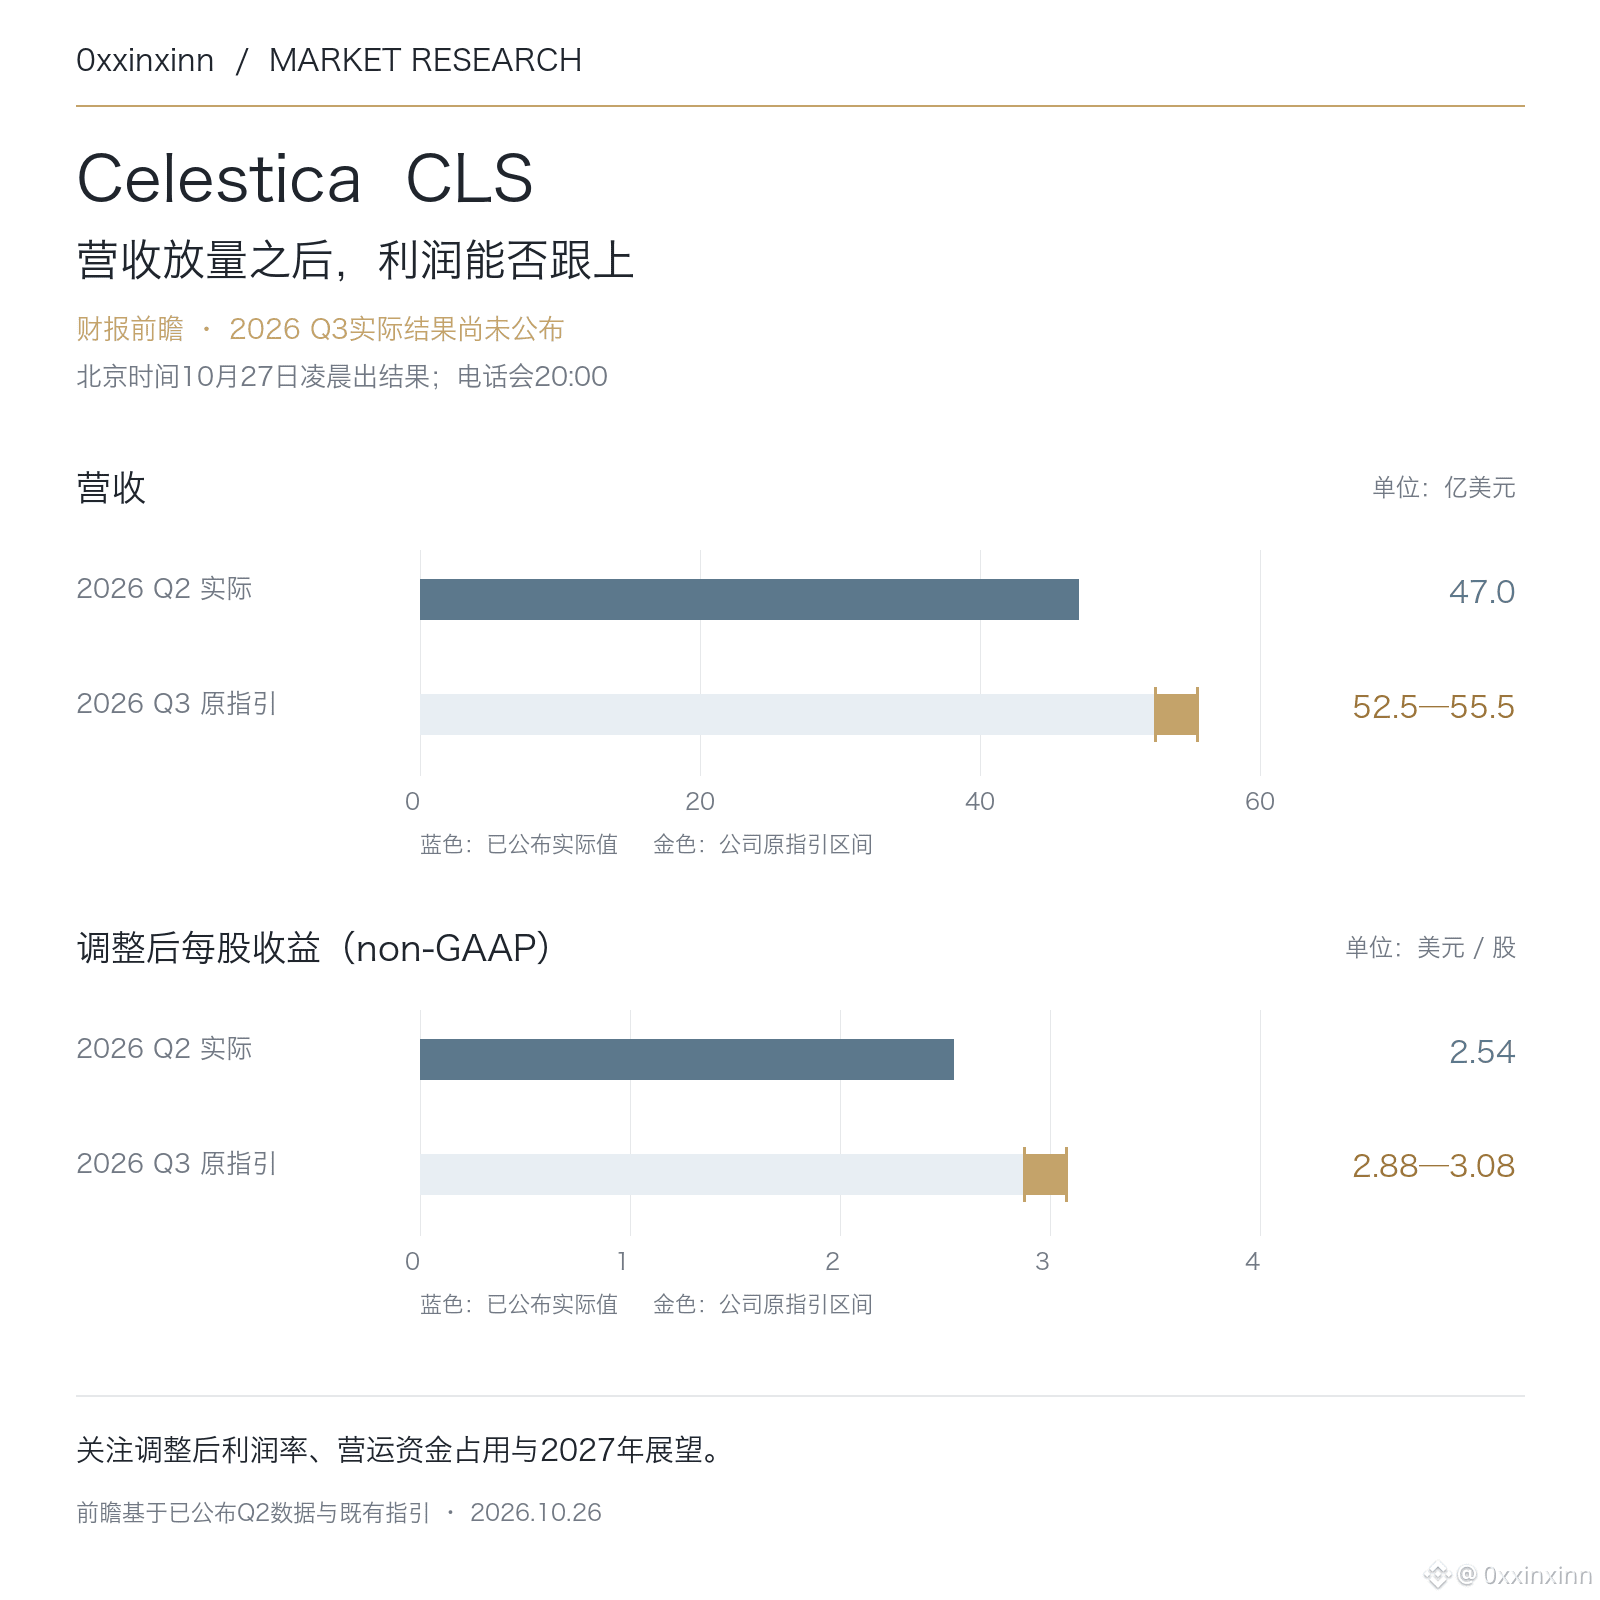
The company reported second-quarter revenue of $4.7 billion, up 62% year over year, and adjusted earnings per share of $2.54. Its original third-quarter guidance was revenue of $5.25 billion–$5.55 billion and adjusted earnings per share of $2.88–$3.08. The latter is on a non-GAAP basis, and none of this guidance has yet become actual results.
Margins are more worth watching than the revenue range: the adjusted operating margin was 8.2% in the second quarter, while the midpoint of the original third-quarter guidance was 8.4%. If revenue grows but margins don’t keep pace, it’s worth looking into customer mix, costs, and delivery timing—not jumping to conclusions just because of AI orders.
The company also previously forecast that revenue growth in 2027 would exceed its expected 65% growth in 2026, so whether it can maintain this outlook is also key. I’ll be watching for any improvement to the original guidance in the new results, and whether inventory, accounts receivable, and cash flow can support a larger business.