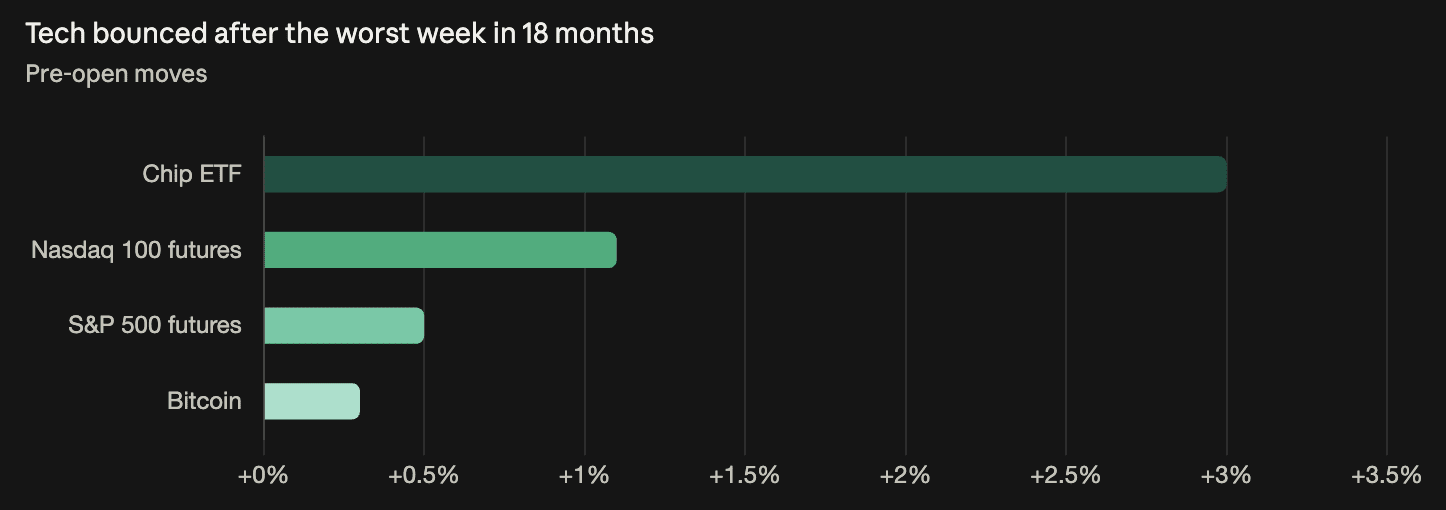
Bitcoin traded at $82,000-$83,000 Monday — rejected at $84,000 for a third time, floor defended at $80,700 for a fourth — as Nasdaq futures rebounded 1%+ after last week’s 5.5% selloff. The bounce barely registered in crypto: Bitcoin +0.3%, against a 3% chipmaker ETF gain. China’s Q3 GDP at 4.5% (vs 4.3% prior) and easing oil prices drove Asia’s recovery; the KOSPI reversed a 3.17% opening drop to close +1.76%. Altcoin Season index at 56, down from a 2026 record of 63 — the index requires 75 to qualify, meaning 2026 has never produced an actual altcoin season. This week’s tech earnings (Meta, Tesla, then Alphabet, Microsoft, Apple) settle the AI capex question that drove last week’s damage.
U.S. Storage Shares Open Higher as Nasdaq Gains 0.9%
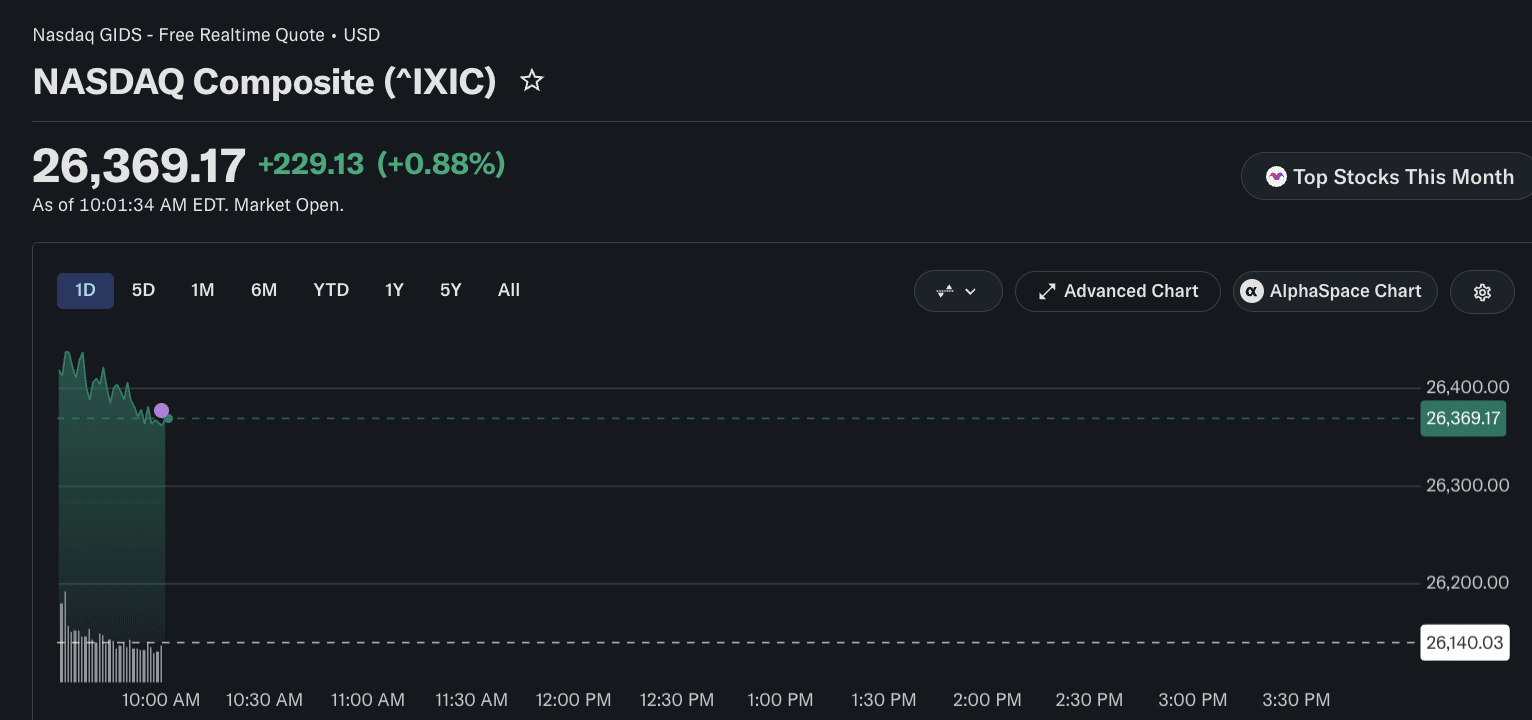
SK Hynix +4.5%, SanDisk +4.6%, Micron +3.7%, Western Digital +3.1%, Nvidia +1.4% at the US open. Dow -0.05%, S&P +0.54%, Nasdaq +0.9%. The chipmaker rebound snaps roughly 10 losing sessions — Goldman Sachs measured AI-related high-yield spreads widening 25bps last week while non-AI spreads barely moved, so the question is whether Friday’s credit stress in AI infrastructure was a correction or a beginning. Memory names leading the bounce (SK Hynix, SanDisk, Micron) are the same names that triggered Korea’s circuit breaker at -9% on Thursday — a 4-5% single-day recovery against a 20%+ weekly decline leaves the damage largely intact.
Bitcoin Sits at $82,000, Boxed Between an $84,000 Ceiling and an $80,000 Floor
Bitcoin climbed from $80,700 overnight to $83,000 early Monday, then gave most of it back within half an hour to trade at $82,188 (+0.3% over 24 hours). The $80,000 area has now held four times in five sessions ($79,800 Thursday, $80,746 Friday, weekend, $80,700 overnight). The $84,000 ceiling has rejected Bitcoin three times (October 13, 14, and this morning at $83,000 — a thousand short of the level). Monday’s half-hour round trip from $83,000 to $82,400 confirms sellers are positioned at the top of the band. Bitcoin fell only 1% Friday when the Nasdaq dropped 2.3% and Strategy lost 9.2% — it is participating in neither direction with much conviction.
Markets Turn Green on China’s 4.5% Growth as Oil Reverses Last Week’s Spike
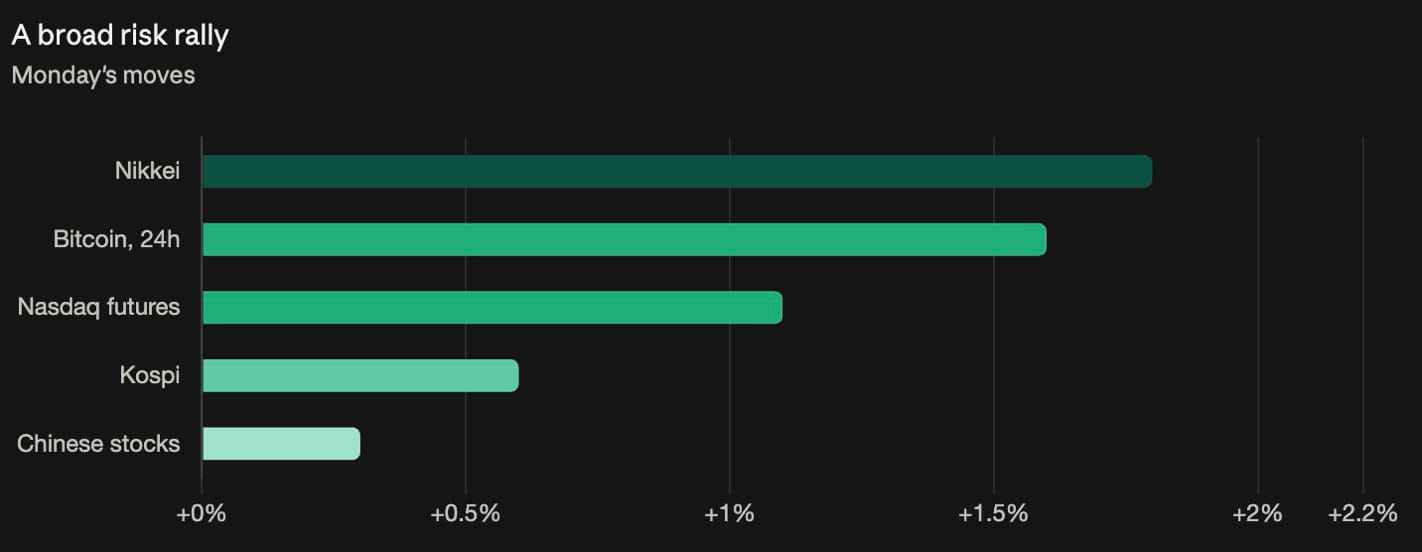
China Q3 GDP: 4.5% YoY (vs 4.3% in Q2); retail sales +1.1% (vs 0.5% expected). The retail beat is real at the headline level; at 1.1% against output growth of 4.5%, consumption remains well behind — the familiar growth model imbalance rather than a demand revival. Nikkei +1.8%, Nasdaq futures +1%+, KOSPI +0.6%. Europe moved the other way: Stoxx 600 -0.8% after weekend protests in France, with French bonds leading a European debt selloff — fiscal stress running independently of the AI credit story. Gold flat near $4,180. Dollar Index below 102 for a third consecutive session — a softer dollar has historically been a more reliable channel for digital assets than rate expectations alone, which makes the three-session decline the more useful crypto input than Monday’s risk sentiment. October hike odds remain at ~15%; December at ~90%; no cut priced at any horizon.
Altcoin Season Peaked at 63 This Year — It Needs 75, and It’s Now at 56
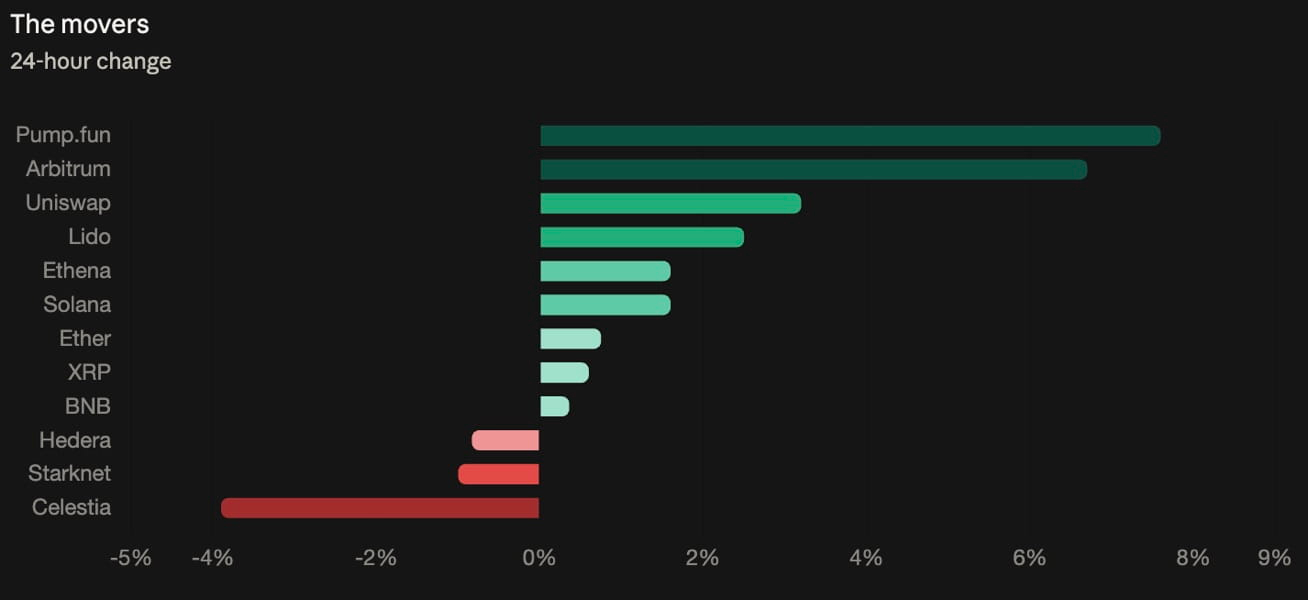
Altcoins outpaced Bitcoin roughly 2.5x Monday: CoinDesk 80 +0.9% vs Bitcoin +0.35%. Arbitrum led +6.7% following the Arbitrum Foundation’s Stablecoin Growth Program (2M ARB, ~$400K, for the first 10 teams holding $10M each in USDG — roughly $40K per team, or 0.4% on required capital). Pump.fun +7.6% with no catalyst — doubled volume in a thin market. ADA carries the only negative funding rate among majors (-8%) alongside negative CVD — crowded shorts paying to hold is the squeeze configuration if the bounce extends. The altcoin season framing needs correction: the index requires 75, peaked at 63 this year (12 points short), and has since given back 7 more to 56. 2026 has produced altcoin outperformance periods without ever producing an actual altcoin season. Monday’s derivatives signature flipped from Friday’s short-covering (OI growing slower than prices) to leverage-led (OI growing faster than prices, volume delta flat-to-negative) — fragile gains built on passive limit orders rather than aggressive buying.
KOSPI Reverses Early Slide to Close up 1.76%, Nikkei Falls; Hong Kong Shut for Holiday
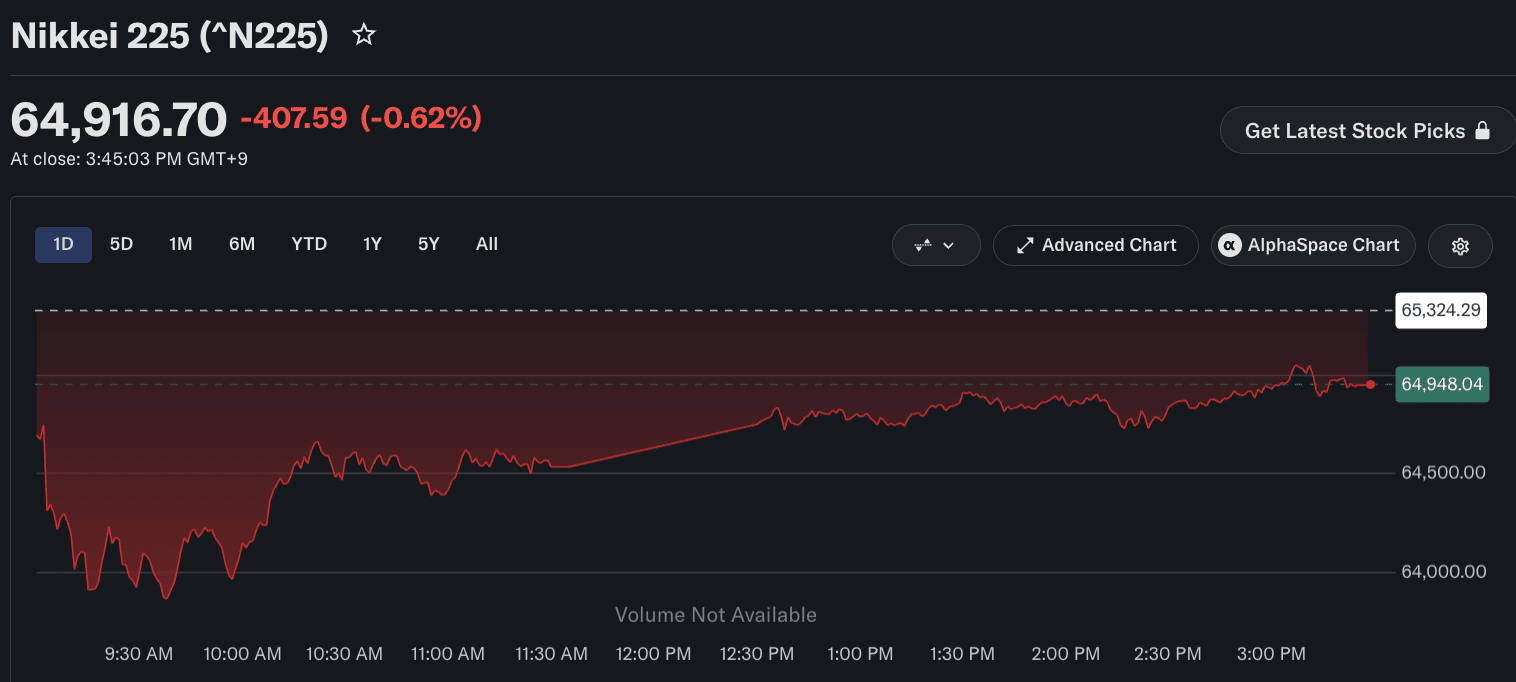
KOSPI opened -3.17% (low: 5,488.41) before institutions net bought 574.66B won to close at 5,768.01 (+1.76%, +99.96 points) — a 288-point intraday reversal. Samsung +1.16% to 218,000 won, SK Hynix +0.39% to 1.28M won, Hyundai Motor +4.49%. IBK Securities: bargain buyers in large-caps after sharp recent declines. Nikkei 225 closed -407.59 points at 64,916.70, paring an intraday loss of 1,400+ points; Tokyo Electron -2.63%, Advantest -0.23%. TOPIX closed slightly higher. Taiwan TAIEX -0.61% to 46,822; TSMC flat at NT$2,420, MediaTek -1.06%, Hon Hai -1.84%; institutional net sellers of NT$89.9B. Hong Kong closed for Chung Yeung Festival, resumes Tuesday. China: Shanghai Composite +0.39%, Shenzhen Component +0.13%, ChiNext -0.94%.