

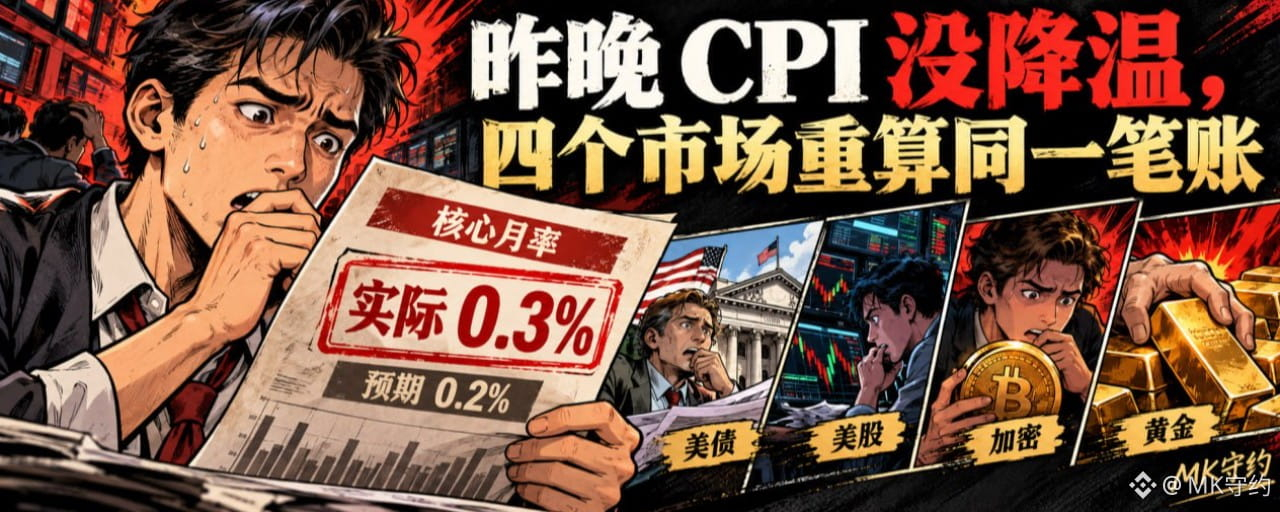


Inflation is rising—why is gold falling?
Isn’t Bitcoin supposed to hedge against inflation? Why is it falling too?
If you focused only on the “3.7%” figure last night, it was easy to misread what was happening in these two markets.
What the market cares more about is how high this inflation will push the Fed’s cost of money.
At 8:30 p.m. Beijing time on October 14, the U.S. released its September CPI report.
Headline CPI was up 3.7% year over year, versus expectations of 3.6% and a previous reading of 3.4%.
Headline CPI rose 0.6% month over month, versus 0.4% previously.
Core CPI was up 2.6% year over year, versus expectations of 2.5% and a previous reading of 2.4%.
Core CPI rose 0.3% month over month, versus expectations of 0.2% and a previous reading of 0.3%.
That final line is the gap from last night that deserves the most attention.
The market had expected core monthly inflation to fall from 0.3% to 0.2%, but it didn’t.
I. Oil is a factor, but it isn’t the only one to blame
Gasoline prices rose 9.1% month over month in September, accounting for more than half of the overall monthly CPI increase.
This shows that energy was a major driver of this inflation rebound.
But month-over-month housing inflation also rose from 0.3% to 0.4%, while core inflation excluding food and energy remained at 0.3% month over month.
The phrase “oil-price fluctuations” alone can’t fully explain this report.
Shouyue’s view is that this CPI report made the trade on “inflation gradually cooling on its own” harder to pull off.
But a tougher environment doesn’t mean the Fed will definitely raise rates at its next meeting.
The data changes policy expectations, but policy decisions also depend on employment, growth, and financial conditions. Treating a single upside surprise as proof that “a rate hike is certain” can also cost you.
II. Treasuries took an initial hit, then clawed back much of the loss
Let’s be clear about the direction first: rising Treasury yields correspond to falling prices for existing fixed-rate bonds.
After the data was released, the 10-year Treasury yield briefly surged above 5.32%, then gave back most of its gains. Short-term yields also spiked before pulling back.
This sequence is more informative than looking only at the intraday high.
In the first wave, the market reassessed the likelihood of higher rates, selling bonds and pushing yields up.
Bond prices later rebounded, showing that the initial selloff didn’t persist in full through the end of the session. Factors such as safe-haven demand and position adjustments may also have played a role, so we can’t attribute all the volatility to CPI.
For trading, the difference is significant.
A sudden intraday spike in yields is a shock.
Yields staying elevated for an extended period is what creates more persistent financing and valuation pressure.
If you only look at a chart of the first minute and say, “Treasuries tanked all night,” you’ll miss what happened in the second half of the session.
III. When U.S. stocks fall, they’re pricing in how much future profit is worth today
At yesterday’s close, the S&P 500 was down about 1.1%, the Nasdaq Composite was down about 1.9%, and the Dow was down about 0.1%. AI-related stocks led the declines.
The same CPI report didn’t hurt all three indexes equally.
When rate expectations rise, stocks whose valuations depend on profits further in the future tend to be more sensitive. The market may be willing to pay less today for $100 earned in the future.
This doesn’t mean a company’s orders disappeared the moment the data was released.
It means the market is starting to demand a higher return before it’s willing to keep taking on the risks behind these growth stories.
More importantly, after yields pulled back from their highs last night, pressure on stocks didn’t ease at the same time. Intraday observations from the New York Stock Exchange clearly documented this divergence.
So whether U.S. stocks can recover depends on both interest rates and corporate earnings. Blaming all the existing pressure on chip and AI stocks on CPI oversimplifies the issue.
IV. Crypto trades dollar conditions first; for Bitcoin, watch whether buyers step in
In a 2:30 p.m. Eastern market snapshot from the New York Stock Exchange, Bitcoin was around $81,600.
This is an intraday snapshot, not a single, standardized “closing price” for the crypto market.
Bitcoin’s long-term scarcity narrative can coexist with its short-term role as a trade on dollar liquidity.
When hotter inflation makes the market worry about higher rates and more expensive financing, investors may well cut their more volatile positions in the short term.
If leveraged longs are concentrated, falling prices could also trigger forced liquidations and amplify the shock. But without verified liquidation data, we can’t attribute all of last night’s decline to “liquidation-driven selling.”
Shouyue has consistently emphasized that BTC is the anchor of the crypto market.
BTC stabilizing is an important prerequisite for assessing whether other major coins can recover; but a steady anchor doesn’t mean all coins will rise together. You also need to look at spot buying support, trading volume, and whether the rebound has reclaimed key levels.
A bearish macro backdrop is a reason to raise the bar for going long. To actually go short, you still need to wait for price action to confirm the move.
V. Gold is an inflation hedge—so why did it fall this time too?
At the time of Reuters’ report, spot gold was down about 1.45% to $4,096.58 per ounce, while the U.S. Dollar Index was up about 0.35%.
Gold pays no interest.
If hotter inflation first lifts rate-hike expectations, bond yields, and the dollar, the opportunity cost of holding gold and pressure from its dollar-denominated price may outweigh its appeal as an inflation hedge, at least initially.
So, while gold can protect against long-term losses in purchasing power, that doesn’t guarantee it will rise on the day every time CPI comes in hotter than expected.
There’s another point here that’s easy to confuse.
You can’t simply take the “10-year nominal yield minus this month’s year-over-year CPI” and treat it as the market’s actual real interest rate. To assess pressure from real rates, look at market indicators such as Treasury Inflation-Protected Securities yields.
We can’t conclude that real interest rates rose by the same amount just because nominal yields rose intraday.
Gold’s next move depends on the combined influence of the dollar, real interest rates, and safe-haven demand. Simply saying “inflation is high, buy gold” leaves out several important calculations.
VI. What Shouyue will be watching next
I’d start by looking at short-term Treasury yields to see whether rate-hike expectations hold.
Next, look at long-term yields and the dollar to see whether financing pressure is persisting.
Then look at tech stocks and BTC: once interest-rate pressure eases, does real buying return? If bonds have recovered but risk assets are still struggling, be alert to other sources of market pressure.
Finally, watch whether gold can find sustained buying support amid changes in the dollar and interest rates.
These four markets can’t each be discussed in isolation, nor can they be forced into a pattern where they always rise and fall together.
The shared question last night was this: if inflation proves stickier than expected, is the return still worth the risk?
My response is clear.
First, acknowledge the impact of the data on risk appetite, then watch whether the market absorbs the shock. Treat intraday rebounds in the context of the intraday structure; wait for confirmation on higher time frames before making a trend call.
Don’t condemn every asset based on a single data release.
And don’t assume money has become cheap again just because of one rebound.
You may hold different assets, but they all have to answer the same question: at this price, is there enough potential return to compensate you for the risk you’re taking?