


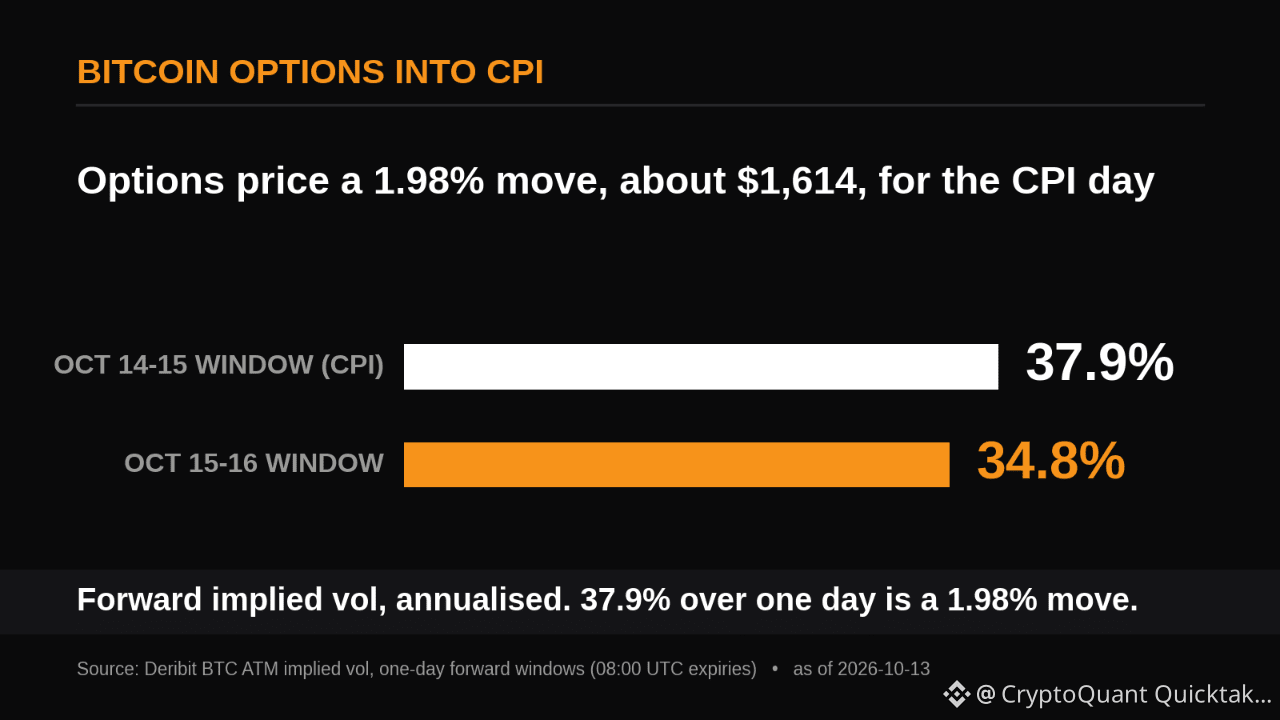
Deribit options price a 1.98% move in bitcoin, about $1,614, over the one-day window from October 14 to October 15 that contains Wednesday's US CPI release.
That figure comes from the term structure. Implied volatility for the window that holds CPI works out to 37.9%, against 34.8% for the window right after it. Traders are paying a little extra to carry options through the print, but only a little. The broader backdrop is quiet too: 30-day implied volatility is lower than on 91% of days in Deribit's DVOL history, which begins in March 2021.
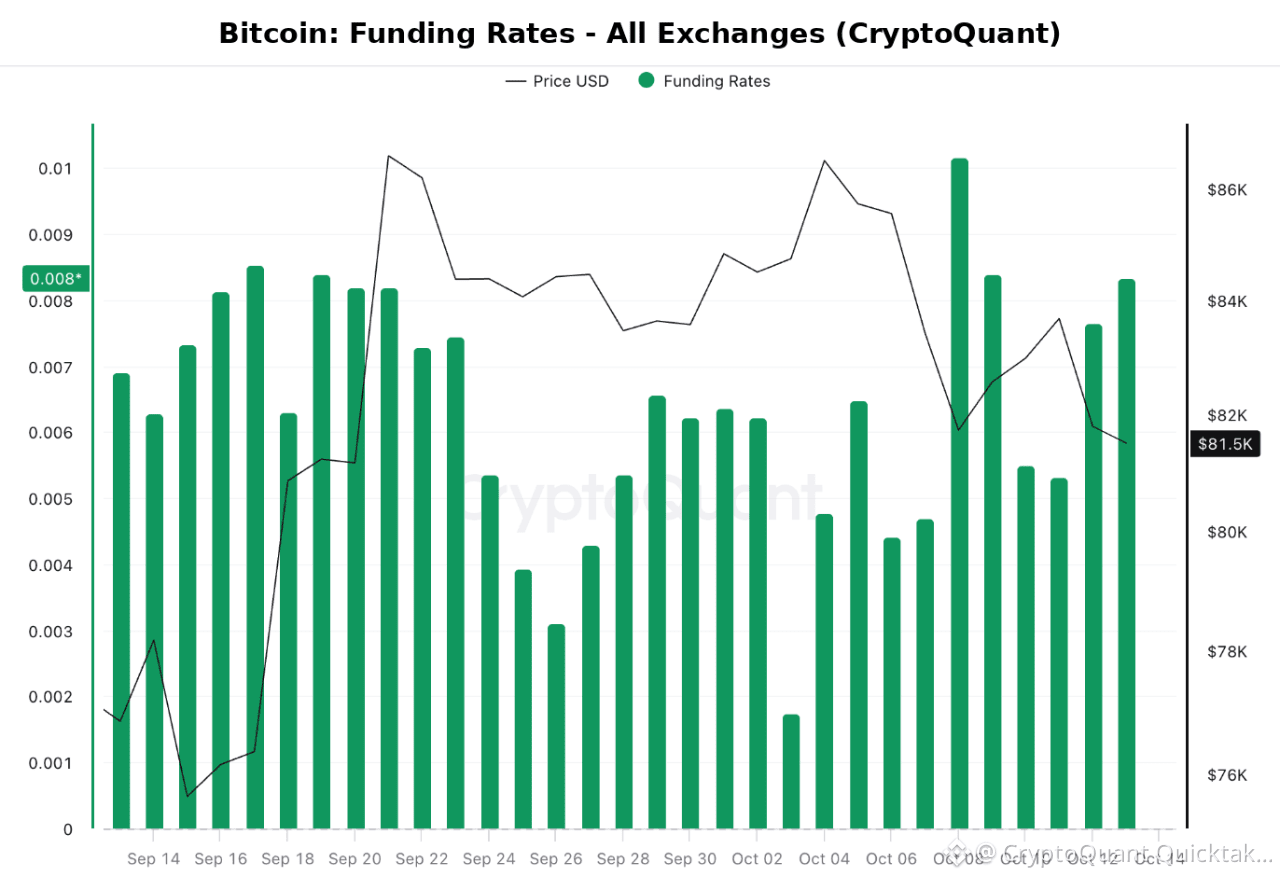
The perpetuals market tells the same story. CryptoQuant's all-exchange Funding Rates printed 0.0077% on October 12 and have stayed between roughly 0.002% and 0.010% over the past month, mostly below the 0.01% level that usually marks a neutral market. Nobody is paying up to stay long on borrowed money into the number.
A priced move is not a forecast, and a calm price is not a cheap one. Across 1,599 days of history, DVOL priced more volatility than the next 30 days delivered 73.5% of the time, by a median 10.6 vol points. Options usually overcharge for movement, so a modest CPI premium is the normal state of this market.
Options and perpetuals agree: traders are pricing a quiet CPI.
What would break that read: a move larger than $1,614 in either direction between Wednesday 08:00 UTC and Thursday 08:00 UTC would mean options underpriced the print, and funding jumping above 0.01% alongside it would mean perpetual longs chasing the move. If bitcoin stays inside that band and funding holds where it is, the calm read carries toward the October 30 expiry, where max pain sits at $78,000 against spot at $81,443. Max pain is the price at which option holders collectively lose the most, not a target.
Written by The Daily Digits