
It’s now the early hours of October 12, and the U.S. Treasury cash market is closed today.
Because it’s Columbus Day, the official curve won’t update, leaving only Tuesday and Wednesday for pricing.
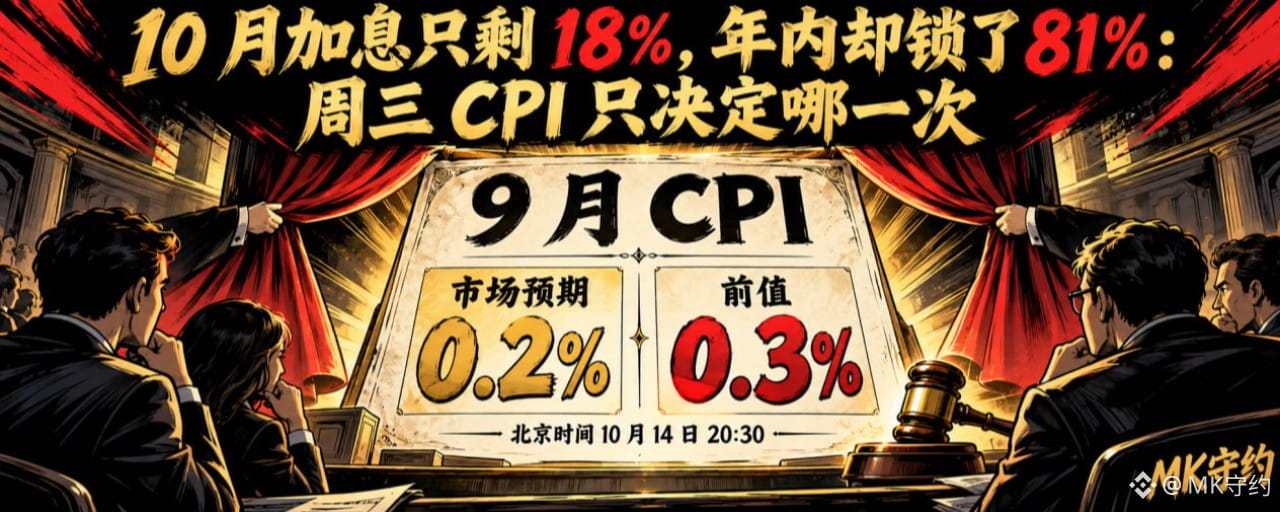
September CPI will be released Wednesday at 20:30.
The market isn’t asking whether inflation is high.
What it wants is a timeline.
By timeline, it means the data won’t change the direction—only the date of the rate hike.
On September 16, the Fed raised rates to 3.75%–4.00%, its first rate hike since 2023.
Passed unanimously, 12–0.
In the September meeting minutes, most officials thought one more rate hike this year would be appropriate.
In the dot plot, 16 of 18 officials projected at least one more hike.
But the market assigns only an 18% probability to a rate hike in October.
The market assigns an 81% probability to at least one more hike this year.
The market assigns a 0% probability to rate cuts this year.
So the disagreement isn’t about direction, only timing.
Will they act on October 28 or push it back to December 9?
The interest-rate outlook for this year has already flipped. At the start of the year, the market was betting on rate cuts; now it’s betting on when it’ll take another hit.
So what you really need to judge isn’t whether inflation will fall, but which scenario the market has already started pricing in.
Break this down to the data, and there’s just one number to watch.
This time, the deciding factor is the core monthly rate.
The previous reading was 0.3%, and the market expected 0.2%.
The core monthly rate is the deciding factor because fluctuations in energy and food can be explained away, but core inflation can’t.
The forecast for the core annual rate is 2.5%, versus 2.4% previously.
The forecast for the headline annual rate is 3.6%, versus 3.4% previously.
The forecast for the headline monthly rate is 0.6%, versus 0.4% previously.
So the market expects inflation to accelerate, not fall.
And long-term yields have already started charging for this risk.
The 10-year Treasury yield is 5.24%, and the 30-year is 5.60%.
The shorter maturities are also hovering around 5%.
The entire yield curve slopes upward.
There are two explanations for elevated long-term yields: inflation, or the supply of government debt issuance.
These two explanations have completely opposite policy implications, so long- and short-term yields are telling different stories right now.
If a data release can support two interpretations at once, the volatility it creates will surely be greater than the move in either direction alone.
Long-term yields are hedging against inflation.
Short-term yields are waiting on jobs data.
The 10-year Treasury yield touched 5.342% on October 1, its highest level since early 2002.
The 10-year real yield is 2.91%.
The real rate means that borrowing costs remain very high even after inflation is taken into account.
That’s the pin weighing down gold and equity valuations.
Here’s another angle that’s rarely discussed: inflation expectations.
In the University of Michigan’s preliminary October survey, the 1-year inflation expectation is 4.7%, versus 4.6% previously.
The 5-to-10-year inflation expectation is 3.5%, versus 3.4% previously.
Both are moving higher.
Inflation expectations are what the Fed least wants to see get out of control; they’re harder to bring back down than inflation itself.
Expectations are harder to bring down than prices.
But the current conditions index in the same report fell to 44.7.
A sharp drop from the previous reading.
Expectations are rising while current conditions are collapsing.
This isn’t a soft-landing curve; it’s a stagflation curve.
So there’s no consensus within the Fed either.
One official described September’s rate hike as insurance against persistent inflation.
Some officials also said it was to prevent energy prices from feeding through to other areas.
Last week’s jobs data didn’t support further tightening: nonfarm payrolls increased by just 29,000 in September.
Core PCE rose 0.2% month over month in August, also below market expectations.
Energy has been the least well-behaved component in recent weeks, with oil prices up about 14% in September.
So this is where things stand: inflation expectations are rising, employment is weakening, and neither can be ignored.
So what should you be watching now?
Here’s what’s happening across asset classes.
The dollar index is at 102.23, stuck below 102.50.
This time, the dollar hasn’t moved in step with interest rates; it’s been stuck around this level for days.
Gold is at $4,205 on Binance perpetuals, with an intraday high of $4,212.
Gold holding above $4,200 despite a 2.91% real yield is worth thinking about for a moment.
The S&P 500 is at 7,811, and QQQ, the Nasdaq 100 ETF, is at $751.
The S&P 500 and Nasdaq don’t rise on earnings alone; they also rely on low discount rates.
Both are still in historically high ranges.
Bitcoin is at $83,700, with $51.95 billion in open interest.
Funding rates are just 0.0026%, and the large-trader long/short ratio is 1.55.
There’s only $31.56 million in orders sitting at the $84,450–$84,500 level overhead.
That wall is thin.
It’s easy to break higher.
The structure of this crypto rally is completely different from last year’s; leverage has already been flushed out once, so volatility is lower.
Valuations haven’t been flushed out.
Finally, here’s my outlook.
If the core monthly rate is 0.2%, pricing for no move in October and a hike in December will hold.
The dollar will ease first, with gold benefiting before crypto.
Long-term yields may not fall in tandem, because the debt issuance situation hasn’t changed.
Even a drop to 0.2% shouldn’t be read as good news; it would only push the issue to December.
If the core monthly rate is 0.3% or higher, bets on a rate hike in October will return.
The dollar is set to test above 102.50, and the 10-year Treasury yield could test 5.342%.
Conversely, 0.3% wouldn’t mark the start of a collapse either; it would simply bring the timeline forward by a month and a half.
Crypto won’t be the biggest casualty then.
Crypto funding rates are just 0.0026%, so leverage is thin.
Valuations are most vulnerable: the S&P 500 and Nasdaq are both near highs, and rising rates will hit them first.
The difference between the two scenarios for crypto is in the timing, not the direction.
So I can’t offer certainty either.
That’s why I’m not giving you a definitive call in this piece.
So on Wednesday night, you only need to watch three numbers.
Core CPI month-over-month, the dollar at 102.50, and the 10-year Treasury yield at 5.342%.
You only need to watch which of the three numbers breaks first.
Until then, don’t assume inflation is falling.
And what you should still be worried about is your own leverage.
—MK守约